News
Elon Musk and Jeff Bezos: The Rivalry of the Century (that we are all benefitting from)

Elon Musk and Jeff Bezos have shared an extremely public rivalry throughout the past few years, aiming to one-up each other in space exploration and self-driving cars. The two men, who own the top two positions on Forbes’ Billionaires List, are chomping at the bit to get ahead of one another, and the competition that lies within the Tesla and Amazon CEOs gives the people of Earth all something to benefit from: longevity and innovation.
The two most powerful men in the world in their respective sectors, Bezos being at the helm of the most dominating company in the e-commerce world, and Musk surging forward the acceleration to sustainable energy with Tesla. There is a lot of money, a lot of power, and a lot of reputation at stake, and the rivalry between the two men is mostly comprised of healthy competition to out-do the other. However, the two men share a similarity in their strategy to help humankind move forward, and it lies within their aerospace companies: Musk’s SpaceX and Bezos’ Blue Origin. But it isn’t a competition that has always been healthy and in good spirits. It has often resulted in name-calling and Twitter contradictions, showing that even the two richest men in the world can share a very public rivalry while benefitting the rest of us.
In past years, Musk has been the more successful entrepreneur in the space exploration and self-driving vehicle front, of course. His two companies being Tesla, the largest car company in the world in terms of market cap, and SpaceX, which has been launching satellites for global internet service with Starlink and sending astronauts to the International Space Station on several missions. It is no secret that Musk has an astounding lead over Bezos in those sectors, and he doesn’t have any intention of selling consumer goods, even though he would encourage competition in that market after calling Amazon a monopoly.
Time to break up Amazon. Monopolies are wrong!
— Elon Musk (@elonmusk) June 4, 2020
But Musk’s lead must leave a small portion of Bezos feeling left out. Musk undoubtedly receives more recognition and more kudos for his work, and he should. He’s made legacy automakers change their strategies moving forward, forcing them to work on all-electric powertrains, and SpaceX has made the possibility of human space travel possible again. Bezos, being the extremely successful person that he is, must thrive off of competition and the work that it takes to make things more efficient and better than anyone else.
In the early 2000s, both Musk and Bezos were struggling entrepreneurs who worked to grow their entities into the world’s biggest and most successful companies. Bezos, who once held an office in a shady part of Seattle above a Chinese food restaurant, had a desk that wasn’t level, and an uneven canvas on the wall that said “amazon.com” in blue spraypaint. He drove a run-of-the-mill sedan and shared an incredible joy for his work, which was then just an online bookstore.
Jeff Bezos reveals Rivian’s plans to produce electric vans for Amazon
Meanwhile, Musk was fresh out of his sizeable sale of PayPal. He reinvested his money into Tesla, and he was sleeping on the floor of his office building. Showering at the YMCA in Los Angeles, Musk and his brother Kimbal were also subjected to startup life’s genuine struggle: long hours, less-than-luxurious living conditions, and minimal pay.
Fast forward a few years, and the two men are among the most powerful people on Earth thanks to their influence on their respective sectors. But what is really driving things forward between the two men is the competition they share with one another. The constant need to outperform the other person is evident, and the two men’s based opinions constantly encourage the other one to work a little harder.
In the end, the personal rivalry has benefitted us all. SpaceX and Blue Origin are both doing things to accelerate the possibility of normalized space travel. Amazon is making consumer goods easy to obtain, and Tesla is making electric cars fun, fast, and affordable.


SpaceX reported its third-quarter 2026 financial results on October 20, posting the company’s first solidly profitable quarter since going public earlier in the year under the ticker $SPCX.
Revenue reached $14.58 billion, up 161 percent year-over-year from $5.6 billion, and well ahead of consensus estimates in the $12.7 to $12.9 billion range. The results highlight a rapid shift in SpaceX’s center of gravity toward artificial intelligence/super intelligence, while Starlink and traditional space operations continue to show robust progress.
Here are the key financial results for the quarter:
- Revenue of $14.58 billion (+161% YoY)
- Adjusted EBITDA of $8.8 billion (+306% YoY)
- GAAP net income of $4.4 billion (versus a $1.1 billion net loss in the prior-year quarter)
- Adjusted EPS of approximately $0.35 (versus roughly $0.13–0.16 expected)
- Income from operations of $2.8 billion
The AI/SI segment generated $7.56 billion in revenue, an 830 percent year-over-year increase, making it the company’s largest segment for the first time. Growth was primarily driven by the activation of major cloud services agreements, the integration of Cursor (acquired earlier in 2026), and rising usage of Grok models and the newly introduced Grok Bot personal agent.
🚨 SpaceX just reported earnings! Here are some highlights:
Financial:
Revenue $14.58B (+161% YoY) vs. consensus ~$12.7–12.9B
Adjusted EBITDA $8.8B (+306% YoY)
GAAP net income $4.4B (vs. prior-year loss; first solidly profitable quarter post-IPO)
Adjusted EPS ~$0.35 vs. ~$0.13–0.16 expectedSegments:
Super Intelligence (SI, formerly AI): $7.56B (+830% YoY) — now the largest segment, driven by cloud contracts, Cursor, and Grok.
Connectivity (Starlink): $5.25B (+69% YoY).
Space: $1.77B.Other highlights:
Starlink subscribers: 13.6M (+89% YoY).
Nameplate compute: 1.7 GW.
Capex: $19.6B (majority AI infrastructure).
Cash & marketable securities: ~$90B.
First revenue-generating Starship mission (26 V3 Starlink satellites, ~10× Falcon 9 downlink capacity per launch).— TESLARATI (@Teslarati) October 20, 2026
SI adjusted EBITDA reached $5 billion, and nameplate compute capacity stood at 1.7 GW at quarter-end, up from 1.4 GW in June and 0.6 GW a year earlier. Capital expenditures totaled $19.6 billion, with the majority allocated to AI infrastructure, including continued expansion of the Colossus facilities.
The Connectivity segment, which primarily surrounds Starlink, produced $5.25 billion in revenue, a 69 percent year-over-year and 22 percent sequentially. These are pleasant results to see and expected, considering how many airlines have adopted Starlink over the past year.
Starlink consumer subscribers reached 13.6 million, an 89 percent increase from the prior year, and a sequential gain of 1.6 million. Consumer average revenue per user improved to $69. Meanwhile, Enterprise and Government revenue also grew strongly, and Starlink is now installed on more than 3,800 aircraft, making internet more accessible and better performing than previous options.
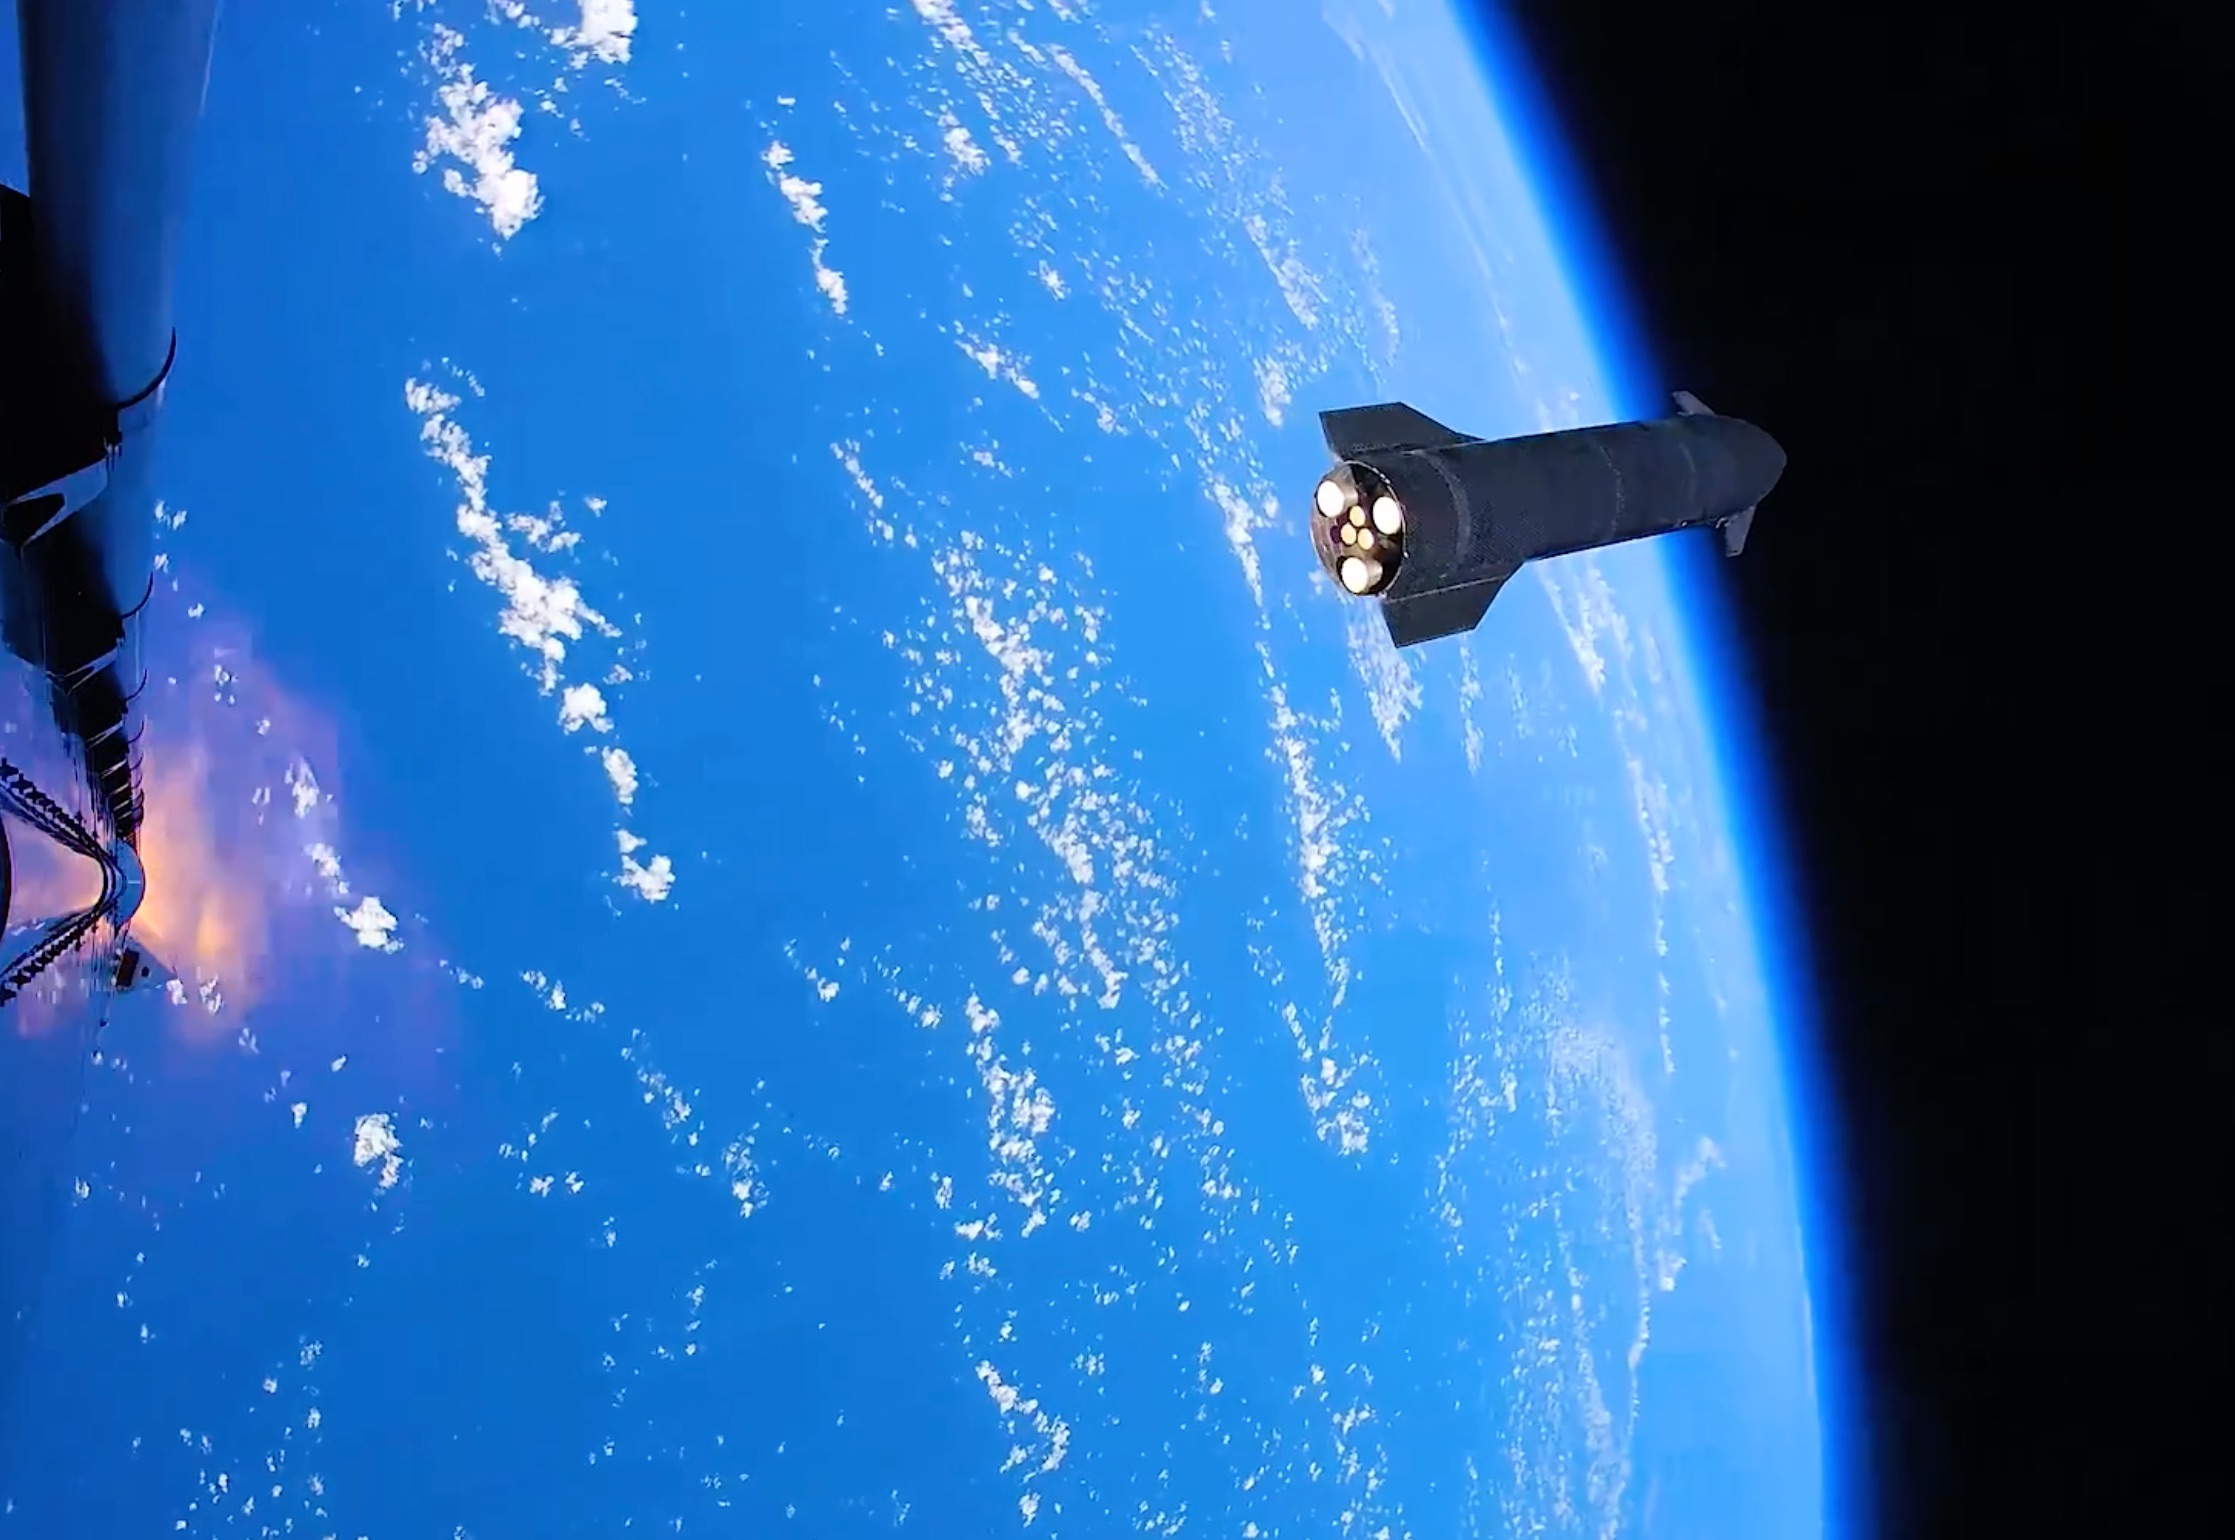
The Space segment also performed well and contributed $1.77 billion in revenue, up 6 percent year-over-year and 84 percent sequentially. A major milestone was the successful first revenue-generating Starship mission (Flight 14), which deployed 26 V3 Starlink satellites. Those satellites added roughly 10 times the downlink capacity of a typical Falcon 9 Starlink launch.
SpaceX completed 12 customer launches during the quarter, including NASA’s Nancy Grace Roman Space Telescope mission, and continued to grow its backlog of crewed, national security, and commercial flights.
CFO commentary noted that the combination of launch leadership, recurring Starlink revenue, and rapid SI expansion is producing meaningful operating leverage.
The company ended the quarter with roughly $90 billion in cash and marketable securities, providing substantial resources for ongoing investment while targeting an investment-grade balance sheet. Sequential revenue nearly doubled from the $7.81 billion reported in the second quarter, illustrating the pace of the AI-driven acceleration. Things are looking strong for SpaceX.
What’s incredibly striking is the fact that SI has grown to be larger than the rest of the company in such a short amount of time. CEO Elon Musk said on the earnings call that Grok Bot is the “fastest-growing product I’ve ever seen,” so it seems that it could be a true keystone of SpaceXSI over the next few years.
SpaceX (NASDAQ: SPCX) will report its second public earnings call today since its IPO earlier this year, and there are a few things we expect to hear about, as well as Wall Street analysts, who have already outlined their expectations for the call.
Wall Street analysts have a consensus of $12.72 billion in revenue and an earnings per share (EPS) of $0.13. These are broken down into three sectors: Space, Connectivity, and AI/SI, which are perceived in this way:
- Space: $1.41 billion
- Connectivity: $4.84 billion
- AI/SI: $6.47 billion
Other outlets cluster near $12.8 or $12.9 billion in revenue and $0.14 – $0.15 EPS. This implies a roughly 65 percent sequential growth from Q2’s $7.81 billion, driven mostly by AI/SI, with the first post-IPO positive EPS expected.
Here are the three things to watch for on the call:
AI Revenue Ramp and the $100B+ ARR target
AI is truly the swing factor for SpaceX, and analysts expect it to roughly double from Q2’s $2.56 billion and become about half of total revenue. Management previously guided to a $100 billion+ annualized run rate by December, including the Cursor acquisition, which was $60 billion, to close the quarter.
Listen for updates on SpaceX’s compute capacity, especially pertaining to its contracts with Google, Anthropic, and others, revenue per watt, any new deals, and Cursor’s early contribution.
Starlink/Connectivity Metrics and Mobile Expansion
Connectivity remains a main profit engine for SpaceX. Subscriber additions will be something to pay attention to, as Q2 ended at 12 million and previews are looking at 14 million for this quarter. Additionally, ARPU trends, enterprise and government growth, and any commentary on Starlink Mobile will be something to pay attention to, especially following the recent low-band spectrum deal and FCC-related constellation approvals.
Capex Trajectory, Cash Burn/FCF, and Starship/Operational Updates
Q2 capex of roughly $18.4 billion weighed on the stock. Investors will look to scrutinize Q3 spending levels, any guidance on the pace into Q4/2027, free cash flow, backlog, and liquidity. Operational color on Starship (Flight 14 milestones and Flight 15 timing/reusability progress), Falcon cadence, and government/NASA contracts are also in focus.
Of course, there will also be some speculation on the potential Tesla-SpaceX merger, but there was nothing mentioned in the company’s proxy it sent earlier this week.
SpaceX will report earnings after market close today and will stream the call on X.
Watch live as SpaceX discusses our Q3 2026 earnings at 3:30pm CT today → https://t.co/Qrb0qeVG15
— SpaceX (@SpaceX) October 20, 2026
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here
News
SpaceX just launched its secret Starfall saucer again
SpaceX launched its Starfall capsule again on Bandwagon-5, this time listed openly beside rideshare customers.

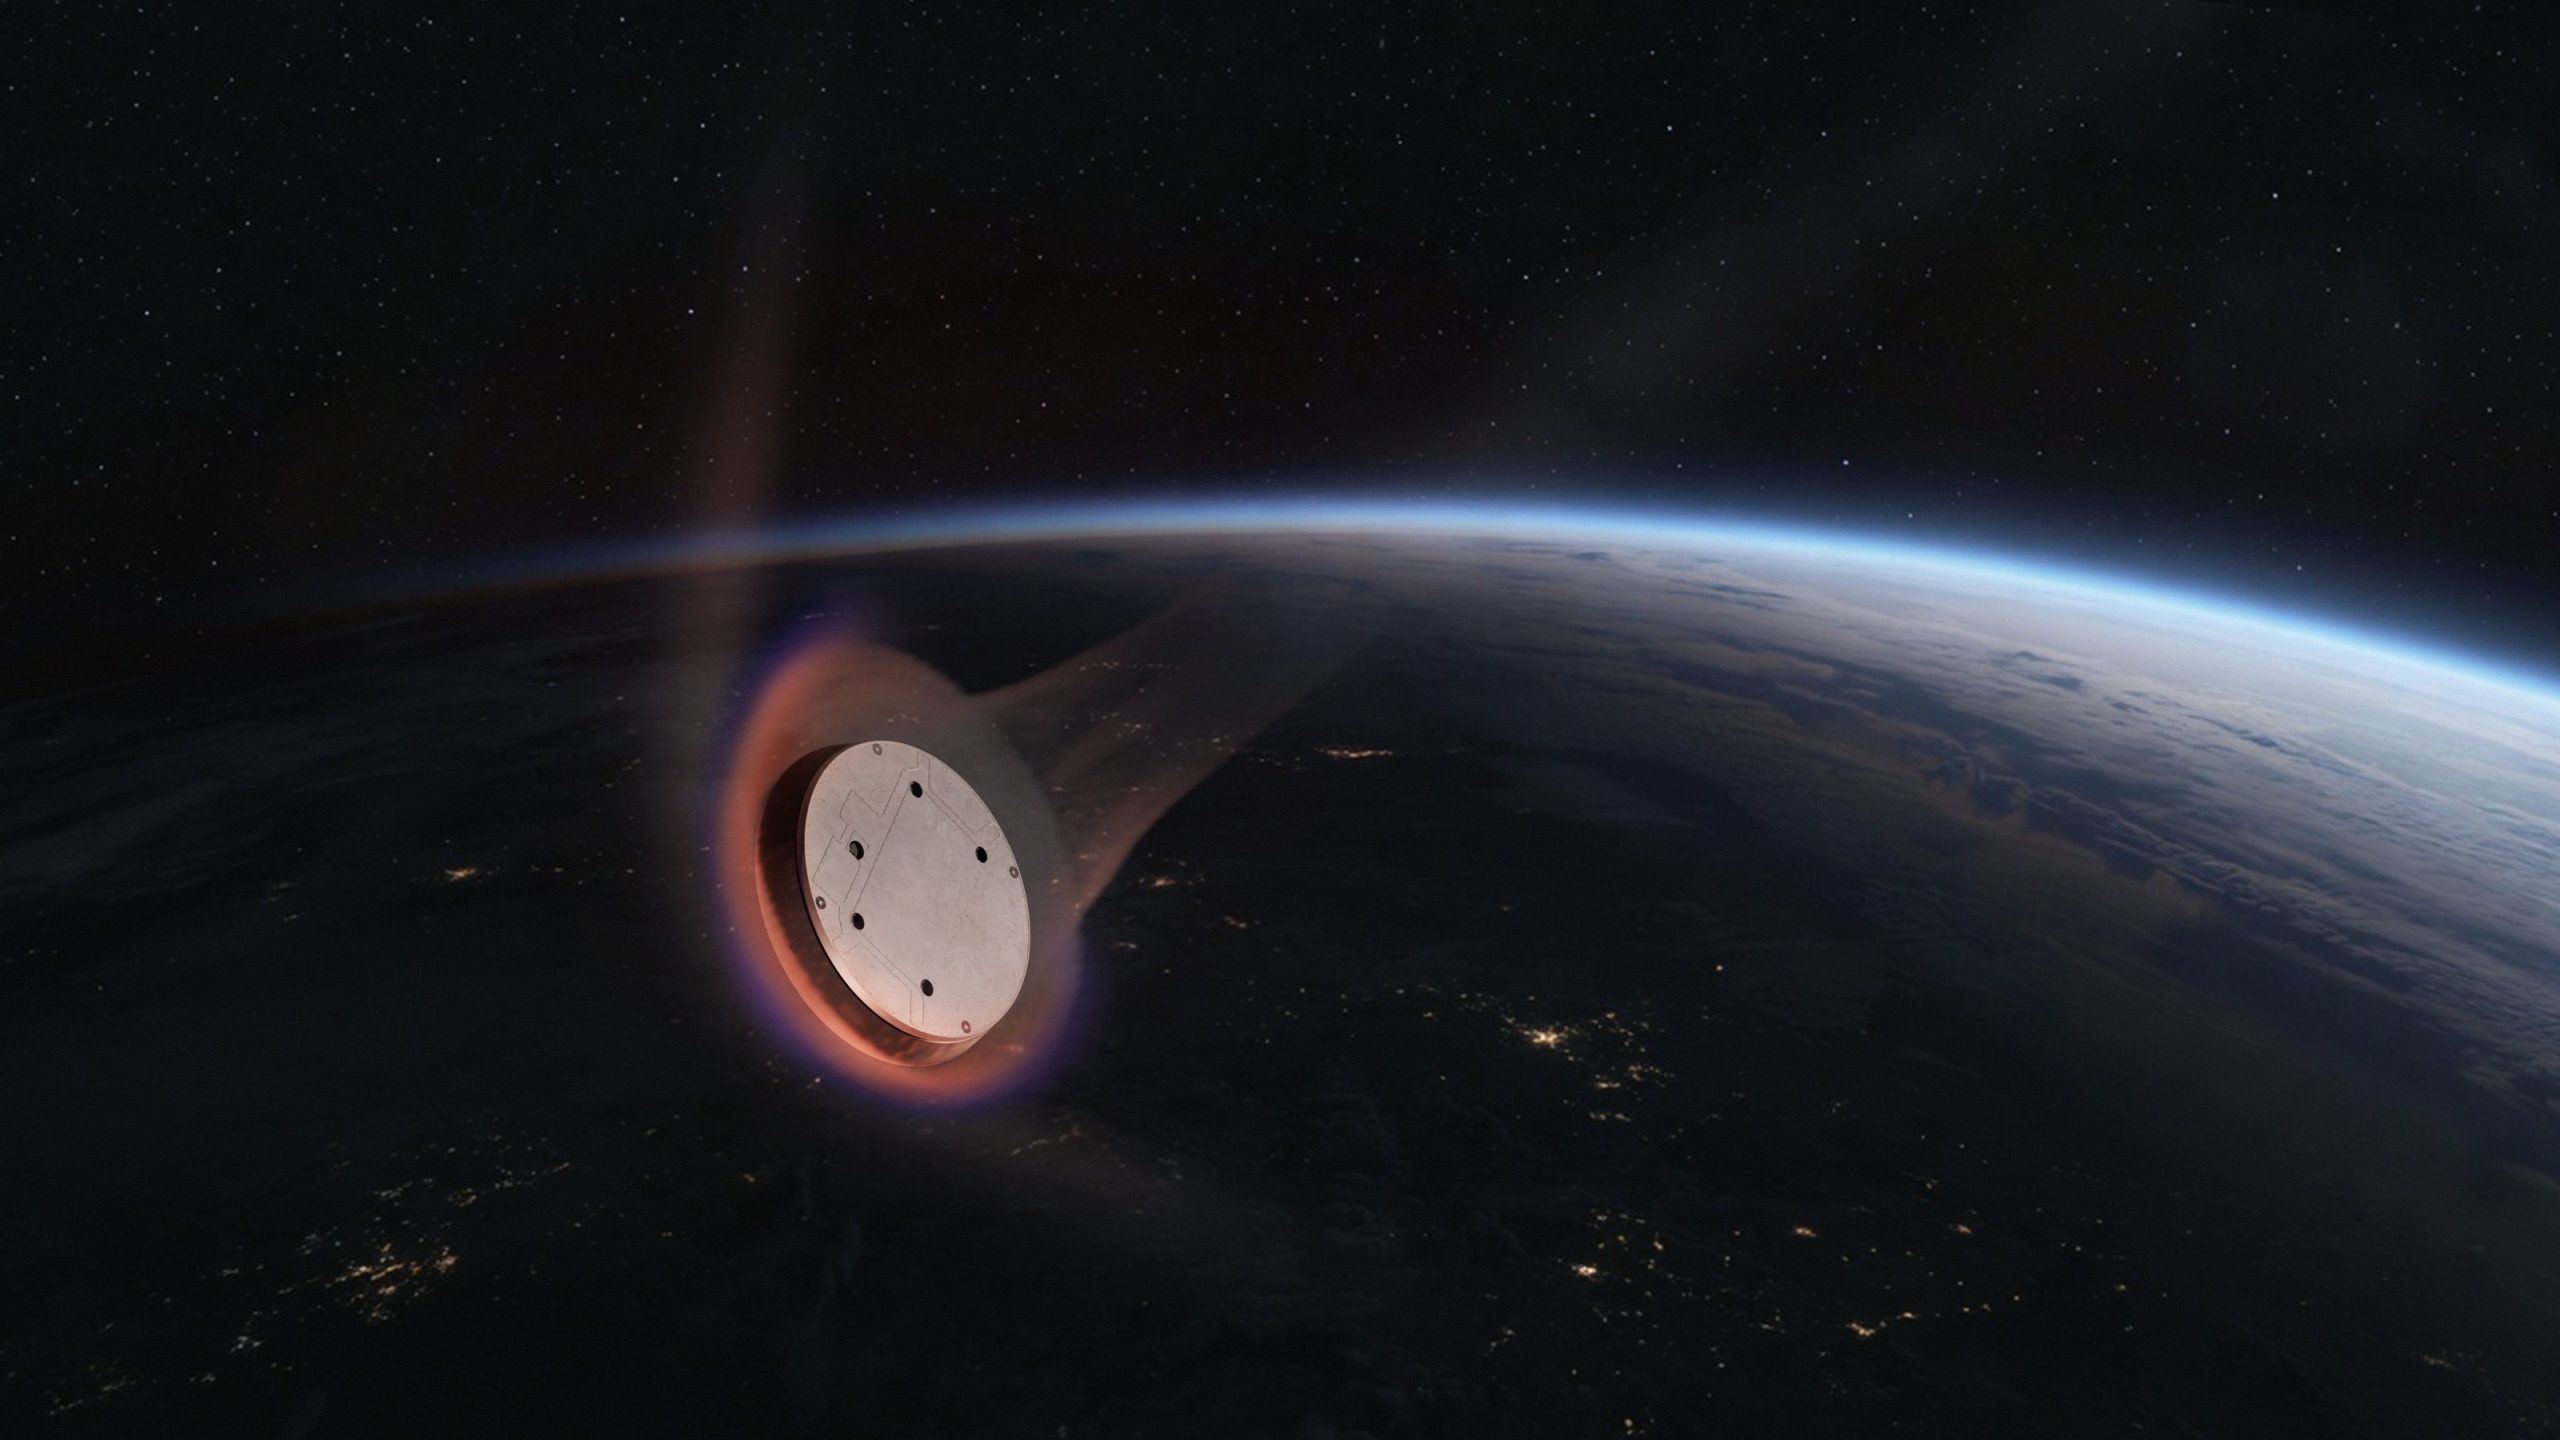
SpaceX launched its Starfall reentry capsule for the second time on Tuesday morning, flying it as the payload of the Bandwagon-5 rideshare mission. Falcon 9 lifted off from Space Launch Complex 40 in Florida at 7:04 a.m. ET with 32 payloads, and the first stage booster, on its 19th flight, landed on the droneship A Shortfall of Gravitas about nine minutes later.
Starfall was scheduled to separate last, 2 hours and 48 minutes after liftoff. The final customer satellite on SpaceX’s mission timeline comes off the upper stage about an hour and nine minutes in, which left a long gap before the capsule was due to be released alone. SpaceX later posted that the payload deployment sequence is complete. At liftoff, the company said Starfall “enables affordable, routine access to a microgravity environment, providing unique opportunities for on-orbit manufacturing, scientific research, and testing.”
Starfall enables affordable, routine access to a microgravity environment, providing unique opportunities for on-orbit manufacturing, scientific research, and testing https://t.co/y8kJg3QDor
— SpaceX (@SpaceX) October 20, 2026
As Teslarati reported before the first Starfall flight, SpaceX made no public announcement about the vehicle then, and nearly everything known came from FAA and FCC filings. This time Starfall is an item name on the official mission page, listed beside paying rideshare customers. SpaceX has still not said what, if anything, is aboard this Starfall, Spaceflight Now noted.
The FAA’s environmental assessment from May describes a disk about 10.2 feet wide and 2.5 feet tall that weighs roughly 4,600 pounds and can bring 2,200 pounds of payload back to Earth.
Interestingly, the same rocket also carries a competitor’s hardware. Varda Space Industries launched its W-Series 7 capsule on Bandwagon-5, a spacecraft about three times smaller than Starfall that will test whether microgravity can improve the solubility of a cancer drug called Protac. It is Varda’s ninth reentry capsule, and W-8 and W-9 launched earlier this month on Transporter-18. SpaceX has been Varda’s launch provider since the company’s first Falcon 9 rideshare contract in 2021.
SpaceX has not published where or how this Starfall will come down. The preview we ran in June described a recovery from the Pacific Ocean, and the company has not said whether this flight follows the same plan. The launch also arrives hours before SpaceX posts its third quarter results after the market closes, a report we previewed earlier this week.

SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms

SpaceX reports its second earnings today: here’s what to expect

SpaceX just launched its secret Starfall saucer again

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


