Investor's Corner
Oil Prices Sinking Tesla Motors Stock?

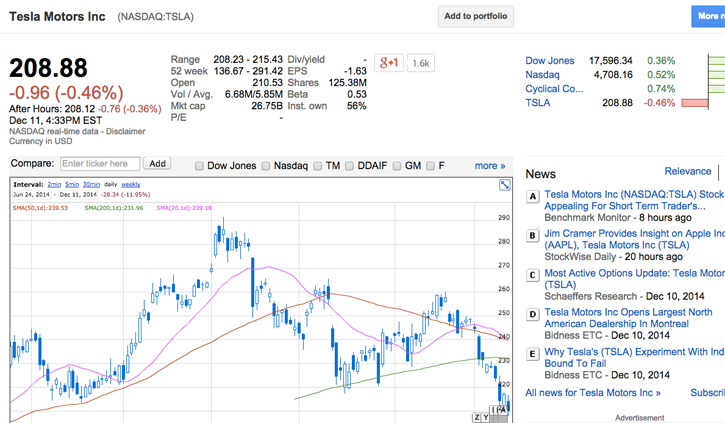
As I was watching a recent webinar on forward-looking trending tools for stocks, the moderator popped Tesla Motors stock chart on the screen to demonstrate the Fibonacci retracement and Ichimoku tools. Perfect timing, I’m a long investor in Tesla Motors stock and what about these downward oil prices?
Financial media sites are in a tizzy regarding oil prices plummeting—Saudis pulling the strings—and how this poses a big hurt for electric car industry sales and, of course, Tesla Motors stock price. Sine I cover the oil and gas industry for the Chicago-based Automation World magazine, the Saudis’ primary “displacement” target is U.S. shale.
Fracking shale plays are very expensive due to the fact that oil and gas drilling companies have to setup so many wells in order to find shale sweet spots. Plus, these small-to-medium sized drillers are financially over-leveraged and need barrel prices to be somewhere around $80 a barrel in order to be profitable. That’s not going to happen for some time, did I say “displacement.”
However, it does begs the question whether there is a decent correlation between high gas prices and electric car sales in the last four years, and will lower gas prices doom Tesla Motors’s stock price for the near-term or long-term?
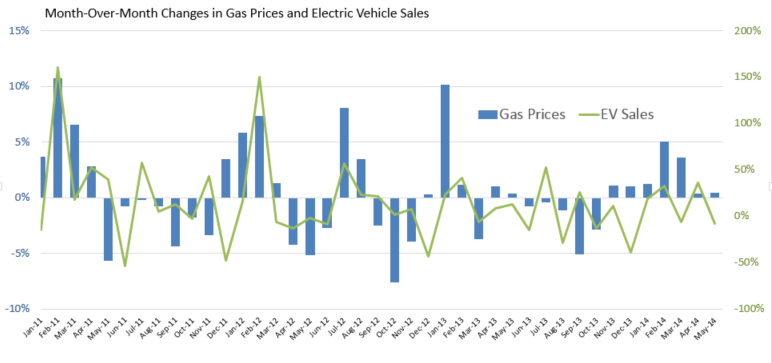
Source: Energy Information Agency
As a Energy Information Agency chart shows above, there’s not a direct correlation between sales and increase gas prices. However, I believe some EV automakers will take a hit from really low gas prices in 2015–say $2.10-2.20– but not Tesla Motors.
Why? Tesla Motors owners are not obsessed with the price of power for their car, compared to a Volt or Leaf owner is my theory, and this car just won the award for the highest satisfaction from Consumer Reports, two years running.
Plus, Americans are buying more expensive cars, north of $50,000. TrueCar just this week released data on buying patterns and showed:
From January through November 931,064 vehicles were sold in the U.S. with average price above $50,000, a whopping 30.8 percent increase compared to the same period last year, according to TrueCar.
So with lower oil prices soon to be a non-issue or baked into Tesla’s current stock price, is it attractive at $210 or lower? How long will this downward, selling pressure last?
Ishimoku technicals (forward-looking indicators) point to new lows being tested in the near term, such as the $203 level. So Tesla shorting could continue and recent data shows 23% of Tesla stock owners were shorting in November.
According to John Del Vecchio and Tom Jacobs’ book What’s Behind the Numbers? (via a Nasdaq.com article), this is why you short a stock:
We recommend waiting until there is aggressive revenue recognition, weakening balance sheets, and deteriorating cash flow trends. It’s the flipside of value-with-catalyst, which is fundamental analysis of value combined with a catalyst for stock market buying to boost the price to realize that value.
As most Tesla Motors investors and followers know, the company’s cash flow is quite positive and revenue is on solid-footing with production capacity investments made in 2014, and the company’s estimate of 50,000 vehicles delivered in 2015. In 2014, Tesla will probably deliver just under 35,000 vehicles, a solid increase.
So there may be an opportunity to buy in the near-term for longs, as I feel the oil price “news” won’t really affect Tesla sales in 2015. One caveat, although, is to keep an eye on Model X news and possible struggles in hitting a 250 mile range for this coveted SUV. This could dampen the stock price if problems persist.



Tesla (NASDAQ: TSLA) reported its earnings for the third quarter of 2026, marking a reasonable performance on the various financial metrics. Tesla still plans to hold a call that will field investor questions at 5:30 p.m. ET, 4:30 p.m. CT.
Here’s where Earnings came in:
- Total Revenues: $28.046 reported vs. $28.34B expected
- Non-GAAP EPS: $0.48 reported vs. $0.45 expected
- Operating Margin: 2.6 % reported vs. 2.5% expected
- Operating Income: $718M reported vs. $721M expected
- Free Cash Flow: $1.531B reported vs. ~-$4.51B expected
Tesla $TSLA Earnings Results:
Revenues: $28.046B
Non-GAAP EPS: $0.48
Operating Margin: 2.6%
Operating Income: $718M
FCF: $1.531B— TESLARATI (@Teslarati) October 21, 2026
Major Takeaways
Full Self-Driving (Supervised)
“FSD (Supervised)⁴ attach rate continued to grow, reaching over 75% of new vehicle deliveries in North America – our most mature market – a nearly twenty percentage point sequential increase. We believe that FSD is driving demand in markets where it is available, and we continue to work with regulators to get it approved in other markets.”
Tesla Semi
“We began volume production of Tesla Semi, our Class 8 heavy-duty truck. The top variant can go 500 miles at full 82,000 lbs gross combination weight while achieving an efficiency of 1.7 kWh/mile. That efficiency allows the Tesla Semi to use a third of the energy used by a comparable diesel truck to haul the same payload. In a transportation market where energy is one of the largest components of total cost per mile, this will provide a meaningful advantage to Tesla Semi operators.”
SI Compute
“We plan to reach 400 MW of SI training compute by the end of the year, supporting the development of both vehicle and humanoid robot autonomy software. Additionally, we continued construction for the Austin Fab, where we plan to start commissioning equipment in 2027.”
Robotaxi
“We began deployment of Cybercab into our Robotaxi fleet in Austin. We reached nearly two million cumulative unsupervised miles for our Robotaxi service as of the end of the quarter. Operating hours in Austin are now 6am to midnight, and we expect to reduce wait times via increased fleet supply and improvement of Robotaxi orchestration algorithms. Grok is available in Cybercab with access to Grok Bot and Connectors, which allows users to manage their inbox, calendars, files, chats and tasks – all hands free via voice command – making Cybercab a mode of transport, a productivity space and, with our entertainment options, a second living room.”
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.
Wall Street analysts rapidly raised price targets on SpaceX (NASDAQ: SPCX) after the company reported a bullish third quarter for 2026 following the market close on October 20. Shares were sent sharply higher in after-hours and premarket trading.
SpaceX posted revenue of $14.6 billion, a 161 percent year-over-year increase that comfortably topped consensus estimates, which fell near $12.7 billion. The company also posted a net profit of $4.4 billion from a prior-year loss, with adjusted EBITDA reaching $8.8 billion.
More price target movement:
🚀 Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
🚀 Barclays raised its target to $300 from $254 (Overweight).
🚀 Citi increased its target to $240 from $200 (Buy),
🚀 UBS moved to $230 from $210 (Buy)
🚀TD Cowen raised its target to $224 from $200 (Buy).
🚀Morgan Stanley held an Overweight rating with a $300 target.
🚀Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.— TESLARATI (@Teslarati) October 21, 2026
Its Super Intelligence (AI) division generated roughly $7.6 billion and became the largest revenue contributor, growing nearly 830 percent year-over-year, while the Connectivity segment delivered $5.2 billion on strong subscriber additions that lifted the consumer base to 13.6 million for Starlink.
The Earnings Call proved especially catalytic, as CEO Elon Musk and CFO Bret Johnsen outlined Q1 2027 revenue guidance of $33 billion to $37 billion, which was far above the roughly $22 billion analysts had modeled, alongside fourth-quarter capital-expenditure plans of $35 billion to $40 billion focused on AI compute infrastructure at sites including Memphis and Southaven.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
Management targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end and discussed pathways to 13 gigawatts or more by the end of 2027. Musk described relentless demand from hyperscalers and other customers, with compute pricing supporting payback periods of less than a year and potentially as short as six months.
Additional highlights included Starship’s recent orbital success and V3 satellite deployment, Starlink pricing and enterprise momentum, rapid Grok Bot adoption, spectrum expansion plans, and the formation of special committees to explore a possible combination with Tesla.
These elements prompted a wave of price-target increases:
- JPMorgan more than doubled its target to $500 from $240 while maintaining an Overweight rating.
- Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
- Barclays raised its target to $300 from $254 (Overweight).
- Citi increased its target to $240 from $200 (Buy),
- UBS moved to $230 from $210 (Buy), and
- TD Cowen raised its target to $224 from $200 (Buy).
- Morgan Stanley held an Overweight rating with a $300 target.
- Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Shares, which closed at $147.79 on October 20, jumped roughly 8 percent in early premarket trading on October 21 as investors digested the results and the newly elevated Street targets.
The average analyst price target has moved higher, which reflects greater conviction in SpaceX’s trajectory across launch, connectivity, and the Super Intelligence business, even as elevated spending remains a point of focus.

Tesla shows what Roadster drivers will see on screen before thruster activation

Tesla reveals Optimus Academy, where robots teach themselves


