Investor's Corner
Tesla’s (TSLA) Q2 2019 earnings call: Here are Wall Street’s estimates

Tesla (NASDAQ:TSLA) is poised to hold its second-quarter earnings call after the markets close on Wednesday. With the electric car maker exceeding expectations on its vehicle production and deliveries, all eyes are now on the company as it tries to return to profitability, which it was able to achieve in the third and fourth quarter of 2018.
Bill Selesky, an analyst with Argus Research, stated that the story of Tesla’s second-quarter immediately changed when it reported its production and delivery figures, which exceeded expectations. “We are still hearing that demand trends bode well for Tesla. What remains to be seen is whether Tesla will rein in its costs and expenses and improve its margins,” he said.
Garrett Nelson, an analyst with CFRA Research, noted that investors would likely be focused on whether the company will keep its initial forecast of selling 360,000-400,000 vehicles in 2019. “The ability of the stock to move higher will really depend on the (sales) guidance. We are still skeptical that they will hit that goal,” the CFRA analyst stated.
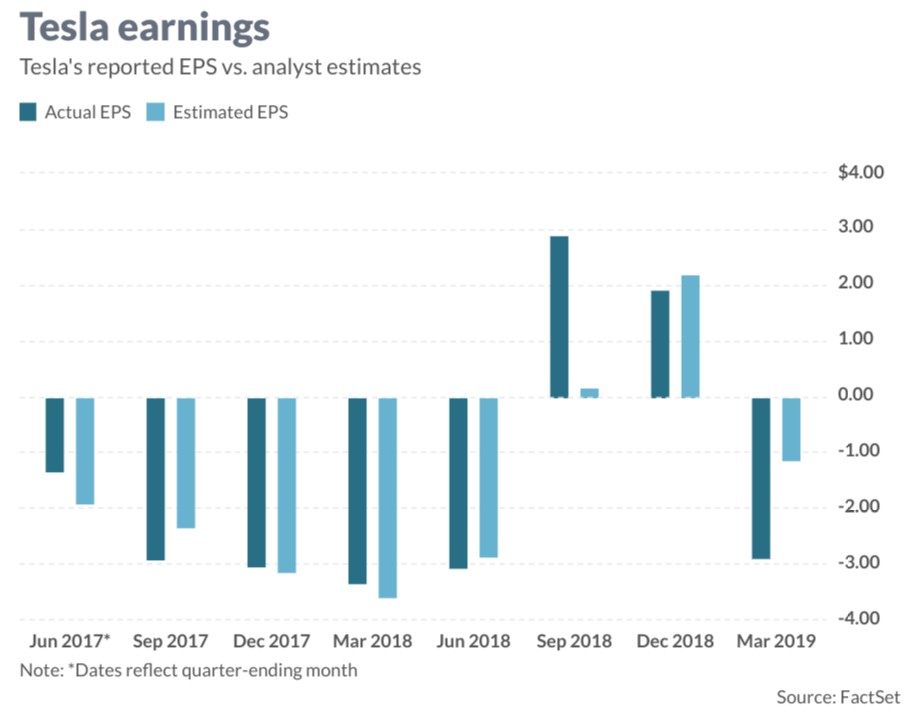
Overall, analysts polled by FactSet expect Tesla to report an adjusted quarterly loss of $0.39 per share, a notable improvement over the $3.06 loss the company reported in Q2 2018. Wall Street also expects Tesla to return to non-GAAP profitability by the fourth quarter.
Estimize, a crowdsourcing platform that aggregates estimates from Wall Street analysts, buy-side analysts, company executives, fund managers, academics and others, has noted that it expects Tesla to report an adjusted loss of $0.25 per share.
As for revenue, FactSet expects Tesla to report sales of $6.5 billion in the second quarter, an improvement over the $4 billion the company reported in Q2 2018 and the $4.5 billion in the first quarter. Estimize, for its part, expects Tesla to report sales of $6.6 billion.
Tesla has been on what appears to be a path towards recovery in July. TSLA shares have recovered 14% this month, following a 21% recovery in June. Due to the steep drop in the electric car maker’s shares following the first quarter, Tesla remains down 23% for 2019. This compares unfavorably with the S&P 500 index and the Dow Jones Industrial Average, which have gained 19% and 17%, respectively.
Selesky’s statement about the Tesla story changing with the results of the second-quarter vehicle production and delivery report mirrors the sentiments of some of the company’s supporters in Wall Street. In a recent note, for example, Baird analyst Ben Kallo stated that Tesla’s further execution, starting with its second-quarter earnings report, will “help restore credibility and create a challenging short environment” despite the “overly negative” narrative surrounding the company.
Even Barclays analyst Brian Johnson, a Tesla bear, has issued a note stating that he sees the electric car maker heading to a nearly profitable Q2 earnings report. “Increasing 2Q estimates as TSLA did indeed ‘move the metal,’” Johnson wrote.
As of writing, Tesla stock is trading +0.84% at $260.36 per share.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.


Investor's Corner
SpaceX’s biggest earnings test yet lands Tuesday, and Tesla shareholders should be watching
SpaceX reports earnings Tuesday as Wall Street watches AI spending, Starlink growth and Tesla merger

SpaceX reports third quarter results after the market closes Tuesday, with a webcast at 4:30 p.m. ET streamed on X, and Tesla follows a day later. Bloomberg consensus, cited by Pepperstone, calls for revenue of $12.89 billion, adjusted EBITDA of $6.62 billion and adjusted EPS near $0.15. That would be about 65% growth from the second quarter and SpaceX’s first profitable quarter since its IPO. Analysts expect roughly $6.4 billion from AI and $4.9 billion from Starlink, which is projected to reach 14.3 million consumer subscribers. Capital spending is forecast at $19.6 billion, leaving free cash flow near negative $11.6 billion.
The numbers matter because SpaceX has spent months trying to win over a skeptical market. It priced its record IPO at $135, spiked to $225.64, then sank near $105 in early August. Friday’s close of $146.03 sits about 28% below the June high. The Q2 report beat on revenue at $7.8 billion and put Starlink at 12 million subscribers, but $18.4 billion of capex hurt the stock. Since then SpaceX reached orbit on Starship Flight 14 with 26 Starlink V3 satellites, agreed to buy 800 MHz spectrum for about $8 billion as part of its Starlink Mobile push, and signed a fourth compute hosting deal in four months worth roughly $13 billion a year from December. Management is targeting more than 2 gigawatts of compute by year end and a $100 billion annualized revenue run rate. Evercore ISI, which raised its target to $275, said the quarter may be judged more on those targets than the reported figures
All of this sits under the Tesla merger question. Barclays analyst Dan Levy expects an all stock deal in which SpaceX buys Tesla at a premium, using reference values of $2.1 trillion and $1.5 trillion, and said an announcement would need to come by late October or early November to be voted on at Tesla’s December 6 annual meeting. Barclays estimates Musk would hold about 37% of the combined company and 56% of the votes. Musk said in July that combining companies cannot be discussed on an earnings call, but an investor question asking when SpaceX will merge with Tesla is sitting on SpaceX’s Q&A platform, and Teslarati has tracked how the Roadster demo revived the talk.
If a deal happens, Tuesday’s result would effectively set the price Tesla holders would receive. Their shares would convert into SpaceX stock, along with exposure to a company with a heavy investment on AI, while Tesla itself expects 2026 capex above $25 billion. A strong quarter and calmer spending would make that exchange easier to sell. Another round of heavy capex and a falling stock would make it harder.
Investor's Corner
Tesla’s flying Roadster just revealed something bigger than the car
Analysts say the Roadster demo puts a Tesla and SpaceX merger back on the table.
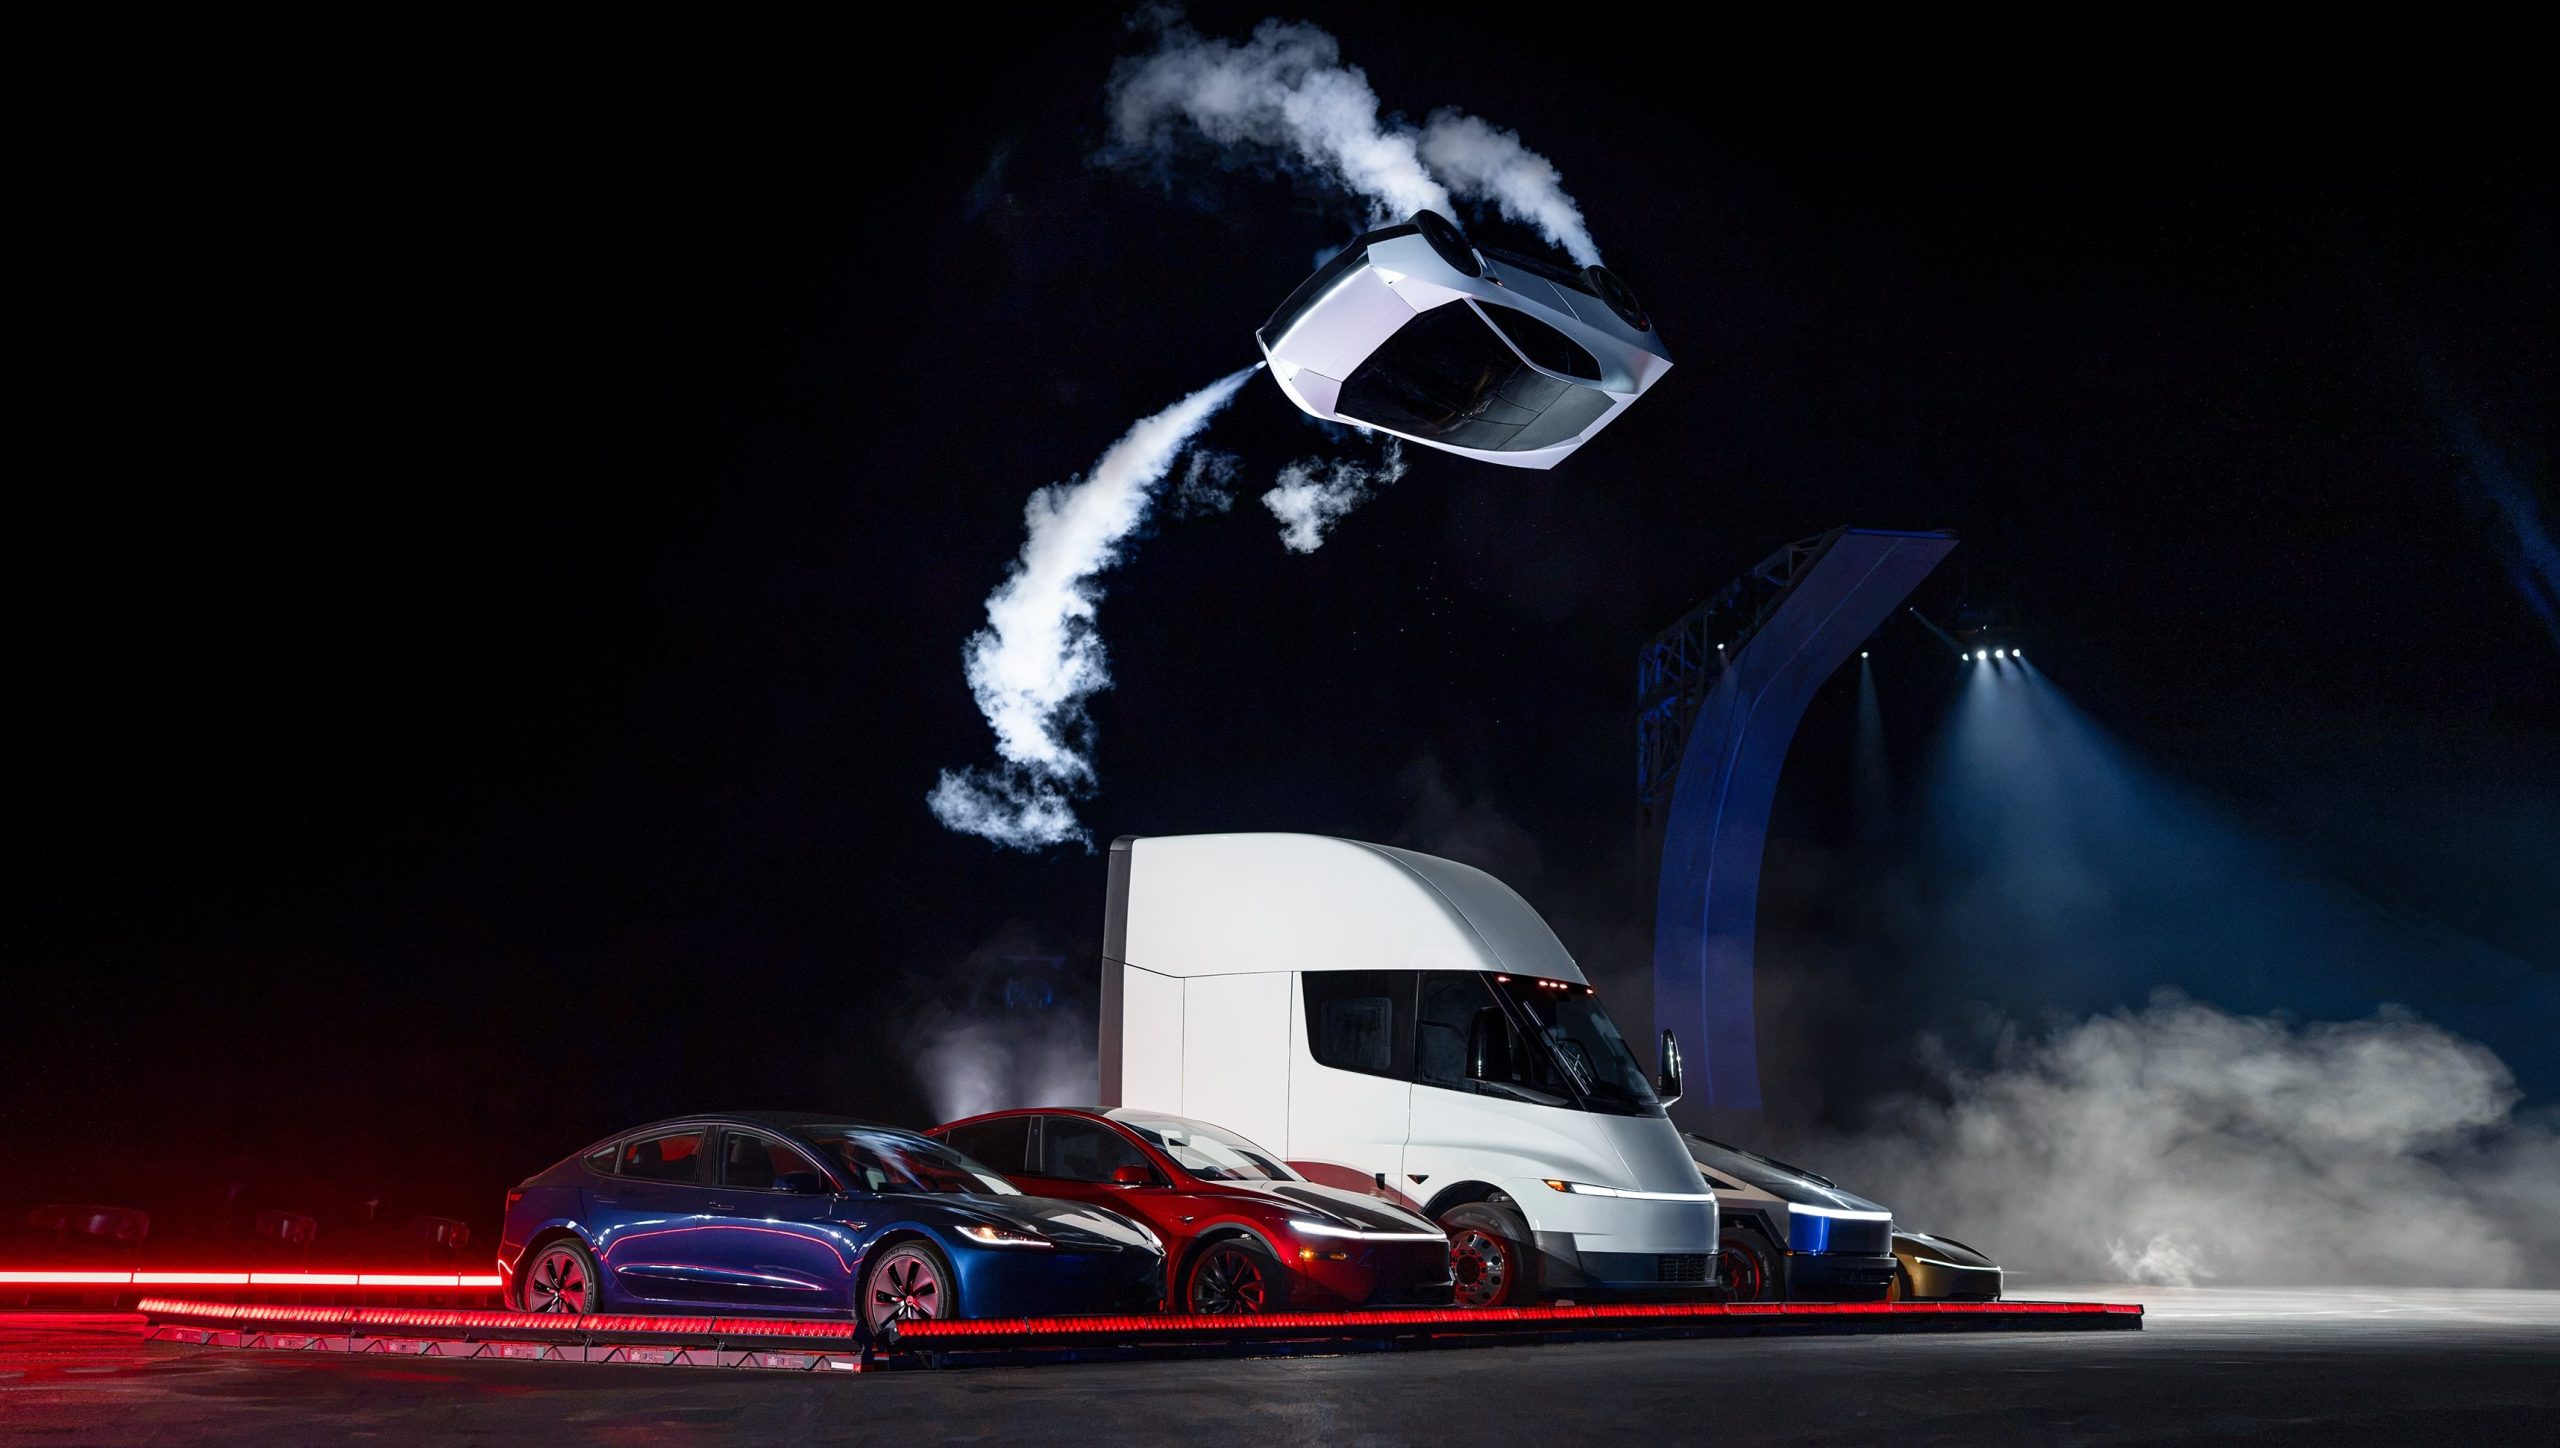
The Roadster unveiling near Waco ended Thursday night, and by Friday morning much of the investor reaction had less to do with the car than with who owns the rocket technology inside it.
Wedbush analyst Dan Ives said the event “puts the Tesla/SpaceX relationship on the table in a tangible way,” pointing to the propulsion, pressure vessel and control hardware sitting on a Tesla product. Gene Munster of Deepwater Asset Management called the demo “a ridiculous display of engineering” with “no commercial value” beyond embarrassing traditional automakers, though he said it showed Musk wants the two companies together.
The more specific forecast came a day earlier from Barclays. Analyst Dan Levy told clients a deal could be announced before Tesla’s annual meeting, which must happen by December 6, and that an announcement in late October or early November could make shareholder approval harder. Barclays expects SpaceX to be the buyer in an all stock deal, with Tesla holders receiving SpaceX shares at a premium, based on market values of roughly $2.1 trillion for SpaceX and $1.5 trillion for Tesla. If nothing lands around the meeting, the bank still sees an announcement within 6 to 12 months.
The Roadster demo just added more weight to merger speculations. Tesla’s demo used cold gas thrusters and pressure tanks of the kind SpaceX uses on Falcon 9, and Musk described the car as a collaboration between Tesla and SpaceX engineers, as we mentioned in our breakdown of the three Roadster configurations.
Musk has not publicly addressed a deal since the event, as far as we have seen. His most direct answer remains the one he gave at the All In Summit, when he said that with so much collaboration, “who can imagine what action one might take” without ruling anything out. Ives has held to a 2027 timeline since his March note, and Musk pushed back on the China piece of the speculation when ARK floated a year end announcement in August.
The next test is Tesla’s third quarter earnings call on October 21. However, we recall in July that Musk told analysts, “we can’t talk about combining companies and that kind of thing on an earnings call,” so a clear answer wouldn’t be expected.
Elon Musk
Elon Musk breaks his silence on the Starlink impact to Ukraine drones
Musk says the US military and president set Starshield limits, not SpaceX, amid Ukraine complaints.
Elon Musk says the speed limit cutting out Ukraine’s military Starlink terminals is not SpaceX’s decision. In a post on X Wednesday, Musk wrote that “Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.” He added that Starlink is a commercial service limited to civilian or defensive activities and “cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.”
He was replying to Mykhailo Fedorov, Ukraine’s former defense minister, who had thanked Musk for restoring connectivity at speeds up to 160 km/h and said removing the Starshield limit entirely is “now critical for Ukraine’s defense.”
Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.
Starlink is a commercial service owned and controlled by SpaceX. Usage of Starlink is limited to civilian or defensive activities and cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.
— Elon Musk (@elonmusk) October 14, 2026
The complaint started Tuesday night, when Ukrainian officials said military terminals began losing service above roughly 100 mph. Presidential adviser Serhiy Beskrestnov said the defense forces got no warning and several missions were disrupted, as Teslarati reported earlier Wednesday. The 7th Rapid Reaction Corps told Reuters connections dropped for 10 to 20 seconds at speeds well below the limit, which made drones harder to control. Poland’s foreign minister, Radoslaw Sikorski, asked Musk on X whether he is “playing politics with your products again.”
That is why the Starlink and Starshield distinction matters. SpaceX introduced Starshield in 2022 as the government version of Starlink, with an initial focus on Earth observation, communications and hosted payloads. It won a Space Force contract in 2023 with a $70 million ceiling. In December 2024, the Pentagon moved Ukraine’s terminals onto Starshield, covering about 3,000 units across two contracts. Ukraine’s military connections therefore run through a service that Musk now says sits under Washington’s control.
While Musk’s post describes who holds authority, it does not infer that anyone ordered the limit, and neither SpaceX nor the US government has confirmed who set it. Ukrainian officials have pointed to the timing, which follows President Trump’s push for an energy ceasefire and Musk’s Saturday post that “Zelensky has gone too far.” The BBC noted Trump denied threatening to restrict intelligence sharing with Kyiv, and no evidence has been presented that Washington requested the cap.
The episode also revives a promise from 2025. After Poland accused him of threatening Ukraine’s access, Musk said Starlink “will never turn off its terminals” and would not be used as a bargaining chip. Poland has since supplied more than 29,000 terminals to Ukraine. Teslarati also covered Kyiv’s search for Starlink alternatives in 2025, and the latest dispute gives that search new urgency.

SpaceX’s biggest earnings test yet lands Tuesday, and Tesla shareholders should be watching

SpaceX’s Gwynne Shotwell just made a quiet gesture toward Tesla

Tesla Roadster owners to get “Flying Stunt Mode” and looping track access

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


