Investor's Corner
Tesla skeptic changes tune on Model 3 battery costs: ‘TSLA remains ahead of the pack’

Longtime Tesla skeptic UBS appears to be taking a rather bullish outlook on the electric car maker. In a recent note, UBS analyst Colin Langan raised his price target for Tesla stock (NASDAQ:TSLA) from a conservative $190 to a more optimistic $230, citing the Model 3’s battery cost advantages over competitors currently available in the market.
The UBS analysts, together with a group of engineers, analyzed batteries from Panasonic/Tesla, LG Chem, Samsung SDI, and Contemporary Amperex Technology (CATL). According to the team’s analysis, the Model 3’s batteries, which are produced at the Gigafactory 1 in NV, are around 20% more cost efficient than LG Chem’s batteries, which are the second-best in the list. The UBS analysts estimated that Tesla’s batteries currently cost $111 per kWh, which is around $37 per kWh cheaper than LG Chem’s batteries, its closest competitor.
In what could only be described as an admission of miscalculations in the past, UBS analyst Colin Langan, who has consistently given TSLA a “Sell” rating, noted that the firm now believes that competitors from established automakers would likely be less profitable than the electric car maker in the EV market.
“Contrary to our team’s previous view, they now believe incumbent OEMs will be less profitable than Tesla in EV space. Tesla’s cost advantage can be defended (at least temporarily) because other OEMs will not switch to cheaper NCA chemistry. We continue to believe that TSLA remains ahead of the pack when it comes to EV tech,” the analyst noted.
Based on Tesla’s lower cost battery and considering non-zero emission electric vehicle credits, the UBS analyst also boosted his fiscal 2019 earnings per share estimate for the electric car maker by $5.85 to $3.55, as noted by The Fly. Keeping his longtime stance on the company, though, Langan nevertheless maintained a “Sell” rating on Tesla, with a price target of $230.
While the financial firm remains notably skeptical about Tesla as evidenced by Langan’s consistent “Sell” rating, UBS’ admission of the Model 3’s battery cost advantages could very well signify a shift in Wall Street’s general perception of the electric car maker. Together with a vote of confidence from Zacks Investment Research in the form of a “Strong Buy” rating after Tesla’s release of its third quarter earnings, Tesla’s capability to maintain profitability in the coming quarters is beginning to appear incredibly feasible.
Elon Musk noted during the third quarter earnings call that Tesla would have a positive net income and cash flow in the present quarter, and in all quarters moving forward. Musk even remarked that even in times when Tesla has to conduct repayments, the company should display a flat cash flow.
“We expect to again have positive net income and cash flow in Q4. And I believe our aspiration is something that will be for all quarters going forward. I think we can actually be positive cash flow and profitable for all quarters going forward, leaving aside the quarters where we may need to do a significant repayment but — for example, in Q1 next year. But I think even in Q1, I think we can be approximately flat in cash flow by end of quarter,” Musk said.
Behind these predictions lies Tesla’s battery technology, which continues to get better over time. As noted by President of Automotive Jerome Guillen, Tesla’s batteries are always in a state of improvement. Thus, while UBS’ analysis has concluded that the Model 3’s batteries are the best in the market, Tesla’s batteries in the coming months would likely show an even wider gap over its competitors.
“We are improving the design of the cell. The design of the cell is not frozen. It evolves, and we have a nice roadmap of technology improvements for the coming years,” Guillen said.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.



Elon Musk said he is planning to give “every one of his SpaceX shares to every kid in America” in 2027, stating that “this will be the first of many.”
SpaceX went public earlier this year, and its stock price has been relatively stable since leveling off shortly after its IPO. Based on its current price, it’s a gift of just over $10 billion to children across the United States.
It appears to be closely related to President Donald Trump’s bank accounts for children, which were set up earlier this year as Trump Accounts.
Just hours earlier, Anthropic had announced the establishment of its Anthropic Public Benefit Fund, “a new wholly-owned entity dedicated entirely to public benefit.” Musk responded by stating he recommended “giving the shares directly to the public,” and that he would be doing it that way.
Just a little bit later, Musk said children across the U.S. would be getting a share from him:
Next year, I will give one of my SpaceX shares to every kid in America.
This will be the first of many.
— Elon Musk (@elonmusk) October 19, 2026
There are roughly 70 million children, meaning someone under the age of 18, in the United States, according to the Federal Interagency Forum on Child and Family Statistics. Musk’s ownership of SpaceX stock shows he has around 849 million Class A shares of SpaceX stock, according to filings with the SEC.
Investor's Corner
SpaceX’s biggest earnings test yet lands Tuesday, and Tesla shareholders should be watching
SpaceX reports earnings Tuesday as Wall Street watches AI spending, Starlink growth and Tesla merger

SpaceX reports third quarter results after the market closes Tuesday, with a webcast at 4:30 p.m. ET streamed on X, and Tesla follows a day later. Bloomberg consensus, cited by Pepperstone, calls for revenue of $12.89 billion, adjusted EBITDA of $6.62 billion and adjusted EPS near $0.15. That would be about 65% growth from the second quarter and SpaceX’s first profitable quarter since its IPO. Analysts expect roughly $6.4 billion from AI and $4.9 billion from Starlink, which is projected to reach 14.3 million consumer subscribers. Capital spending is forecast at $19.6 billion, leaving free cash flow near negative $11.6 billion.
The numbers matter because SpaceX has spent months trying to win over a skeptical market. It priced its record IPO at $135, spiked to $225.64, then sank near $105 in early August. Friday’s close of $146.03 sits about 28% below the June high. The Q2 report beat on revenue at $7.8 billion and put Starlink at 12 million subscribers, but $18.4 billion of capex hurt the stock. Since then SpaceX reached orbit on Starship Flight 14 with 26 Starlink V3 satellites, agreed to buy 800 MHz spectrum for about $8 billion as part of its Starlink Mobile push, and signed a fourth compute hosting deal in four months worth roughly $13 billion a year from December. Management is targeting more than 2 gigawatts of compute by year end and a $100 billion annualized revenue run rate. Evercore ISI, which raised its target to $275, said the quarter may be judged more on those targets than the reported figures
All of this sits under the Tesla merger question. Barclays analyst Dan Levy expects an all stock deal in which SpaceX buys Tesla at a premium, using reference values of $2.1 trillion and $1.5 trillion, and said an announcement would need to come by late October or early November to be voted on at Tesla’s December 6 annual meeting. Barclays estimates Musk would hold about 37% of the combined company and 56% of the votes. Musk said in July that combining companies cannot be discussed on an earnings call, but an investor question asking when SpaceX will merge with Tesla is sitting on SpaceX’s Q&A platform, and Teslarati has tracked how the Roadster demo revived the talk.
If a deal happens, Tuesday’s result would effectively set the price Tesla holders would receive. Their shares would convert into SpaceX stock, along with exposure to a company with a heavy investment on AI, while Tesla itself expects 2026 capex above $25 billion. A strong quarter and calmer spending would make that exchange easier to sell. Another round of heavy capex and a falling stock would make it harder.
Investor's Corner
Tesla’s flying Roadster just revealed something bigger than the car
Analysts say the Roadster demo puts a Tesla and SpaceX merger back on the table.
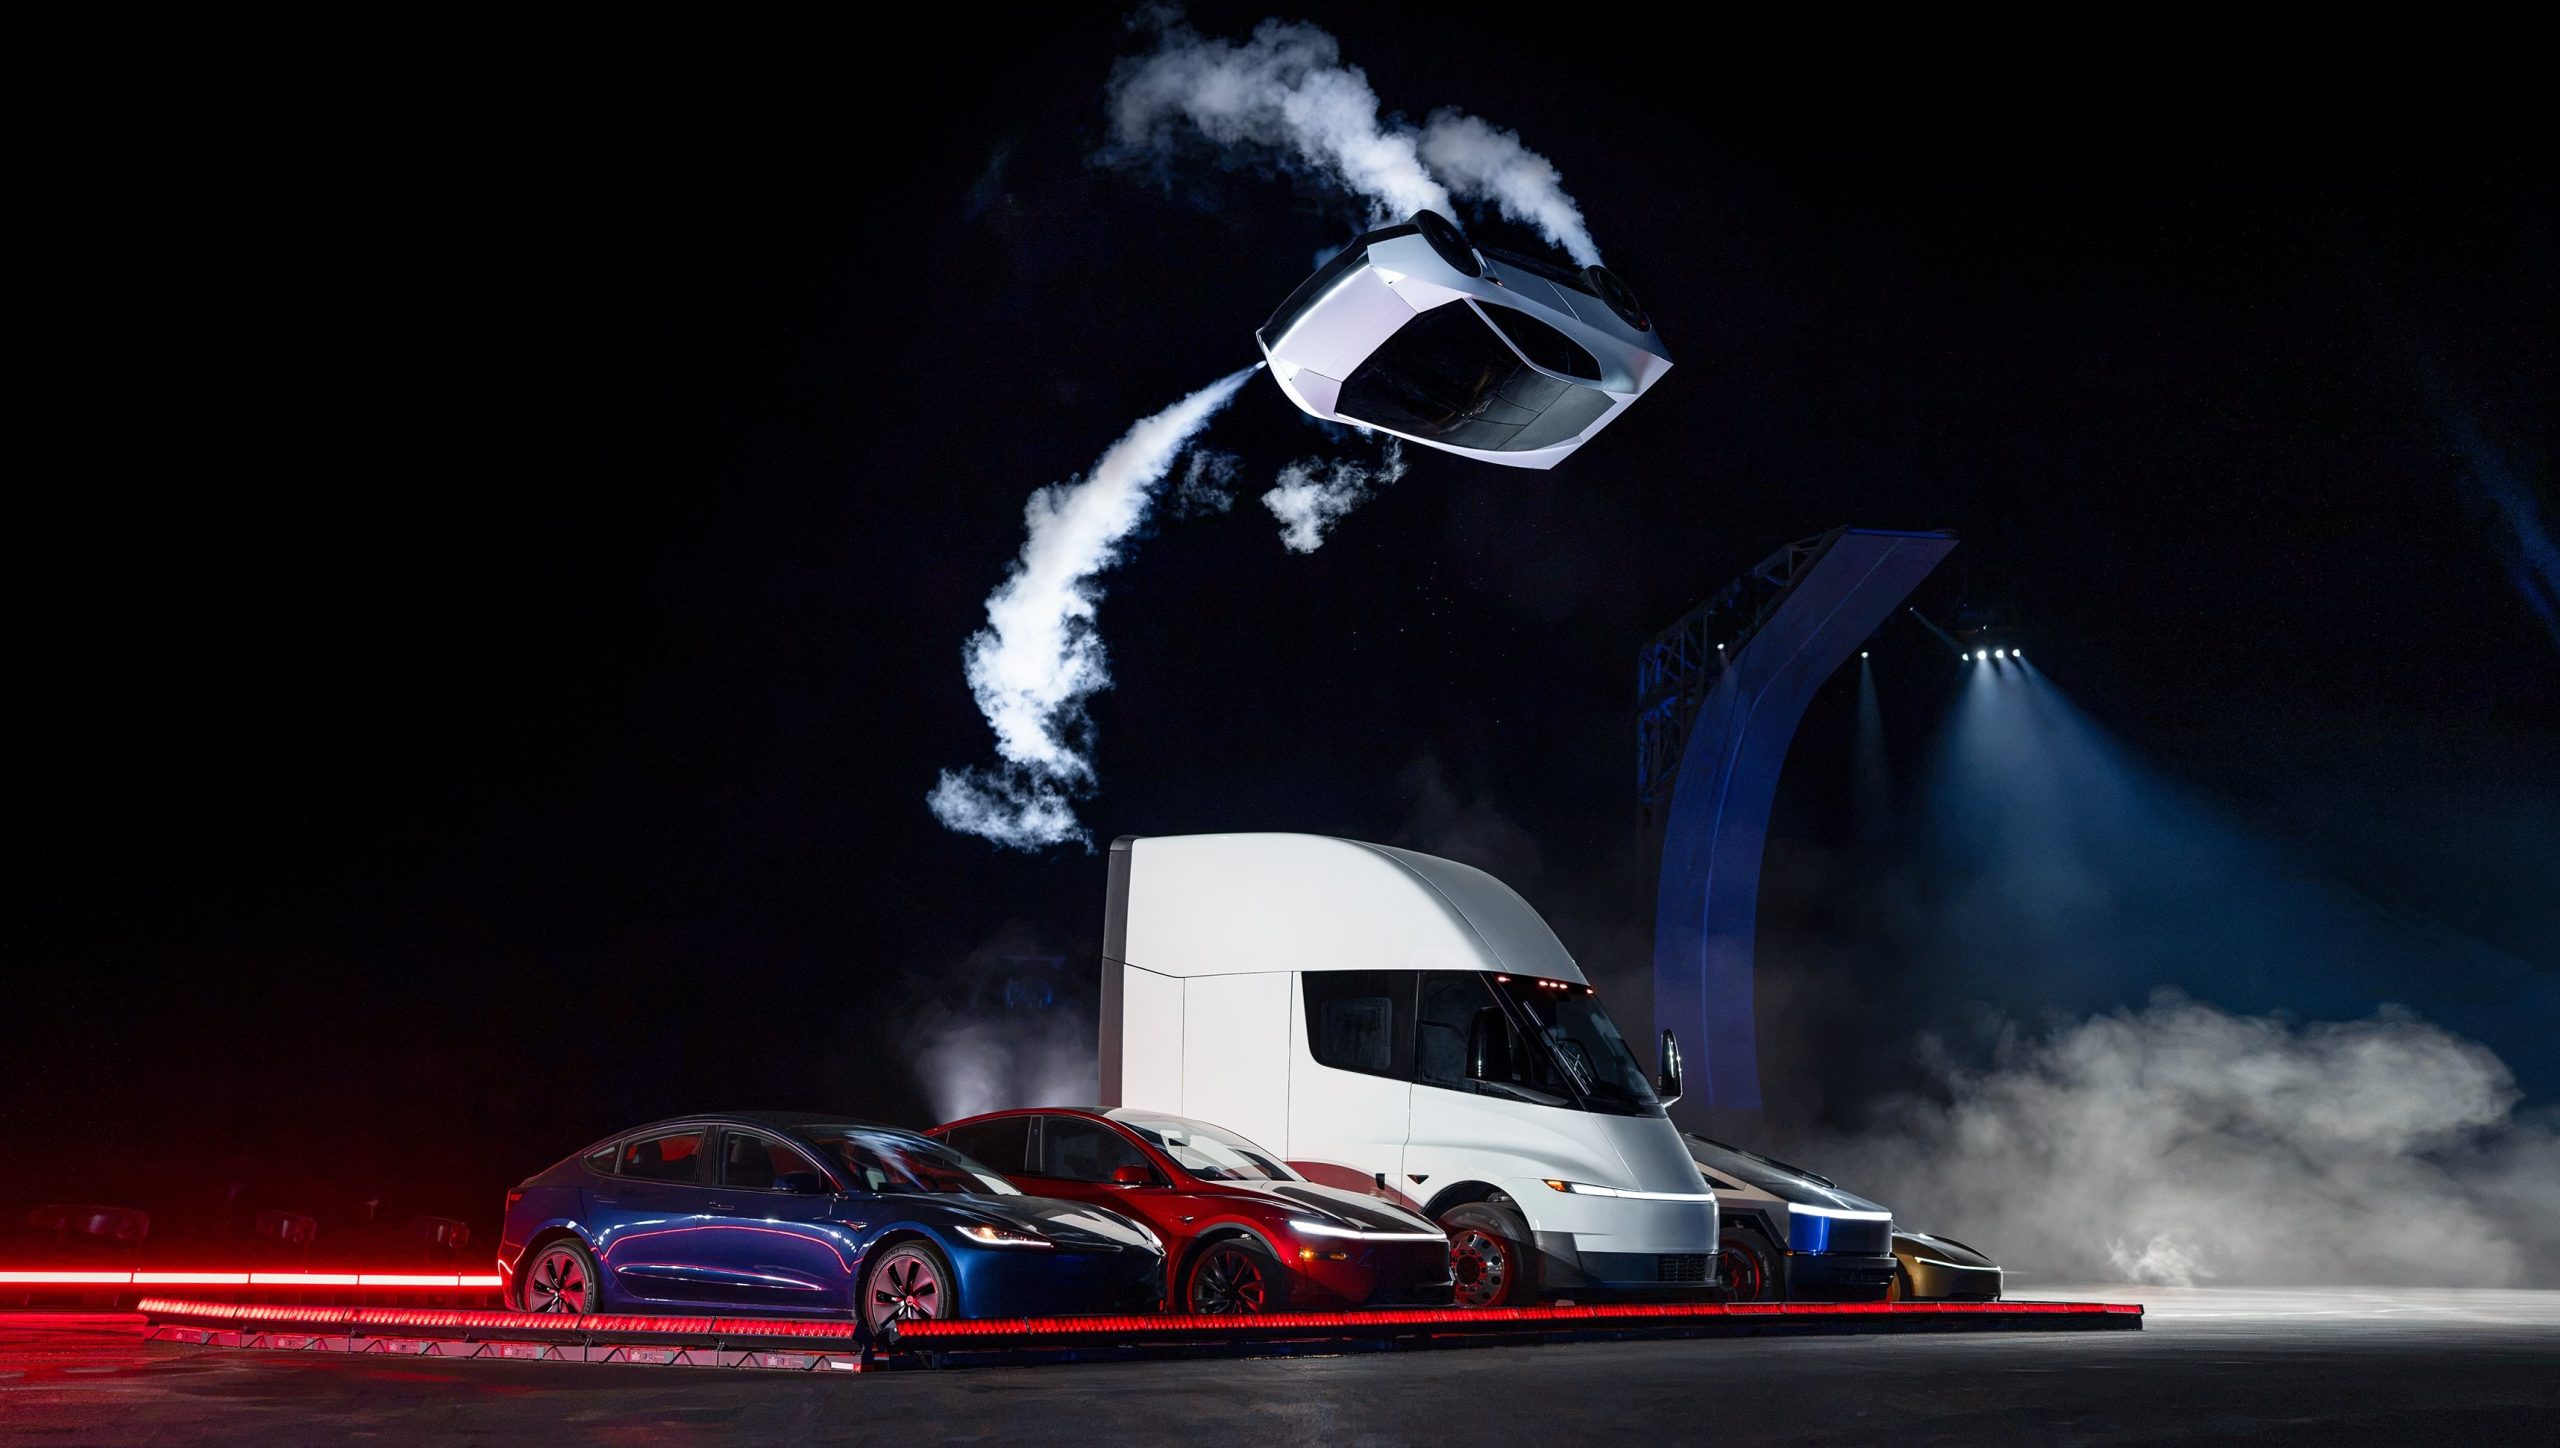
The Roadster unveiling near Waco ended Thursday night, and by Friday morning much of the investor reaction had less to do with the car than with who owns the rocket technology inside it.
Wedbush analyst Dan Ives said the event “puts the Tesla/SpaceX relationship on the table in a tangible way,” pointing to the propulsion, pressure vessel and control hardware sitting on a Tesla product. Gene Munster of Deepwater Asset Management called the demo “a ridiculous display of engineering” with “no commercial value” beyond embarrassing traditional automakers, though he said it showed Musk wants the two companies together.
The more specific forecast came a day earlier from Barclays. Analyst Dan Levy told clients a deal could be announced before Tesla’s annual meeting, which must happen by December 6, and that an announcement in late October or early November could make shareholder approval harder. Barclays expects SpaceX to be the buyer in an all stock deal, with Tesla holders receiving SpaceX shares at a premium, based on market values of roughly $2.1 trillion for SpaceX and $1.5 trillion for Tesla. If nothing lands around the meeting, the bank still sees an announcement within 6 to 12 months.
The Roadster demo just added more weight to merger speculations. Tesla’s demo used cold gas thrusters and pressure tanks of the kind SpaceX uses on Falcon 9, and Musk described the car as a collaboration between Tesla and SpaceX engineers, as we mentioned in our breakdown of the three Roadster configurations.
Musk has not publicly addressed a deal since the event, as far as we have seen. His most direct answer remains the one he gave at the All In Summit, when he said that with so much collaboration, “who can imagine what action one might take” without ruling anything out. Ives has held to a 2027 timeline since his March note, and Musk pushed back on the China piece of the speculation when ARK floated a year end announcement in August.
The next test is Tesla’s third quarter earnings call on October 21. However, we recall in July that Musk told analysts, “we can’t talk about combining companies and that kind of thing on an earnings call,” so a clear answer wouldn’t be expected.

Elon Musk will give ‘every kid in America’ a SpaceX share in 2027

Elon Musk reveals why Boring Co’s biggest East Coast project never happened

Tesla CEO Elon Musk reminds everyone about Roadster’s true meaning

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions
Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


