Investor's Corner
Wall St. can’t make up its mind about Tesla: TSLA ups and downs this quarter

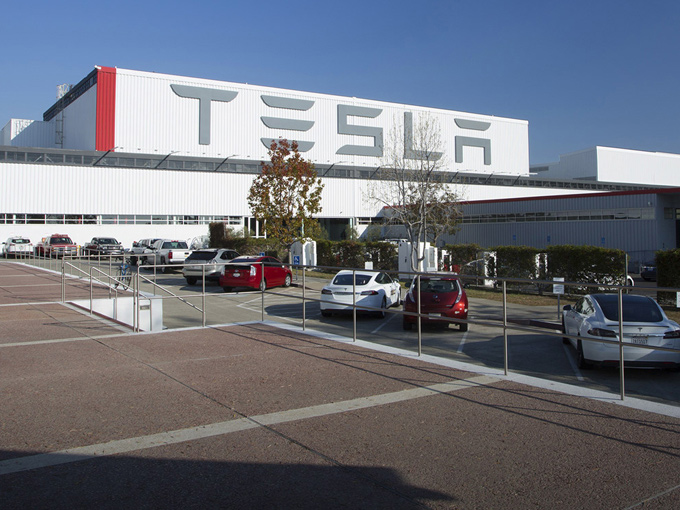
Tesla’s portfolio of products and services extends well beyond transportation to energy storage systems and includes solar and energy storage products. As the world’s only vertically integrated energy company, Tesla is truly unique among alternative energy stock offerings. With end-to-end clean energy products — including generation, storage, and consumption — as well as an established a global network of vehicle stores, service centers, and Supercharger stations, Tesla is well situated to accelerate the widespread adoption of its line.
Many people admire Tesla, Inc. for its visionary approach to a sustainable future. Indeed, the company’s most recent SEC 10-K filing spoke to the company’s mission to provide an “intense focus to accelerate the world’s transition to sustainable transport, ” a business model that differentiates Tesla from other manufacturers.
That report also pointed to possible market uncertainties which could affect the 2017 performance of the Tesla brand.
“We have experienced in the past, and may experience in the future, significant delays or other complications in the design, manufacture, launch and production ramp of new vehicles and other products such as our energy storage products and the solar roof, which could harm our brand, business, prospects, financial condition and operating results.”
As Q1 2017 nears its conclusion, this is a good stopping point to begin to review the ups and downs of the Tesla brand and how stock market analysts have assessed and questioned the resiliency and robust character of the stock.
A global look at TSLA
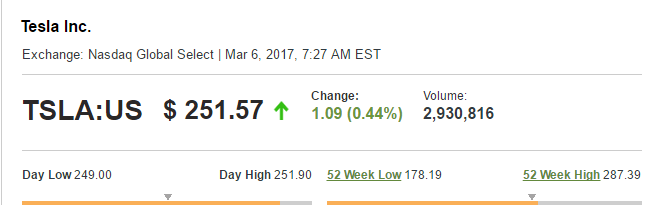
- Tesla, Inc. (NASDAQ:TSLA) opened at $246.23 on Friday, March 3, 2017. Today, March 6, 2017, that number rose to $251.57 to start the day.
- Tesla‘s stock had its “hold” rating reiterated by Deutsche Bank AG in a report released on Friday, March 3, 2017. Deutsche Bank AG had a $215.00 target price on the Tesla stock.
- Eight investment analysts have recently rated the stock with a sell rating, eleven have assigned a hold rating, and twelve have given a buy rating to the company. The stock presently has an average rating of “Hold” and an average price target of $256.33.
- Goldman Sachs Group, Inc. downgraded the Tesla stock from Neutral to a Sell rating after the company’s December quarter results. Like several other brokerages, the firm cited about cash requirements and worries on operational execution.
- Tesla has a 12 month low of $178.19 and a 12 month high of $287.39.
- The firm has a 50-day moving average price of $254.33 and a 200 day moving average price of $215.51.
- The company’s market cap is $38.17 billion.
Why analysts fail to come to consensus on Tesla stock valuation
As the first car company in a very long time to be homegrown and a real challenge to Detroit’s Big 3 automakers, Tesla experiences numerous influences on its stock value, from supply chain difficulties, to currency fluctuations, competition, and even factors like emotion and superstition. These factors can push the Tesla stock high and low, even within a short period of time. A closely watched stock like Tesla is often accused variously of being overvalued, misunderstood, or overextended.
Yet the demand for Tesla’s Model S and X, as well as initial orders for its more cost effective Model 3 sedan, have continued to support Tesla’s fiscal premises that U.S. and global citizens really want to own cleaner vehicles.
Tesla issued its 2016 Q4 earnings results on Wednesday, February 22, 2017 and reported $0.69 earnings per share for the quarter, missing the Zacks’ consensus estimate of $0.43 by $0.26. As 2017 began, Tesla stocks had accrued a number of positive analyst reports and had continued to rise since the 2016 presidential election. The firm earned $2.29 billion during the quarter, compared to analyst estimates of $2.21 billion. During the same period in the prior year, the firm earned $0.87 earnings per share.
Analysts’ estimates of Tesla stock prior to the 2016 annual report
It’s interesting to look back over the past several months and see how variable and uncertain many analysts have been about Tesla. In a cultural climate in which the largest economic downturn since the Great Depression looms large in many people’s consciousnesses, it may be reasonable for many people to be skeptical about Tesla’s value. But, as with any revolutionary change in social thinking, Tesla will likely continue to experience its share of scrutiny as well as celebration as it contributes to a sustainable future.
- Deutsche Bank AG’s price target suggests a potential downside of 12.68% from the company’s current price as of March 3, 2017.
- TheStreet raised Tesla Motors from a “d+” rating to a “c-” rating in a research note on Wednesday, January 25th.
- Robert W. Baird reaffirmed an “outperform” rating and issued a $338.00 price target on shares of Tesla Motors in a research note on Thursday, January 5th.
- Global Equities Research reaffirmed an “overweight” rating and issued a $385.00 price target on shares of Tesla Motors in a research note on Tuesday, December 6th.
- Cowen and Company reaffirmed an “underperform” rating and issued a $155.00 price target (down from $160.00) on shares of Tesla Motors in a research note on Sunday, December 4th.
- Vetr raised Tesla Motors from a “buy” rating to a “strong-buy” rating and set a $203.80 price target on the stock in a research note on Tuesday, November 15th.



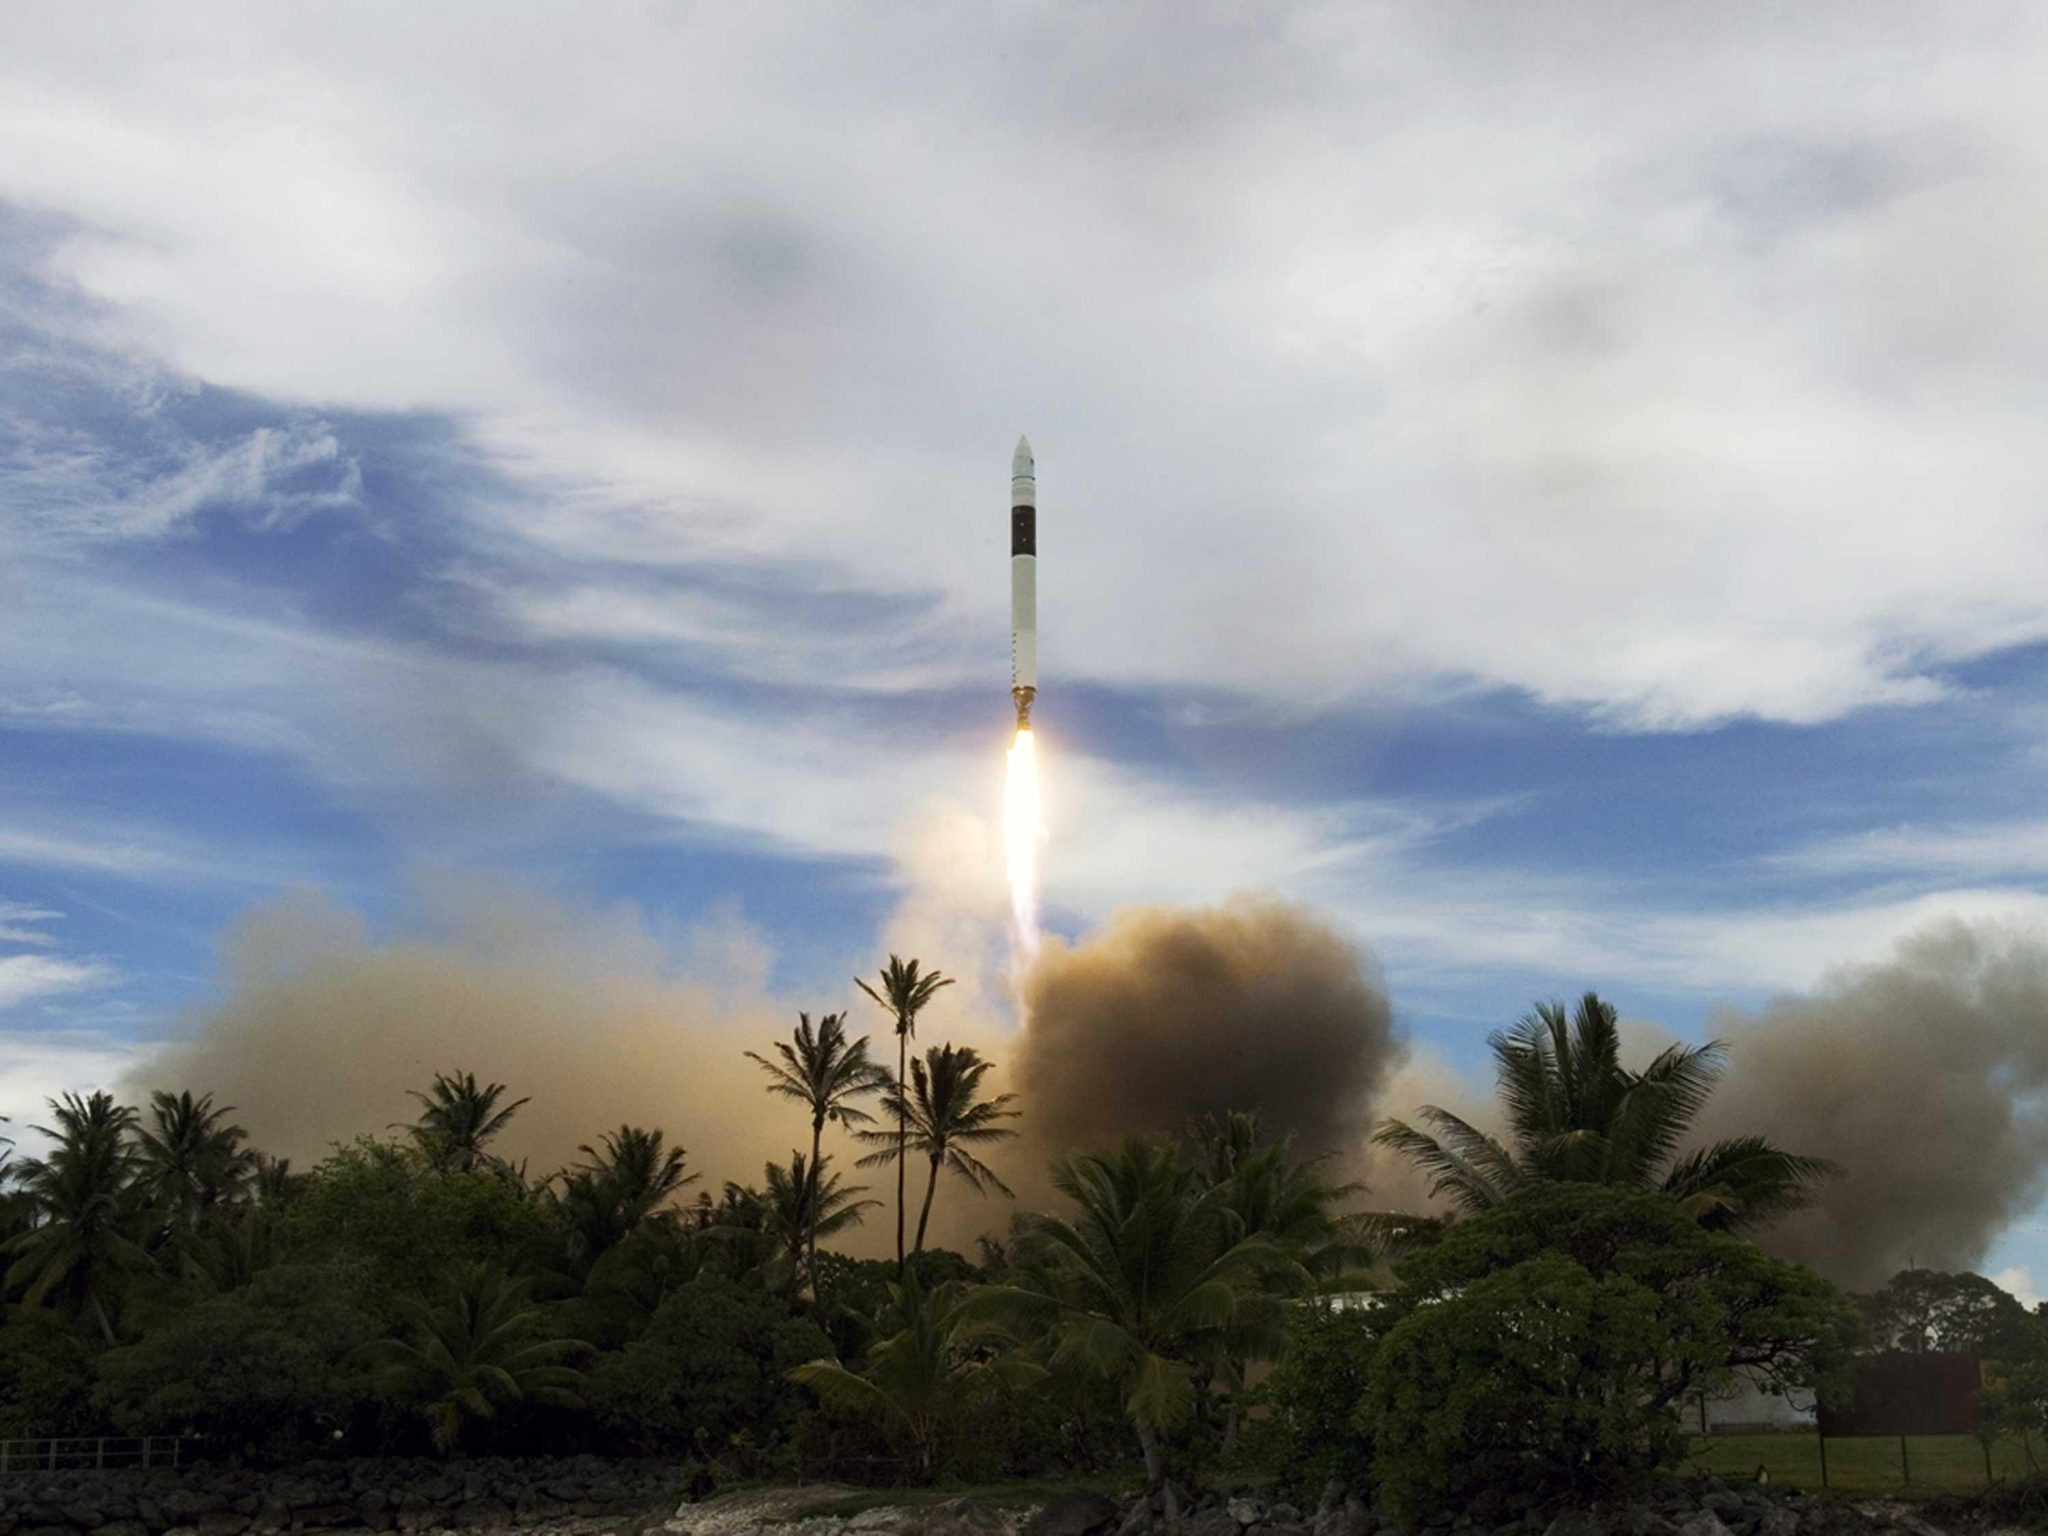
SpaceX (NASDAQ: SPCX) will report its second public earnings call today since its IPO earlier this year, and there are a few things we expect to hear about, as well as Wall Street analysts, who have already outlined their expectations for the call.
Wall Street analysts have a consensus of $12.72 billion in revenue and an earnings per share (EPS) of $0.13. These are broken down into three sectors: Space, Connectivity, and AI/SI, which are perceived in this way:
- Space: $1.41 billion
- Connectivity: $4.84 billion
- AI/SI: $6.47 billion
Other outlets cluster near $12.8 or $12.9 billion in revenue and $0.14 – $0.15 EPS. This implies a roughly 65 percent sequential growth from Q2’s $7.81 billion, driven mostly by AI/SI, with the first post-IPO positive EPS expected.
Here are the three things to watch for on the call:
AI Revenue Ramp and the $100B+ ARR target
AI is truly the swing factor for SpaceX, and analysts expect it to roughly double from Q2’s $2.56 billion and become about half of total revenue. Management previously guided to a $100 billion+ annualized run rate by December, including the Cursor acquisition, which was $60 billion, to close the quarter.
Listen for updates on SpaceX’s compute capacity, especially pertaining to its contracts with Google, Anthropic, and others, revenue per watt, any new deals, and Cursor’s early contribution.
Starlink/Connectivity Metrics and Mobile Expansion
Connectivity remains a main profit engine for SpaceX. Subscriber additions will be something to pay attention to, as Q2 ended at 12 million and previews are looking at 14 million for this quarter. Additionally, ARPU trends, enterprise and government growth, and any commentary on Starlink Mobile will be something to pay attention to, especially following the recent low-band spectrum deal and FCC-related constellation approvals.
Capex Trajectory, Cash Burn/FCF, and Starship/Operational Updates
Q2 capex of roughly $18.4 billion weighed on the stock. Investors will look to scrutinize Q3 spending levels, any guidance on the pace into Q4/2027, free cash flow, backlog, and liquidity. Operational color on Starship (Flight 14 milestones and Flight 15 timing/reusability progress), Falcon cadence, and government/NASA contracts are also in focus.
Of course, there will also be some speculation on the potential Tesla-SpaceX merger, but there was nothing mentioned in the company’s proxy it sent earlier this week.
SpaceX will report earnings after market close today and will stream the call on X.
Watch live as SpaceX discusses our Q3 2026 earnings at 3:30pm CT today → https://t.co/Qrb0qeVG15
— SpaceX (@SpaceX) October 20, 2026
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here
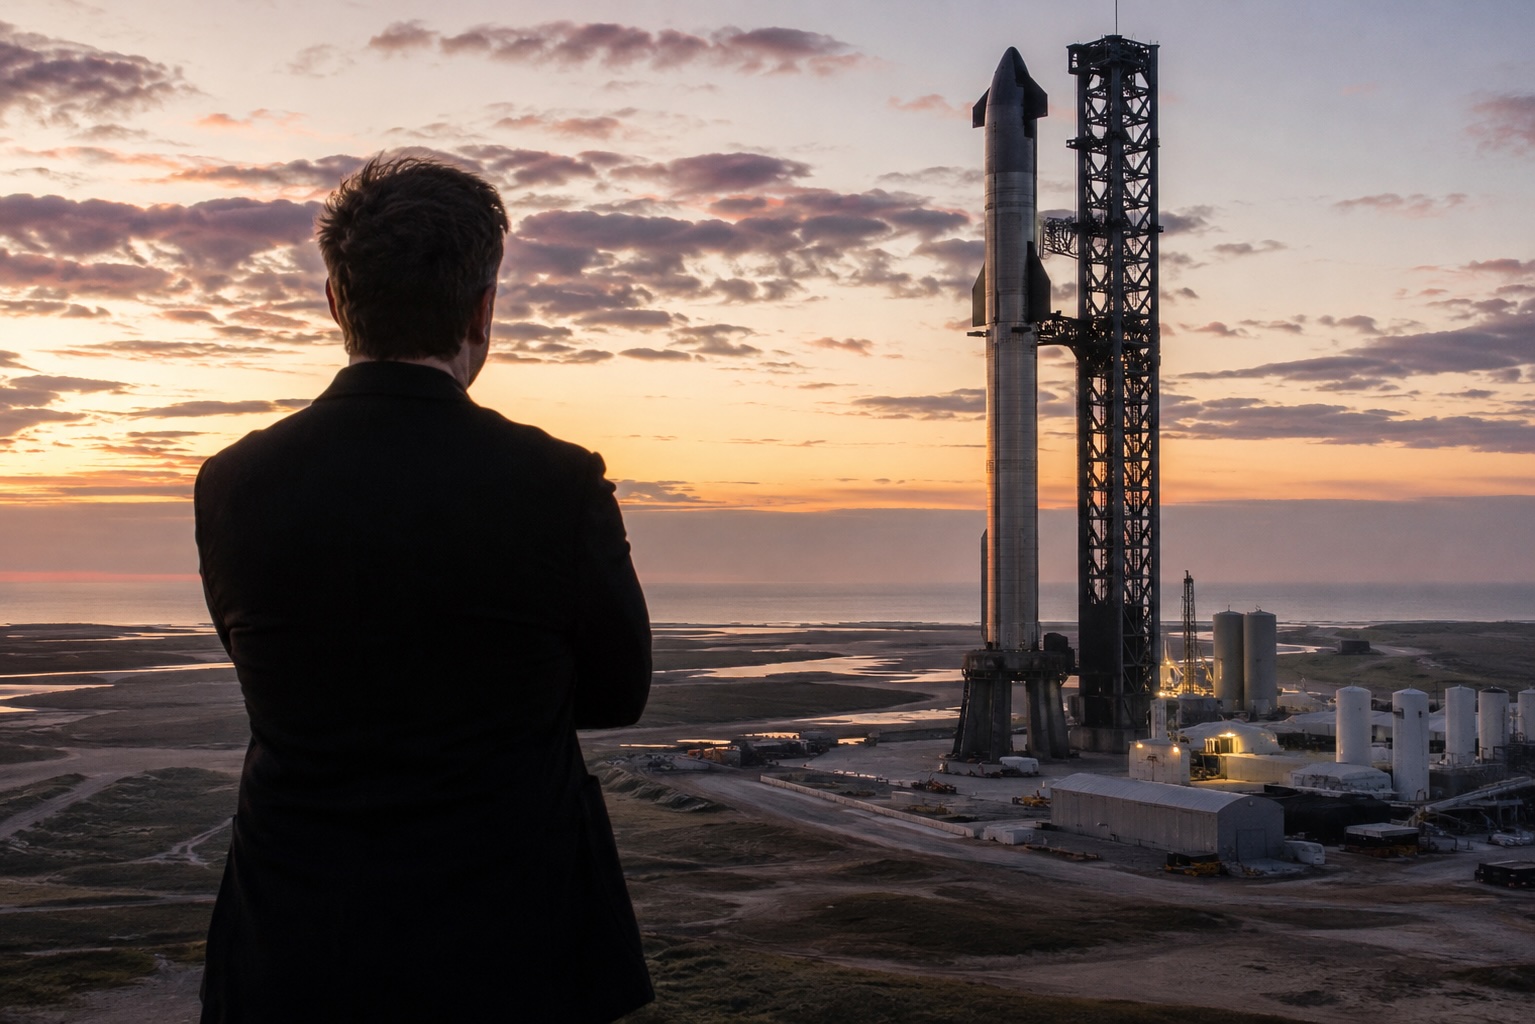
Elon Musk said he is planning to give “every one of his SpaceX shares to every kid in America” in 2027, stating that “this will be the first of many.”
SpaceX went public earlier this year, and its stock price has been relatively stable since leveling off shortly after its IPO. Based on its current price, it’s a gift of just over $10 billion to children across the United States.
It appears to be closely related to President Donald Trump’s bank accounts for children, which were set up earlier this year as Trump Accounts.
Just hours earlier, Anthropic had announced the establishment of its Anthropic Public Benefit Fund, “a new wholly-owned entity dedicated entirely to public benefit.” Musk responded by stating he recommended “giving the shares directly to the public,” and that he would be doing it that way.
Just a little bit later, Musk said children across the U.S. would be getting a share from him:
Next year, I will give one of my SpaceX shares to every kid in America.
This will be the first of many.
— Elon Musk (@elonmusk) October 19, 2026
There are roughly 70 million children, meaning someone under the age of 18, in the United States, according to the Federal Interagency Forum on Child and Family Statistics. Musk’s ownership of SpaceX stock shows he has around 849 million Class A shares of SpaceX stock, according to filings with the SEC.
Investor's Corner
SpaceX’s biggest earnings test yet lands Tuesday, and Tesla shareholders should be watching
SpaceX reports earnings Tuesday as Wall Street watches AI spending, Starlink growth and Tesla merger

SpaceX reports third quarter results after the market closes Tuesday, with a webcast at 4:30 p.m. ET streamed on X, and Tesla follows a day later. Bloomberg consensus, cited by Pepperstone, calls for revenue of $12.89 billion, adjusted EBITDA of $6.62 billion and adjusted EPS near $0.15. That would be about 65% growth from the second quarter and SpaceX’s first profitable quarter since its IPO. Analysts expect roughly $6.4 billion from AI and $4.9 billion from Starlink, which is projected to reach 14.3 million consumer subscribers. Capital spending is forecast at $19.6 billion, leaving free cash flow near negative $11.6 billion.
The numbers matter because SpaceX has spent months trying to win over a skeptical market. It priced its record IPO at $135, spiked to $225.64, then sank near $105 in early August. Friday’s close of $146.03 sits about 28% below the June high. The Q2 report beat on revenue at $7.8 billion and put Starlink at 12 million subscribers, but $18.4 billion of capex hurt the stock. Since then SpaceX reached orbit on Starship Flight 14 with 26 Starlink V3 satellites, agreed to buy 800 MHz spectrum for about $8 billion as part of its Starlink Mobile push, and signed a fourth compute hosting deal in four months worth roughly $13 billion a year from December. Management is targeting more than 2 gigawatts of compute by year end and a $100 billion annualized revenue run rate. Evercore ISI, which raised its target to $275, said the quarter may be judged more on those targets than the reported figures
All of this sits under the Tesla merger question. Barclays analyst Dan Levy expects an all stock deal in which SpaceX buys Tesla at a premium, using reference values of $2.1 trillion and $1.5 trillion, and said an announcement would need to come by late October or early November to be voted on at Tesla’s December 6 annual meeting. Barclays estimates Musk would hold about 37% of the combined company and 56% of the votes. Musk said in July that combining companies cannot be discussed on an earnings call, but an investor question asking when SpaceX will merge with Tesla is sitting on SpaceX’s Q&A platform, and Teslarati has tracked how the Roadster demo revived the talk.
If a deal happens, Tuesday’s result would effectively set the price Tesla holders would receive. Their shares would convert into SpaceX stock, along with exposure to a company with a heavy investment on AI, while Tesla itself expects 2026 capex above $25 billion. A strong quarter and calmer spending would make that exchange easier to sell. Another round of heavy capex and a falling stock would make it harder.

SpaceX reports its second earnings today: here’s what to expect

SpaceX just launched its secret Starfall saucer again

The Boring Company’s latest Tesla tunnel truck mod “fits like a glove”

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


