Investor's Corner
What to look for in Tesla Motors Q1 Financials

Tesla (NASDAQ: TSLA) is set to announce its first quarter earnings report after market close on Wednesday, May 4, 2016.
TSLA reported 4th quarter 2015 earnings of $ -0.87 per share on February 10, 2016. This missed the consensus of $ 0.10 by $ -0.97 of the 16 analysts covering this company. Interestingly that turned out to be the end of a dramatic 42% slide which began on January 1st. Since then TSLA has moved from its lowest point of $141 on that day to roughly $250 per share, a 78% increase in just 3 months. That kind of tells you that TSLA is a stock not for the faint of heart.
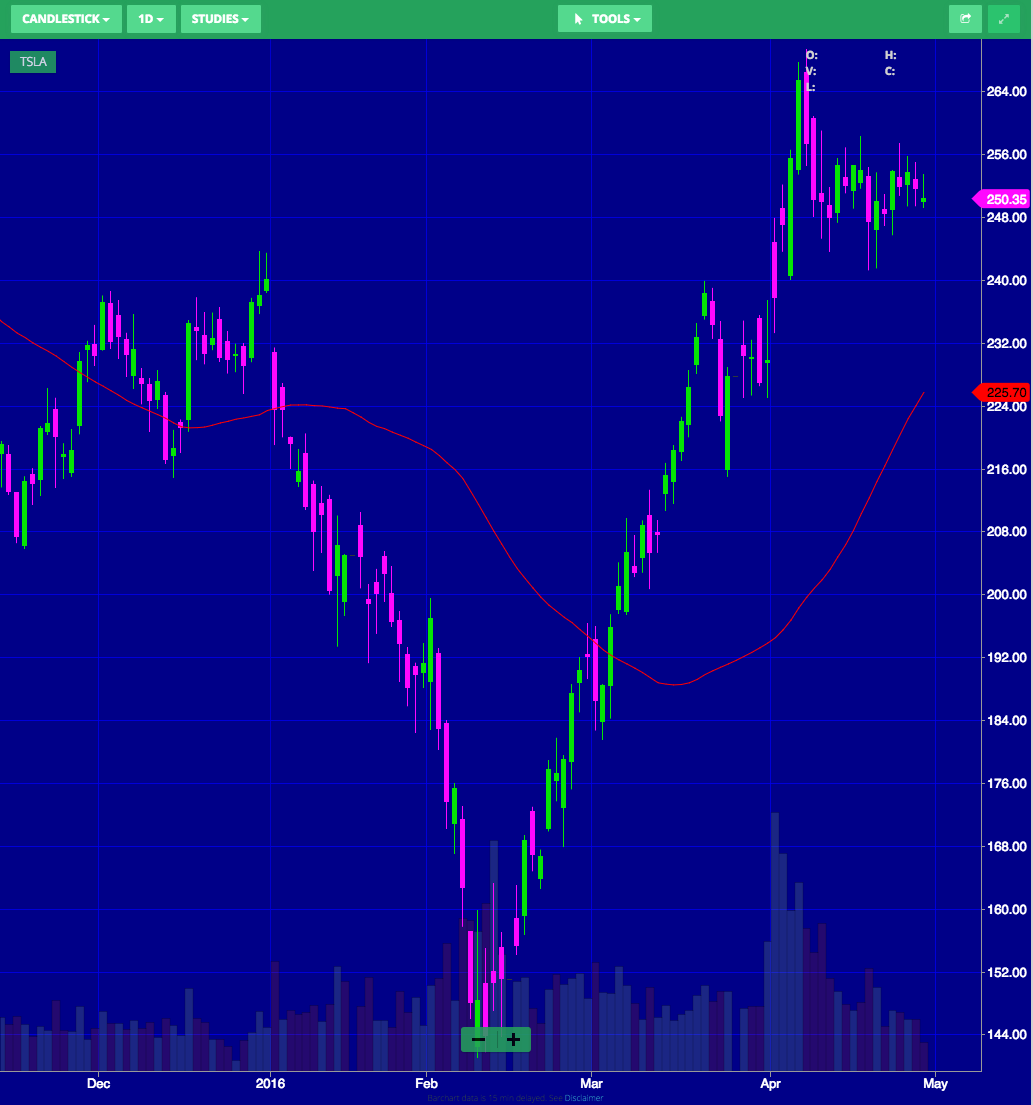
Source: WallSt I/O
The consensus of the 14 analysts covering TSLA for 1st quarter 2016 is a per share loss of $ -.57, with range estimates of: 0.080 | -0.569 | -1.000 (High | Mean | Low).
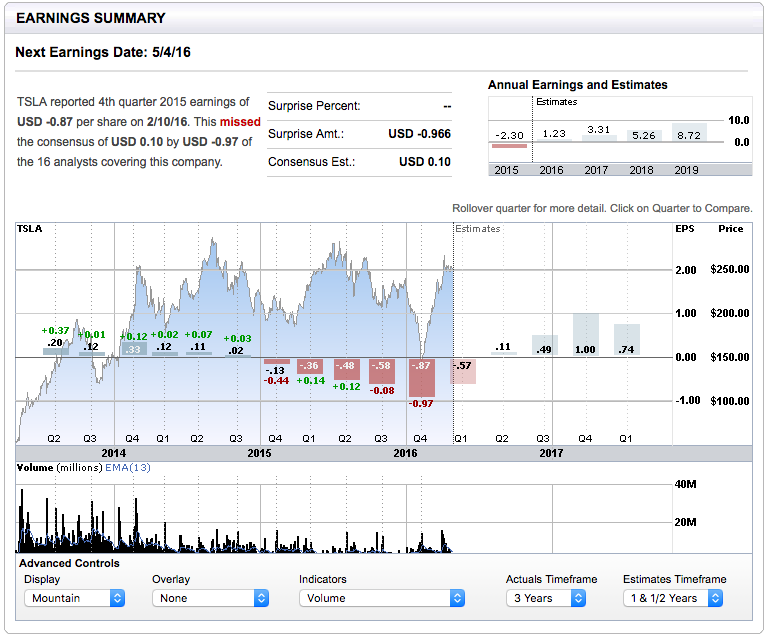
$TSLA earnings summary via E-Trade
Based on 20 analysts offering 12-month targets from TSLA, the average price target is $243.95, effectively a zero-move from the current stock price. If you are an “investor” in TSLA stock, the pros tell you that TSLA will not go anywhere in the next 12 months.
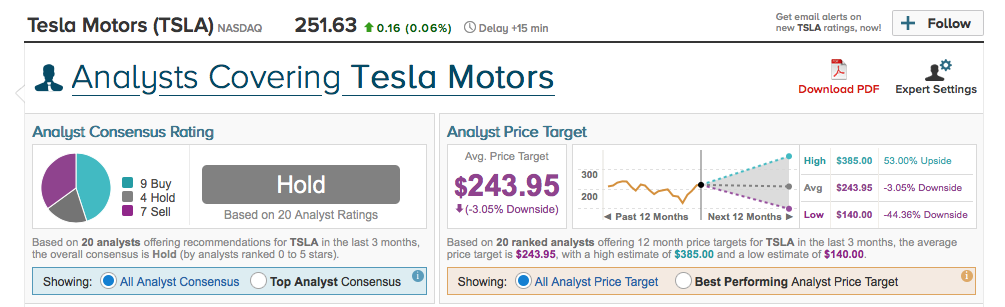
$TSLA analysis via TipRanks
So those are the numbers from the pros, but if you still decide that you want to trade TSLA stock, what should you be looking for in the quarterly results and the conference call webcast?
Q1 Vehicle Deliveries
Let’s take a look at a few items from the “Tesla 4th Quarter & Full year 2015 Shareholder Letter”.
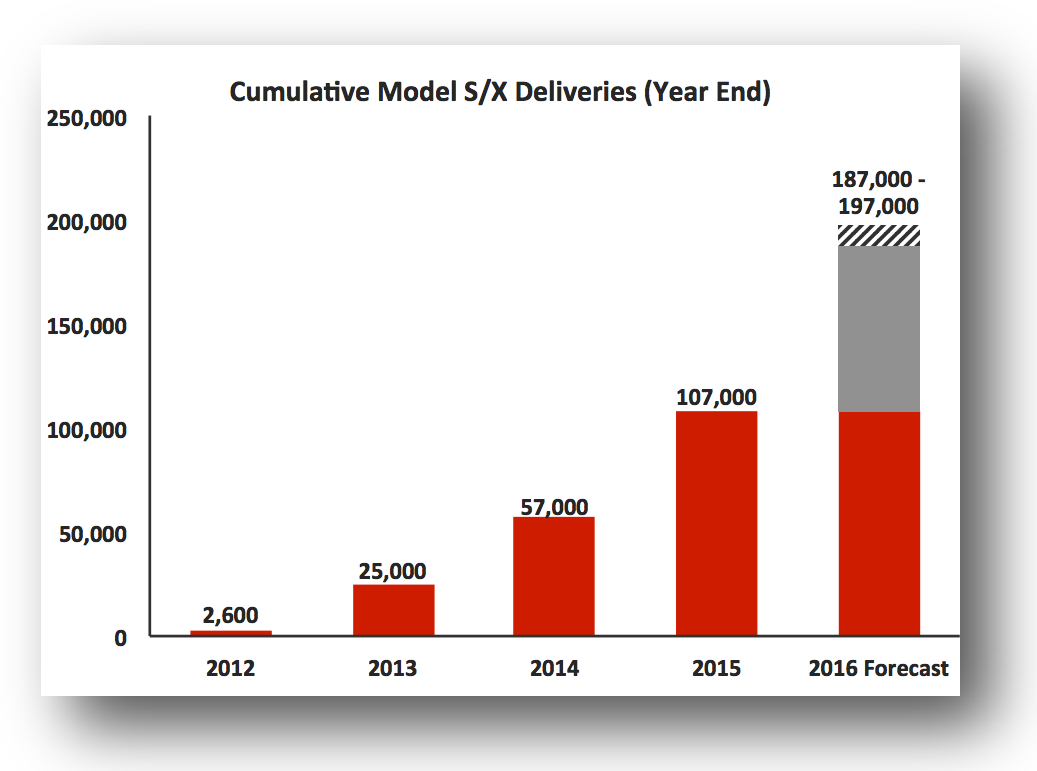
In the “Q1 and Full Year 2016 Outlook” section, Tesla states that “we plan to deliver 80,000 to 90,000 new Model S and Model X vehicles in 2016. […] In Q1, we plan to grow deliveries 60% year on year to approximately 16,000 vehicles”.
Source: Tesla Motors
We already know that Q1 deliveries did not meet the promised 16,000 units, as that number was actually 14,820, due to “severe Model X supplier parts shortages in January and February” as provided in a Press Release on April 4, 2016. In the same release, “Tesla reaffirms its full-year delivery guidance [of 80,000 to 90,000 vehicles].”
The missing income due to the delayed Model X vehicles delivery will be partially offset by the initial Model 3 “reservations”. It is quite interesting that reservations opened on March 31, 2016, the last day in the quarter, and at least 125,000 of them may be counted as an additional $125M income in Q1. In the end, guidance on vehicle deliveries for Q2 2016 will be one of the deciding factors on where TSLA stock moves post the Q1 report.
Cash Flow and Margins
In the same Q4 Shareholder Letter, Tesla states that “we expect to generate positive net cash flow and achieve non-GAAP profitability for the full-year 2016”, and “we plan to fund about $1.5 billion in capital expenditures without accessing any outside capital.” These are both very aggressive goals, especially in light of the 400,000+ Model 3 reservations, as of the latest disclosed counts. Elon Musk has already tweeted that he is “definitely going to need to rethink production plans”, which likely means that another factory will be needed to produce the Model 3 in a reasonable timeline that will allow delivery to the majority of the current reservation holders. This more aggressive delivery of Model 3 vehicles as originally envisioned will likely require outside capital for building such factory.
Definitely going to need to rethink production planning…
— Elon Musk (@elonmusk) April 1, 2016
Since missing the mark on Model X will impact cash flow for Q1, I would expect questions in the conference call asking if the issues have been resolved, and if the missing Model X numbers can be made up in Q2. While cash flow reversed action to the positive for the first time during Q4 2015, with a strong $179M cash flow from core operations, Tesla needs to prove that this behavior will continue in 2016.
Again in the Q1 Shareholder Letter, Tesla states that “Throughout the rest of 2016, Automotive gross margins should continue to increase. […] Model S gross margins should begin to approach 30% and Model X gross margins should be about 25%.” In Q4 gross margins were 20.9% for the Tesla Model S and even a slight increase in margins will be viewed positively by the market. This is a number that will be greatly watched as Tesla needs to prove that it can eventually deliver 500K+ vehicles / year at a profit. Much of the current valuation of Tesla stock is built on this assumption. Accordingly, a drop in margins for Q1 would be viewed very negatively by the market, at least for the short term.
Summarizing, besides vehicle delivery, cash flow and margins will be the other two drivers of the TSLA stock short-term market action after the Q1 report numbers are released.
Live Q&A Webcast
Tesla management will hold a live question & answer webcast on May 4 at 2:30pm Pacific Time to discuss the Company’s financial and business results and outlook. Live and replay webcast will be available at http://ir.teslamotors.com/eventdetail.cfm?EventID=171952 .
Tip of the Week
Starting with today’s posting I’ll be including a “tip of the week.” This may involve covering a trading concept, or recommending a website with tools or information useful to investors and traders of TSLA.
For this week, I am recommending signing up for the free Basic Membership of TipRanks. With it you can receive free alerts for 1 stock and 1 expert, which is enough for the ones just interested in TSLA stock. Happy trading.
Disclosure: I currently have no positions in any stocks mentioned, but I may plan to initiate positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Teslarati). I have no business relationship with any company whose stock is mentioned in this article.

Elon Musk
Elon Musk and Trump are closer than ever, and Tesla could be the big winner
Elon Musk sat beside Trump as AI leaders signed a voluntary White House safety accord.

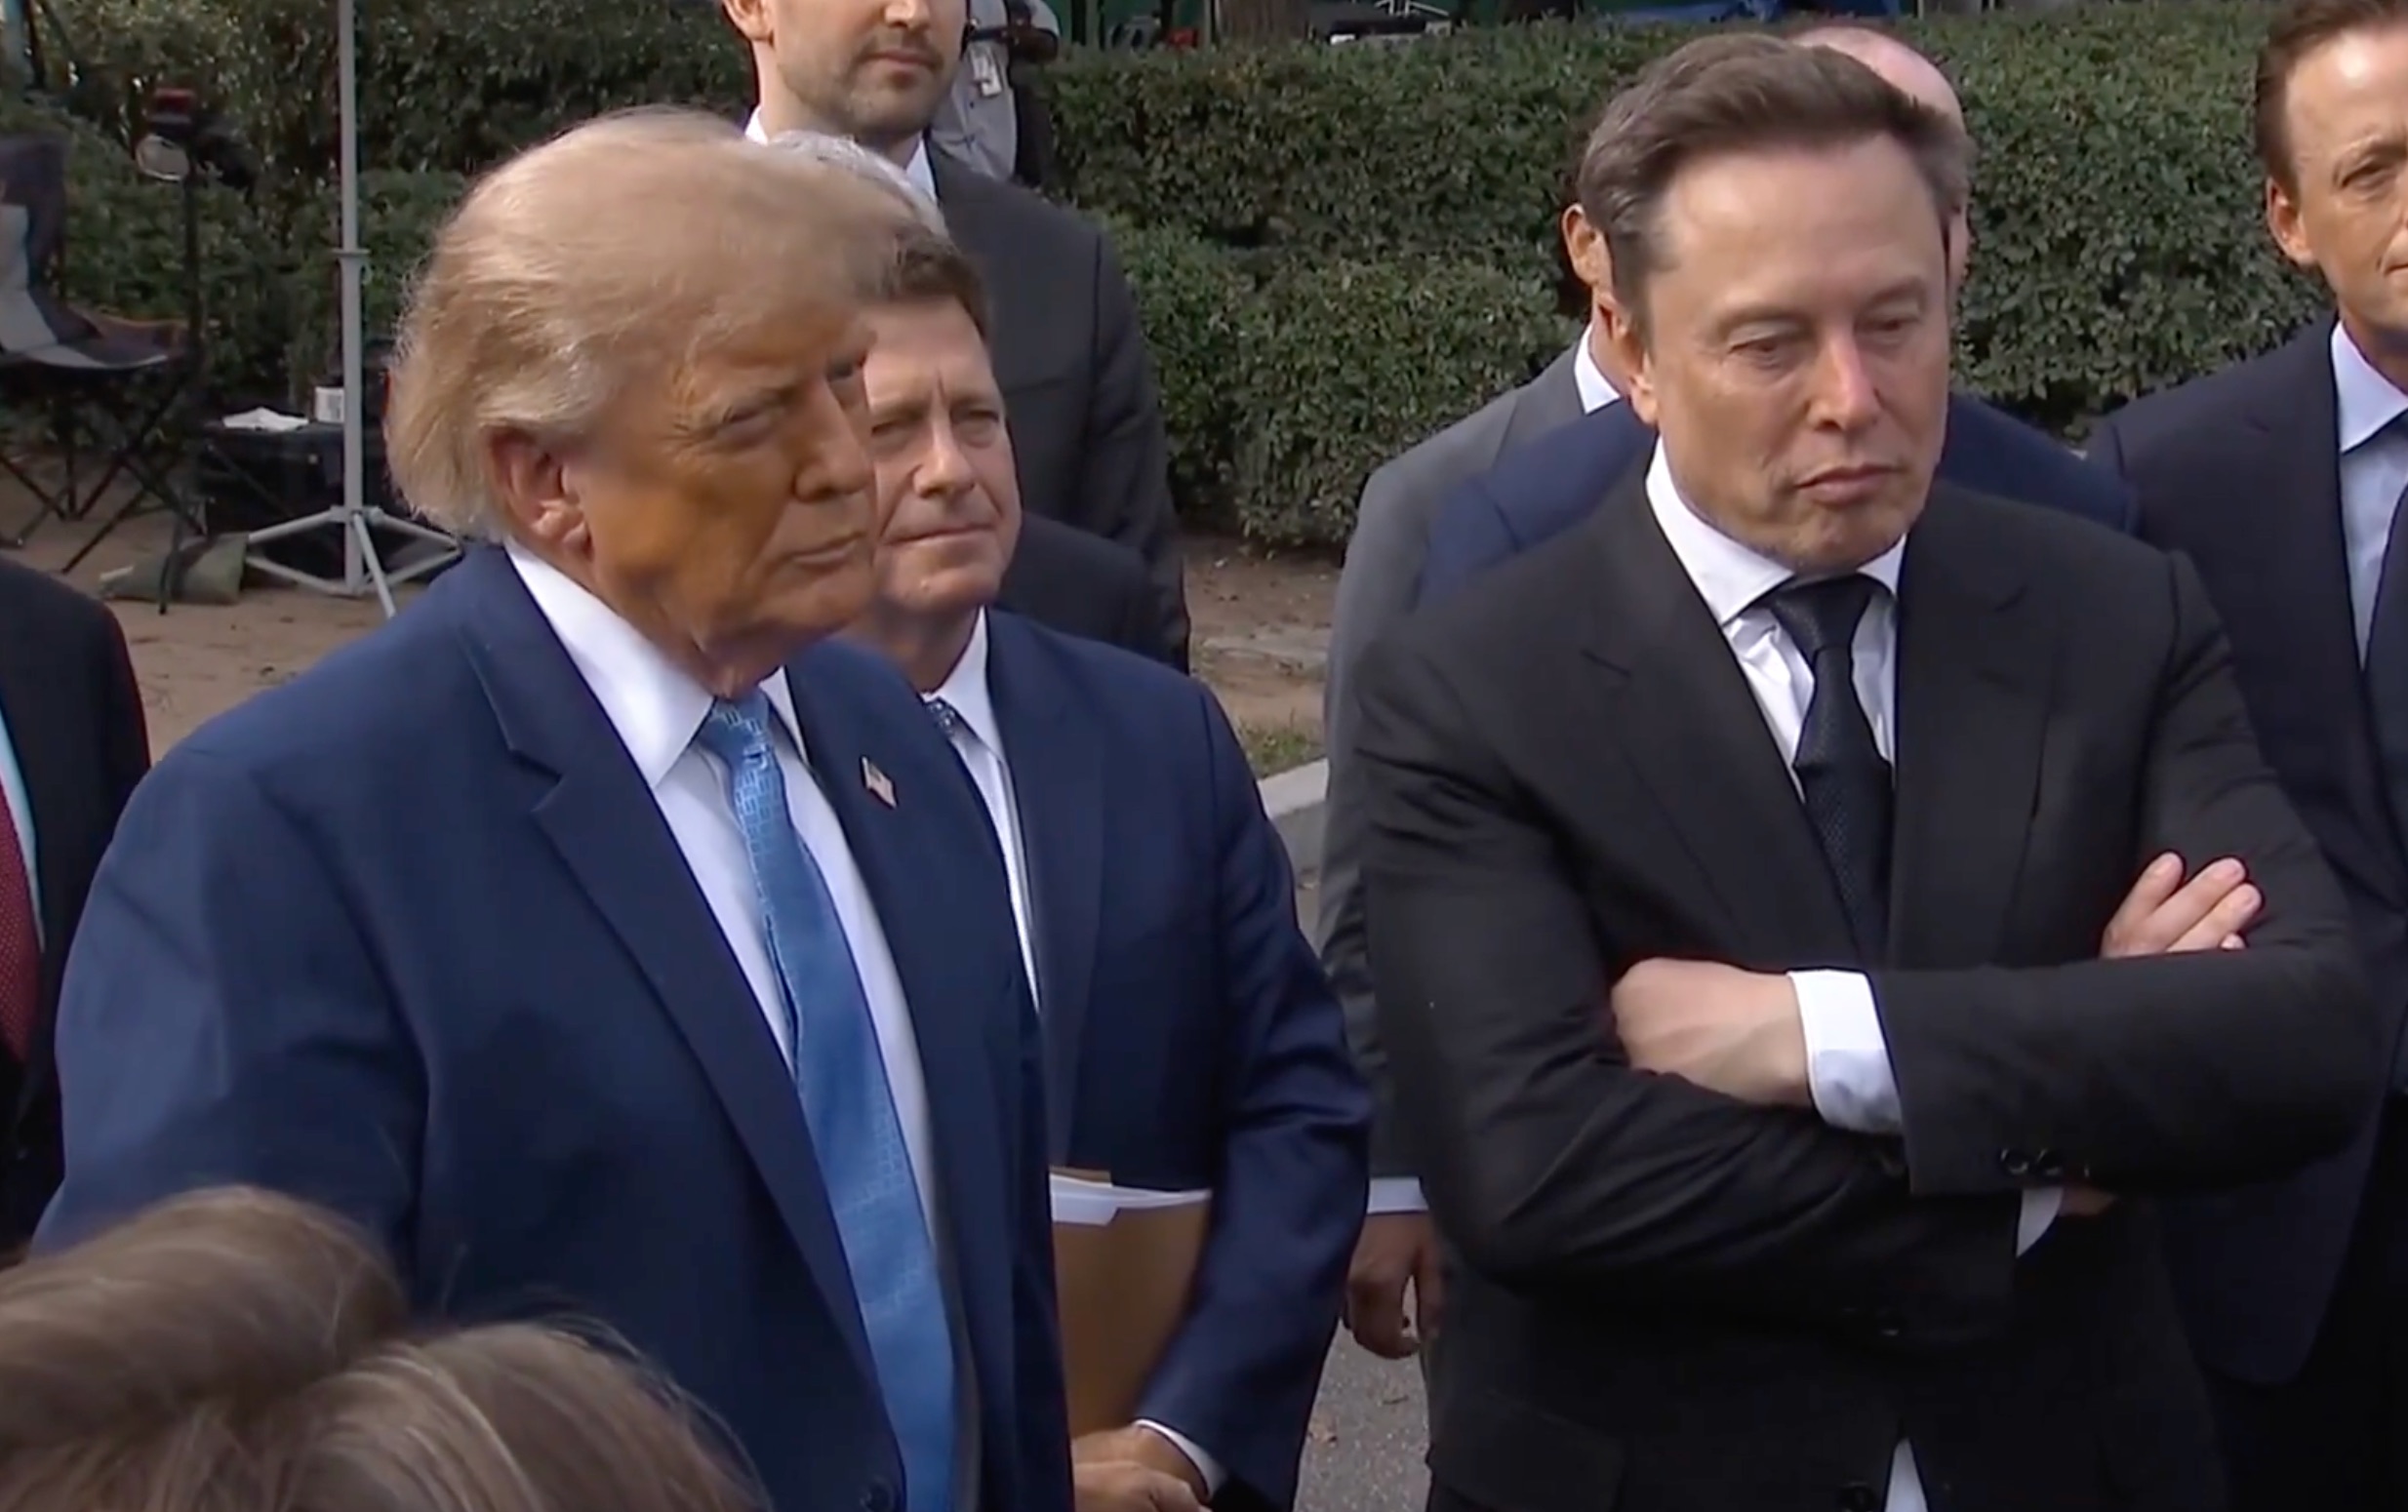
Elon Musk had the seat right next to President Donald Trump on Tuesday as the White House hosted the leaders of America’s biggest artificial intelligence companies for a lunch that ended with a voluntary industry accord on AI safety.
A seating chart Trump posted on Truth Social placed Musk at the president’s left in the East Room, with Nvidia CEO Jensen Huang on his right, according to an Associated Press reporter. Anthropic CEO Dario Amodei, OpenAI President Greg Brockman, Meta’s Mark Zuckerberg, Google’s Sundar Pichai, Microsoft’s Satya Nadella and Amazon founder Jeff Bezos also attended, along with Vice President JD Vance and House Speaker Mike Johnson.
🚨 Elon Musk is currently speaking to the media alongside President Trump after a meeting with AI Leaders in Washington today
Trump says AI is now being called “Super Intelligence” or SI pic.twitter.com/woJJqUVP9B
— TESLARATI (@Teslarati) September 29, 2026
After the lunch, Trump told reporters outside the West Wing that the executives had signed “The White House Accord on Superintelligence: A Joint Commitment on Frontier SI Responsibilities.” Johnson described it as a voluntary statement of principles built on “robust internal controls and layers of internal and external review,” while Zuckerberg said company boards would independently review reports from outside auditors. Trump called the document “morally binding,” said he would name a new AI czar within days, and signed an executive order formally renaming artificial intelligence “super intelligence,” CNBC reported.
Musk was not in the room for Tesla alone. Since SpaceX absorbed xAI, he runs the company behind Grok and one of the largest AI training operations anywhere. On September 25, he said another 220,000 Nvidia GB300 chips would come online at Colossus 2 within a week, with more expected in November and December.
“I think it is worth highlighting the positive benefits of A.I. … S.I., pardon me.”
“Thank you.”@elonmusk catches his own slip after calling the technology “A.I.” while speaking alongside President Trump and other tech leaders, quickly correcting himself to “super… pic.twitter.com/fH7CFileNb
— Fox News (@FoxNews) September 29, 2026
SpaceX confirms third massive compute deal at Colossus data center
Musk also used the trip to restate his energy ambitions. “SpaceX is aiming together with Tesla to do 200 gigawatts of solar production per year,” he said at an event in Washington. It is the same combined target he laid out that feeds directly into Terafab, the Tesla and SpaceX chip venture that will need enormous amounts of power.
The showing between Musk and Trump has come a long way, since the two had the very public split in mid 2025 after Musk opposed the “Big Beautiful Bill” and left DOGE. They reconciled at Charlie Kirk’s memorial that September, and Trump later called their relationship “good”. Since then, Musk has joined Trump’s China delegation in May and attended last week’s White House state dinner for Chinese President Xi Jinping.
For Tesla, that access to government official could pay dividends. As Teslarati noted in January, federal autonomy rules, NHTSA oversight and a single national standard for driverless vehicles all run through an administration Musk can more easily reach directly as Tesla works to scale Robotaxi and Cybercab beyond Texas.

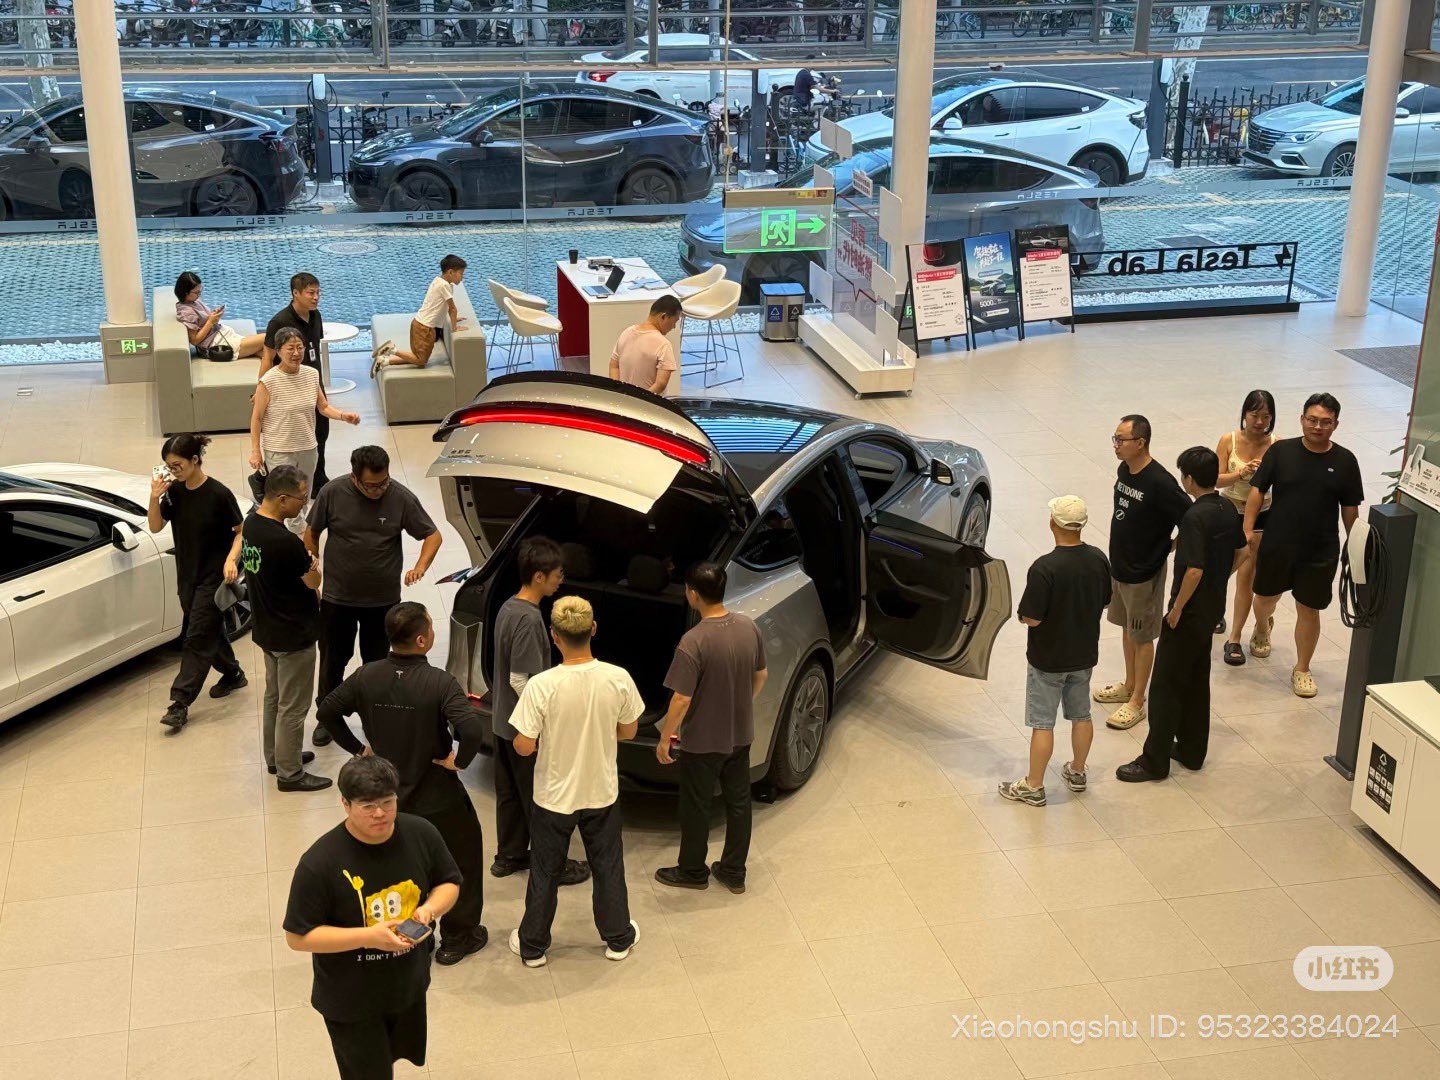
Tesla (NASDAQ: TSLA) showrooms have been picked clean ahead of the end of the third quarter of the year, as demand looks to be strong and delivery estimates for new vehicles are pushed into late 2026 and early 2027.
Tesla appears to have sold out of many of its Model 3 and Model Y trim levels in the United States, as only the Model Y RWD and Model Y All-Wheel-Drive are available for delivery before the end of the year.
Additionally, many showrooms are either completely empty or void of all but just one demo unit within the buildings themselves in an effort to bolster what could be one of Tesla’s best quarters in vehicle deliveries in recent memory.
I’m at Tesla right now and when I walked into their showroom I was shocked to see it basically empty.
I asked one of the people working there where all of the cars are “Gone – it’s the end of the quarter and we’ve sold out of everything… including the display vehicles”So… pic.twitter.com/rN7s3gE6sJ
— Devin Olsen (@DevinOlsenn) September 25, 2026
All the cars are gone from Tesla Century City!
All they have is Model Y L, a self-driving video playing on the background. I guess the best product is no product. Either that or they just sold the showroom cars. pic.twitter.com/mzCjWaXwww
— Whole Mars Catalog (@wholemars) September 26, 2026
Show room is empty. I asked and they have sold the demo cars too. Delivery numbers better be outstanding! pic.twitter.com/jq5N28Q6tZ
— Electric Brawl (@3lectricBrawl) September 22, 2026
Additionally, when I spoke to the guys at Tesla Mechanicsburg two weeks ago, when I returned the Model Y L, their third hauler of the week had just arrived, and every vehicle on it, along with every vehicle in their delivery lot, was accounted for and had a name attached to it for delivery.
Talking to the guys at the Mechanicsburg showroom on Friday, they couldn’t believe they had ANOTHER hauler coming in of cars for delivery—and each was accounted for
No car just sitting in inventory. They’re expecting a BIG quarter, and this is more than just the Y L https://t.co/ce801GkKVv
— TESLARATI (@Teslarati) September 21, 2026
Tesla saw a 25 percent increase in deliveries in Q2 compared to the same quarter the year before. The vast majority of the 480,126 units it delivered, 467,762 vehicles to be exact, were the Model 3 and Model Y.
In Q3 2025, Tesla delivered 497,099 vehicles, once again a figure that was dominated by the company’s two mass-market vehicles. Analysts have unusually wide predictions for this quarter, likely because so many firms missed the Q2 delivery figure by such a substantial margin; Wall Street predicted 408,000 cars, while Tesla delivered 480,000.
Goldman Sachs has Tesla slotted for 435,000 deliveries in Q3, while JPMorgan said it anticipates 482,000. The median guess is about 449,000 deliveries for Q3.
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Elon Musk
SpaceX turned a heralding moment for Starship into its greatest
Starship reached orbit despite losing an engine, deployed 26 Starlink V3 satellites on Flight 14.
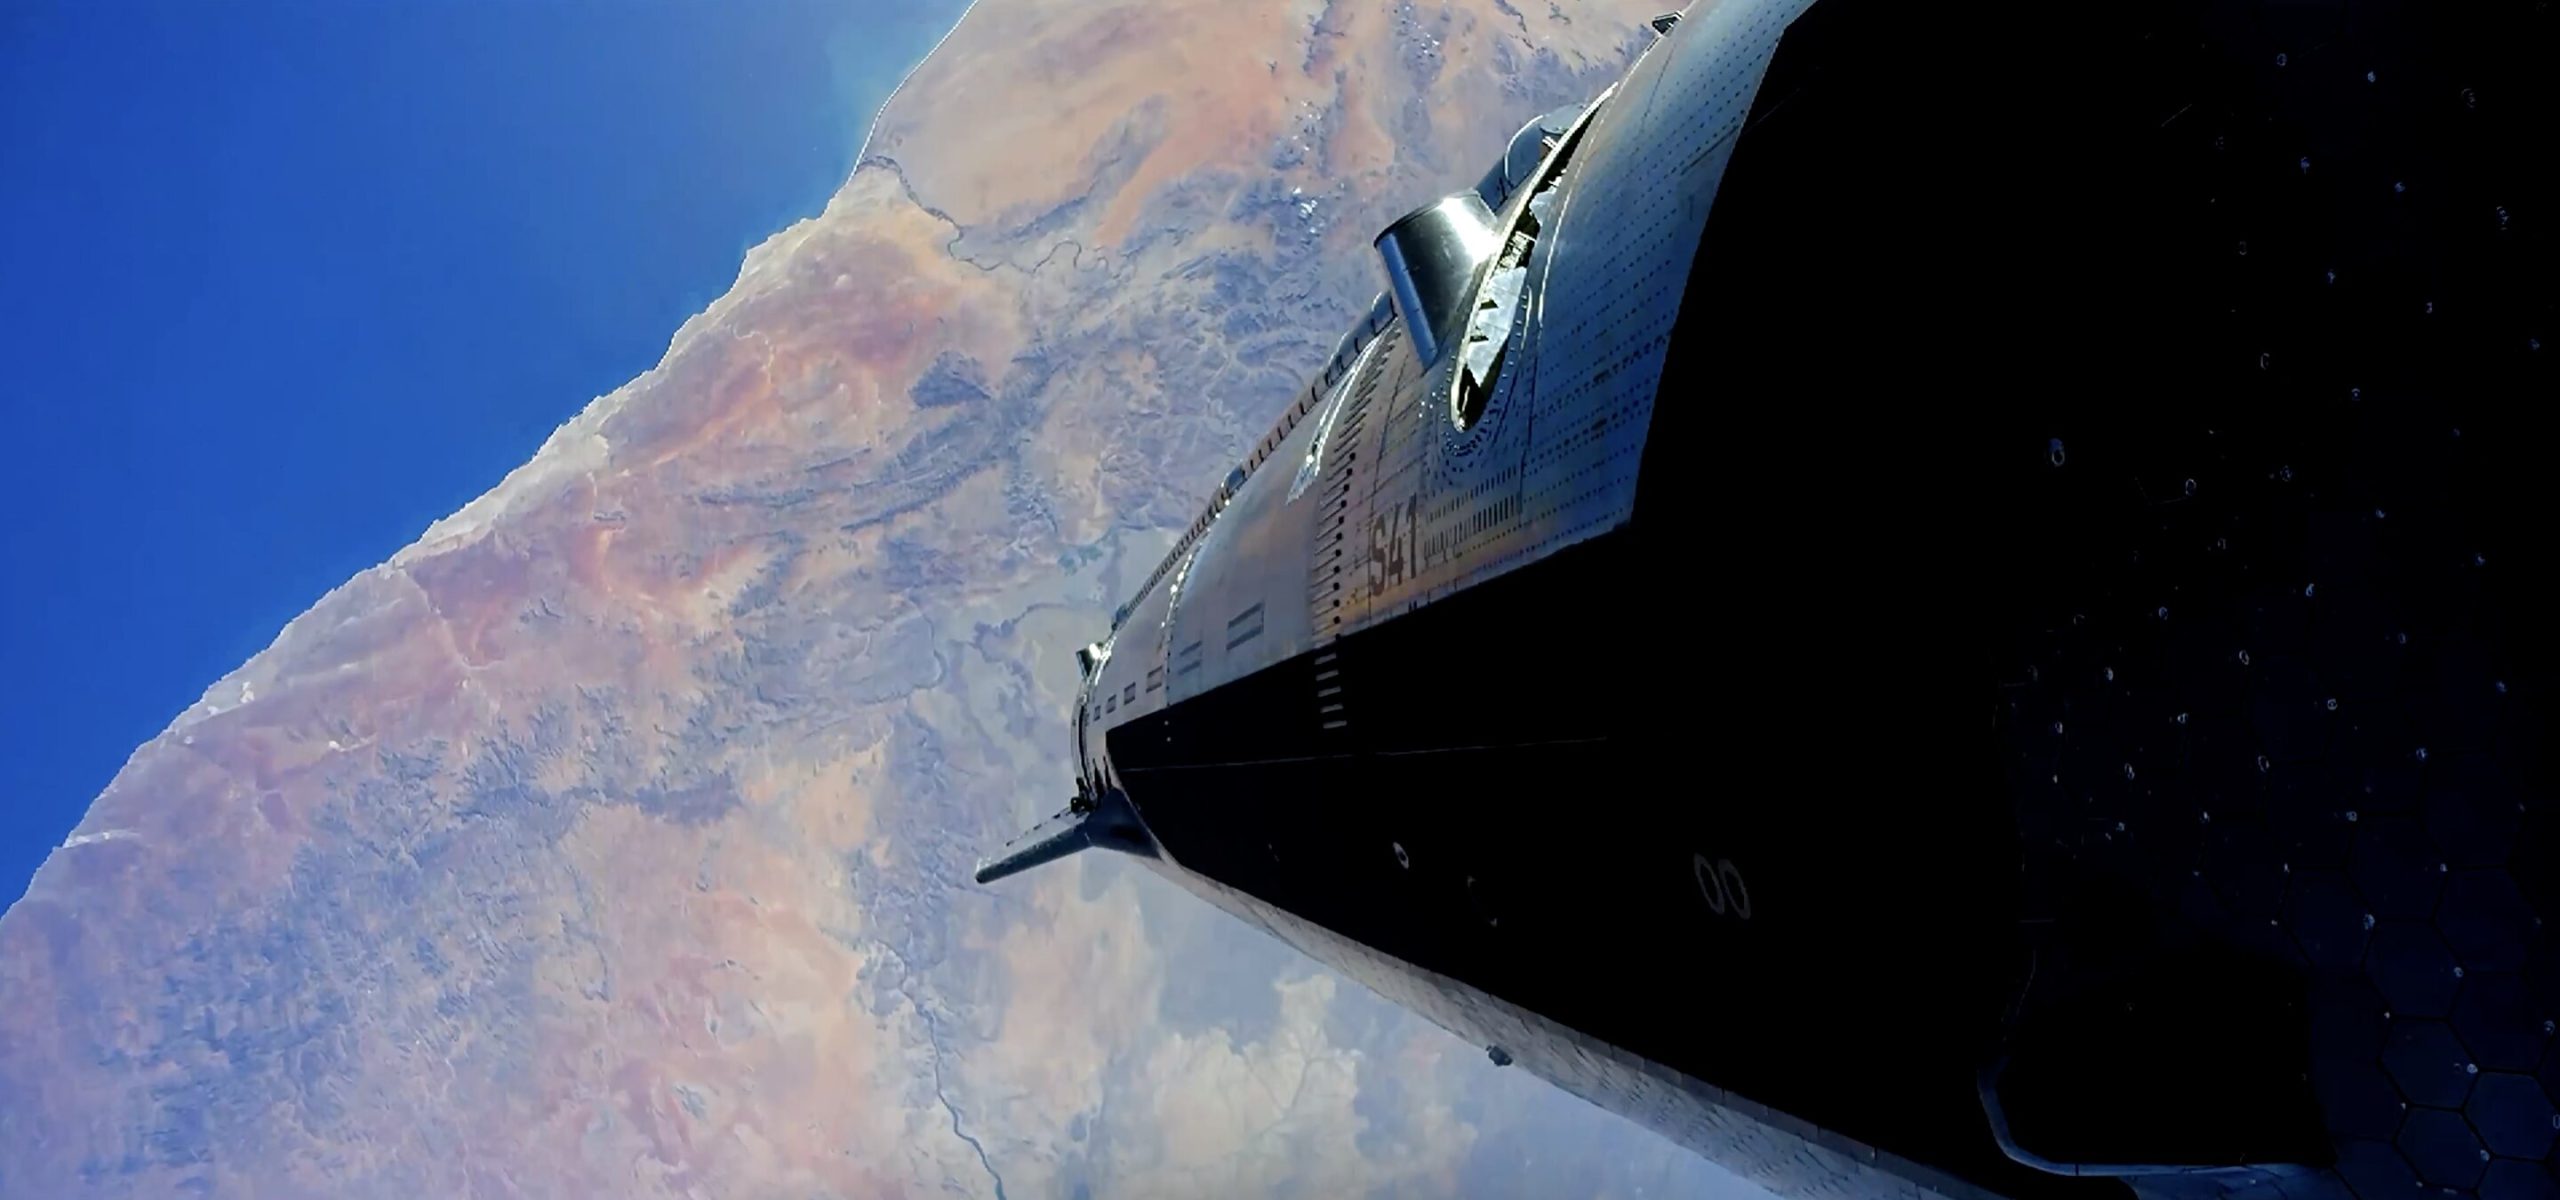
SpaceX’s Starship reached orbit for the first time on Monday, and for a few nail-biting minutes it looked like it wouldn’t. During ascent on Flight 14, one of Ship 41’s six Raptor engines shut down early, and SpaceX’s livestream host Dan Huot told viewers the team had decided not to commit to orbit. Minutes later, after what Huot described as a lot of conversation in the control room, the final poll came back in favor, and a roughly 19 second burn of a single Raptor pushed the ship into orbit about 170 miles up.
The reversal matters because SpaceX had written the exit ramp into the mission plan. The company said it would only fire the orbital insertion burn if flight controllers confirmed enough backup hardware remained for the deorbit burn, a condition Teslarati laid out ahead of the flight. Losing an engine was exactly the scenario that rule was built for.
Pressing forward fits Elon Musk’s history. Falcon 1 failed three straight times before its fourth launch reached orbit in 2008, with SpaceX nearly out of money, and Starship was developed by flying prototypes until they broke. What changed this year SpaceX going public, and with $SPCX sliding below its IPO price in July when Flight 13 slipped, the short interest climbed significantly, as Teslarati reported at the time. A Starship potentially lost today with revenue generating next-gen Starlink satellites aboard would have landed directly on shareholders.
Splashdown confirmed. Congratulations to the entire SpaceX team on the first orbital flight of Starship! pic.twitter.com/urjmiwnvNl
— SpaceX (@SpaceX) September 28, 2026
That pressure showed up after orbit. SpaceX cut a flight planned to last nearly 10 hours to about three, moving splashdown from west of Chile to the North Pacific near Hawaii. SpaceX gave no reason, though Musk said this month the company was being extremely cautious about debris risk. The single Raptor for deorbit worked, and Ship 41 completed its flip and landing burn before breaking apart in the water, an outcome SpaceX expected. Musk has structured SpaceX’s governance to shield long term bets from market pressure.
The payload is the bigger business story. Musk posted that all 26 Starlink V3 satellites deployed and are “operating nominally.” Each V3 is rated for about 1 Tbps of downlink and 160 Gbps of uplink, so this single launch adds roughly 26 Tbps, about 10 times what a Falcon 9 load of V2 Mini satellites adds. The V3 is too large for Falcon 9, making Starship the only vehicle that can build out the planned 100,000 satellite constellation, at up to 60 per flight once it reaches routine service. Unlike the 20 V3 units on Flight 13, which reentered on a suborbital path, these will raise their orbits and could begin serving customers within weeks and bring in hundreds of millions of additional dollars in projected Starlink revenue.
SpaceX has already begun winding down Falcon 9 Starlink launches from Florida in favor of Starship. Reported targets put Flight 15 as early as October 19, leaving about three weeks to diagnose Monday’s engine shutdown before the next orbital attempt.
Starship’s 14th flight is set to launch on Monday, Sept 28. The 75-minute launch window opens at 7:15 a.m. CT. Live coverage of the mission starts ~35 minutes before launch → https://t.co/uQKQvgaTmJ
— SpaceX (@SpaceX) September 27, 2026

SpaceX set to launch astronauts and a classified Falcon Heavy mission on the same day

Tesla Cybercab and Semi have more in common than you might think


