News
(Op-ed) A neutral look at Tesla’s upcoming Q1 2025 vehicle deliveries
Elon Musk affects Tesla, but his impact on the company’s raw vehicle sales may not be as notable as critics would suggest.

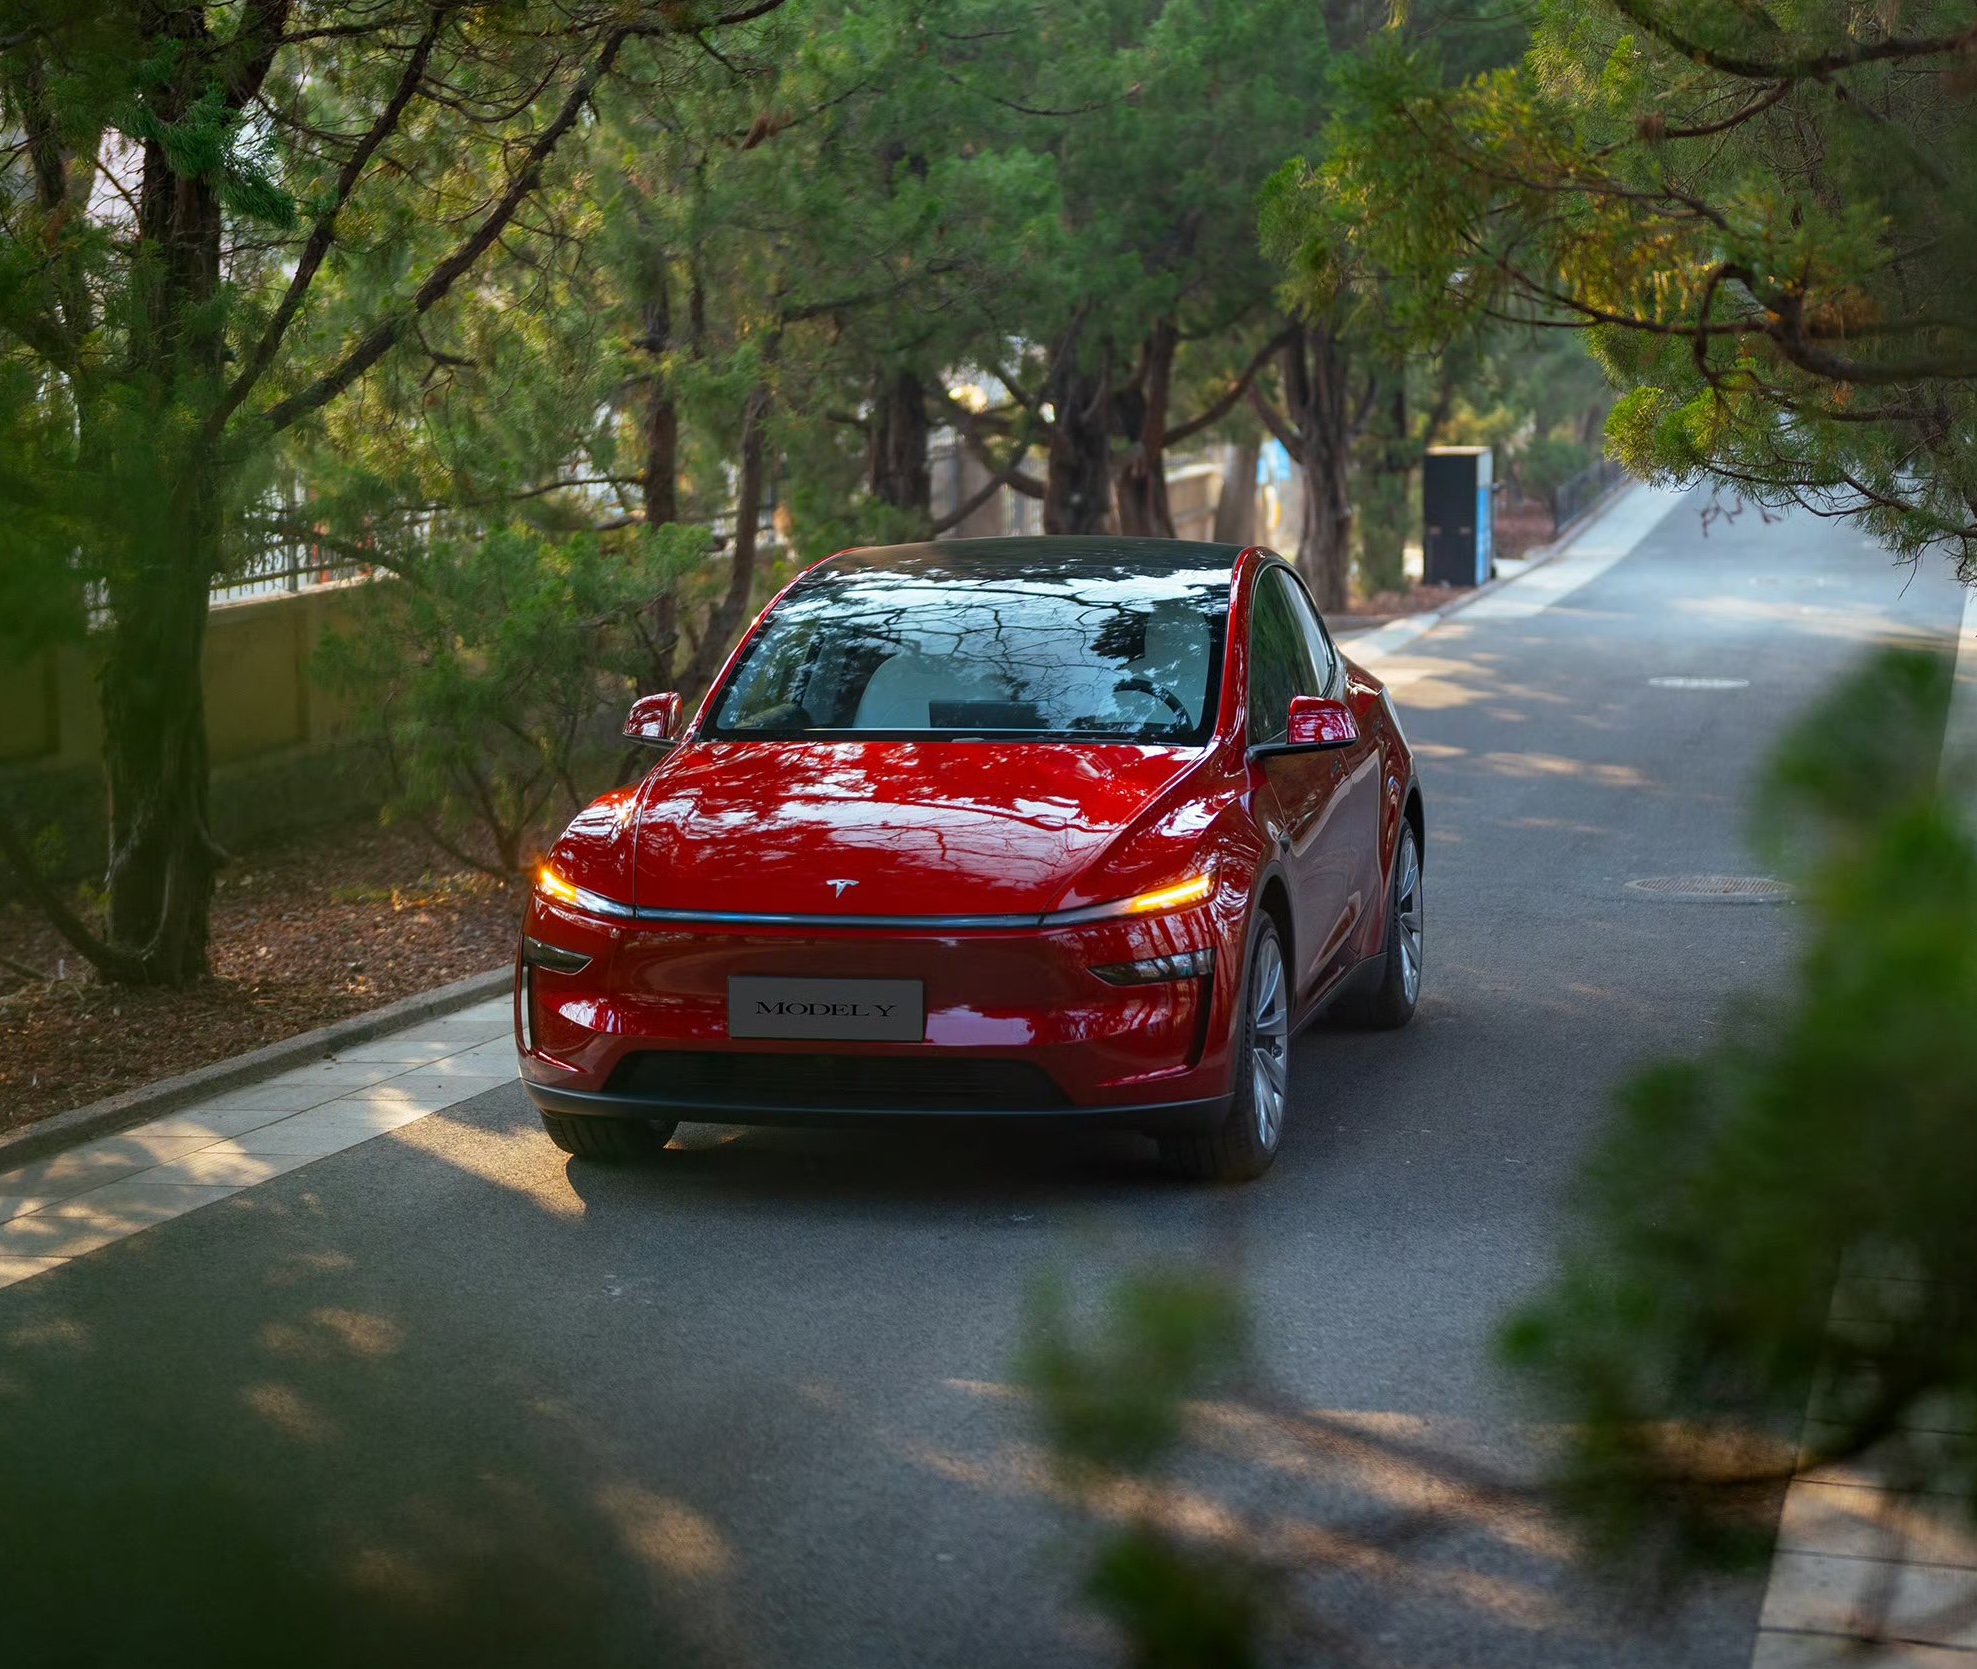
Tesla is such a volatile topic for many that it’s difficult to get a neutral image of the company and its fundamentals today. A look at Tesla news coverage shows this, as even dedicated electric vehicle blogs and tech publications seem to find it difficult to separate Tesla from Elon Musk, who is more polarizing than ever.
This is what I aim to cover in this op-ed. I will be exploring Tesla’s first quarter vehicle deliveries, why they might be underwhelming, the reasons behind them, and why I believe the sky is not necessarily falling.
A likely miss
Analyst consensus for Tesla’s Q1 2025 deliveries currently stands at 418,000 vehicles. That would suggest a year-over-year improvement of 8.06% from the 386,810 vehicles that Tesla was able to deliver in the first quarter of 2024. Considering Tesla’s sales in China and Europe over January and February, 418,000 deliveries seem to be a long shot for the first quarter of 2025.
It would not be surprising at all if Tesla ends up missing Wall Street’s consensus estimates, and by a pretty wide margin. Such is expected considering Tesla’s focus in the first quarter. But what is this focus, really? Elon Musk’s politics? Not necessarily.
A Model Y-shaped hole
Critics and negative Tesla news coverage would argue that the company’s steep drop in sales in several European markets and China is a sign that the company is finished, or that Elon Musk is doing global damage to the Tesla brand. However, Tesla’s sales decline this Q1 may actually be affected in no small part by the company’s transition from the Model Y classic to the new Model Y, which was launched across the United States, China, and Germany.
The Model Y is Tesla’s strongest seller, and it comprises a huge portion of the company’s deliveries every quarter. Considering that the Model Y classic quite literally became the world’s best-selling vehicle by volume in 2023 and 2024, it would not be an exaggeration to state that Tesla’s deliveries have been greatly carried by the all-electric crossover. What would happen then if Tesla implements a transition to the Model Y’s new version across its factories worldwide? Raw Model Y deliveries will go down, at least until Tesla starts deliveries of the revamped all-electric crossover. This is exactly what seems to be happening in China.
A look at Tesla China’s numbers from January and February will show that the company saw fewer registrations this year compared to last year. However, vehicle registrations have since picked up with the start of the new Model Y’s domestic deliveries. Similar trends may emerge in the United States and Europe, as well as territories supplied by Giga Shanghai, Giga Texas, the Fremont Factory, and Giga Berlin.
The Elon Musk factor
There is no doubt that Elon Musk is at his most polarizing today, but to credit Tesla’s low deliveries to the CEO’s political antics is very shortsighted. Yes, Elon Musk affects Tesla, but his impact on the company’s raw vehicle sales may not be as notable as critics would suggest. This could be seen in the results of a poll from German publication t-online, which initially concluded that 94% of Germans won’t buy a Tesla anymore. As it turned out, the survey would end up painting the complete opposite picture once more respondents took the poll. With more than 467,000 respondents on the survey, over 70% stated that they would buy a Tesla.
To state that Elon Musk’s political actions are not adversely affecting Tesla’s appeal to some consumers would not be accurate. There are evidently people who will not be purchasing a Tesla due to Elon Musk and his work with the Trump administration. The impact of the Musk factor, however, may not be as drastic as Tesla critics would suggest. It would not, for example, result in 94% of car buyers suddenly swearing off Tesla. The vast majority of consumers, after all, generally gravitate to the best products in the market, period. Assuming that this is true for most consumers today, Tesla’s vehicles definitely still have a fighting chance this year.
In conclusion
Considering Wall Street’s 418,000 vehicle delivery consensus, it almost seems certain that Tesla will miss this estimate by a notable margin. This would likely result in a wave of reports alleging that demand is drying up worldwide or Musk has completely tanked the brand’s appeal to consumers. With the new Model Y now starting its deliveries across the globe, however, Tesla’s real performance and a clearer view of Musk’s effect on the company’s demand, would likely become more evident in the coming quarters.



SpaceX (NASDAQ: SPCX) will report its second public earnings call today since its IPO earlier this year, and there are a few things we expect to hear about, as well as Wall Street analysts, who have already outlined their expectations for the call.
Wall Street analysts have a consensus of $12.72 billion in revenue and an earnings per share (EPS) of $0.13. These are broken down into three sectors: Space, Connectivity, and AI/SI, which are perceived in this way:
- Space: $1.41 billion
- Connectivity: $4.84 billion
- AI/SI: $6.47 billion
Other outlets cluster near $12.8 or $12.9 billion in revenue and $0.14 – $0.15 EPS. This implies a roughly 65 percent sequential growth from Q2’s $7.81 billion, driven mostly by AI/SI, with the first post-IPO positive EPS expected.
Here are the three things to watch for on the call:
AI Revenue Ramp and the $100B+ ARR target
AI is truly the swing factor for SpaceX, and analysts expect it to roughly double from Q2’s $2.56 billion and become about half of total revenue. Management previously guided to a $100 billion+ annualized run rate by December, including the Cursor acquisition, which was $60 billion, to close the quarter.
Listen for updates on SpaceX’s compute capacity, especially pertaining to its contracts with Google, Anthropic, and others, revenue per watt, any new deals, and Cursor’s early contribution.
Starlink/Connectivity Metrics and Mobile Expansion
Connectivity remains a main profit engine for SpaceX. Subscriber additions will be something to pay attention to, as Q2 ended at 12 million and previews are looking at 14 million for this quarter. Additionally, ARPU trends, enterprise and government growth, and any commentary on Starlink Mobile will be something to pay attention to, especially following the recent low-band spectrum deal and FCC-related constellation approvals.
Capex Trajectory, Cash Burn/FCF, and Starship/Operational Updates
Q2 capex of roughly $18.4 billion weighed on the stock. Investors will look to scrutinize Q3 spending levels, any guidance on the pace into Q4/2027, free cash flow, backlog, and liquidity. Operational color on Starship (Flight 14 milestones and Flight 15 timing/reusability progress), Falcon cadence, and government/NASA contracts are also in focus.
Of course, there will also be some speculation on the potential Tesla-SpaceX merger, but there was nothing mentioned in the company’s proxy it sent earlier this week.
SpaceX will report earnings after market close today and will stream the call on X.
Watch live as SpaceX discusses our Q3 2026 earnings at 3:30pm CT today → https://t.co/Qrb0qeVG15
— SpaceX (@SpaceX) October 20, 2026
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here
News
SpaceX just launched its secret Starfall saucer again
SpaceX launched its Starfall capsule again on Bandwagon-5, this time listed openly beside rideshare customers.

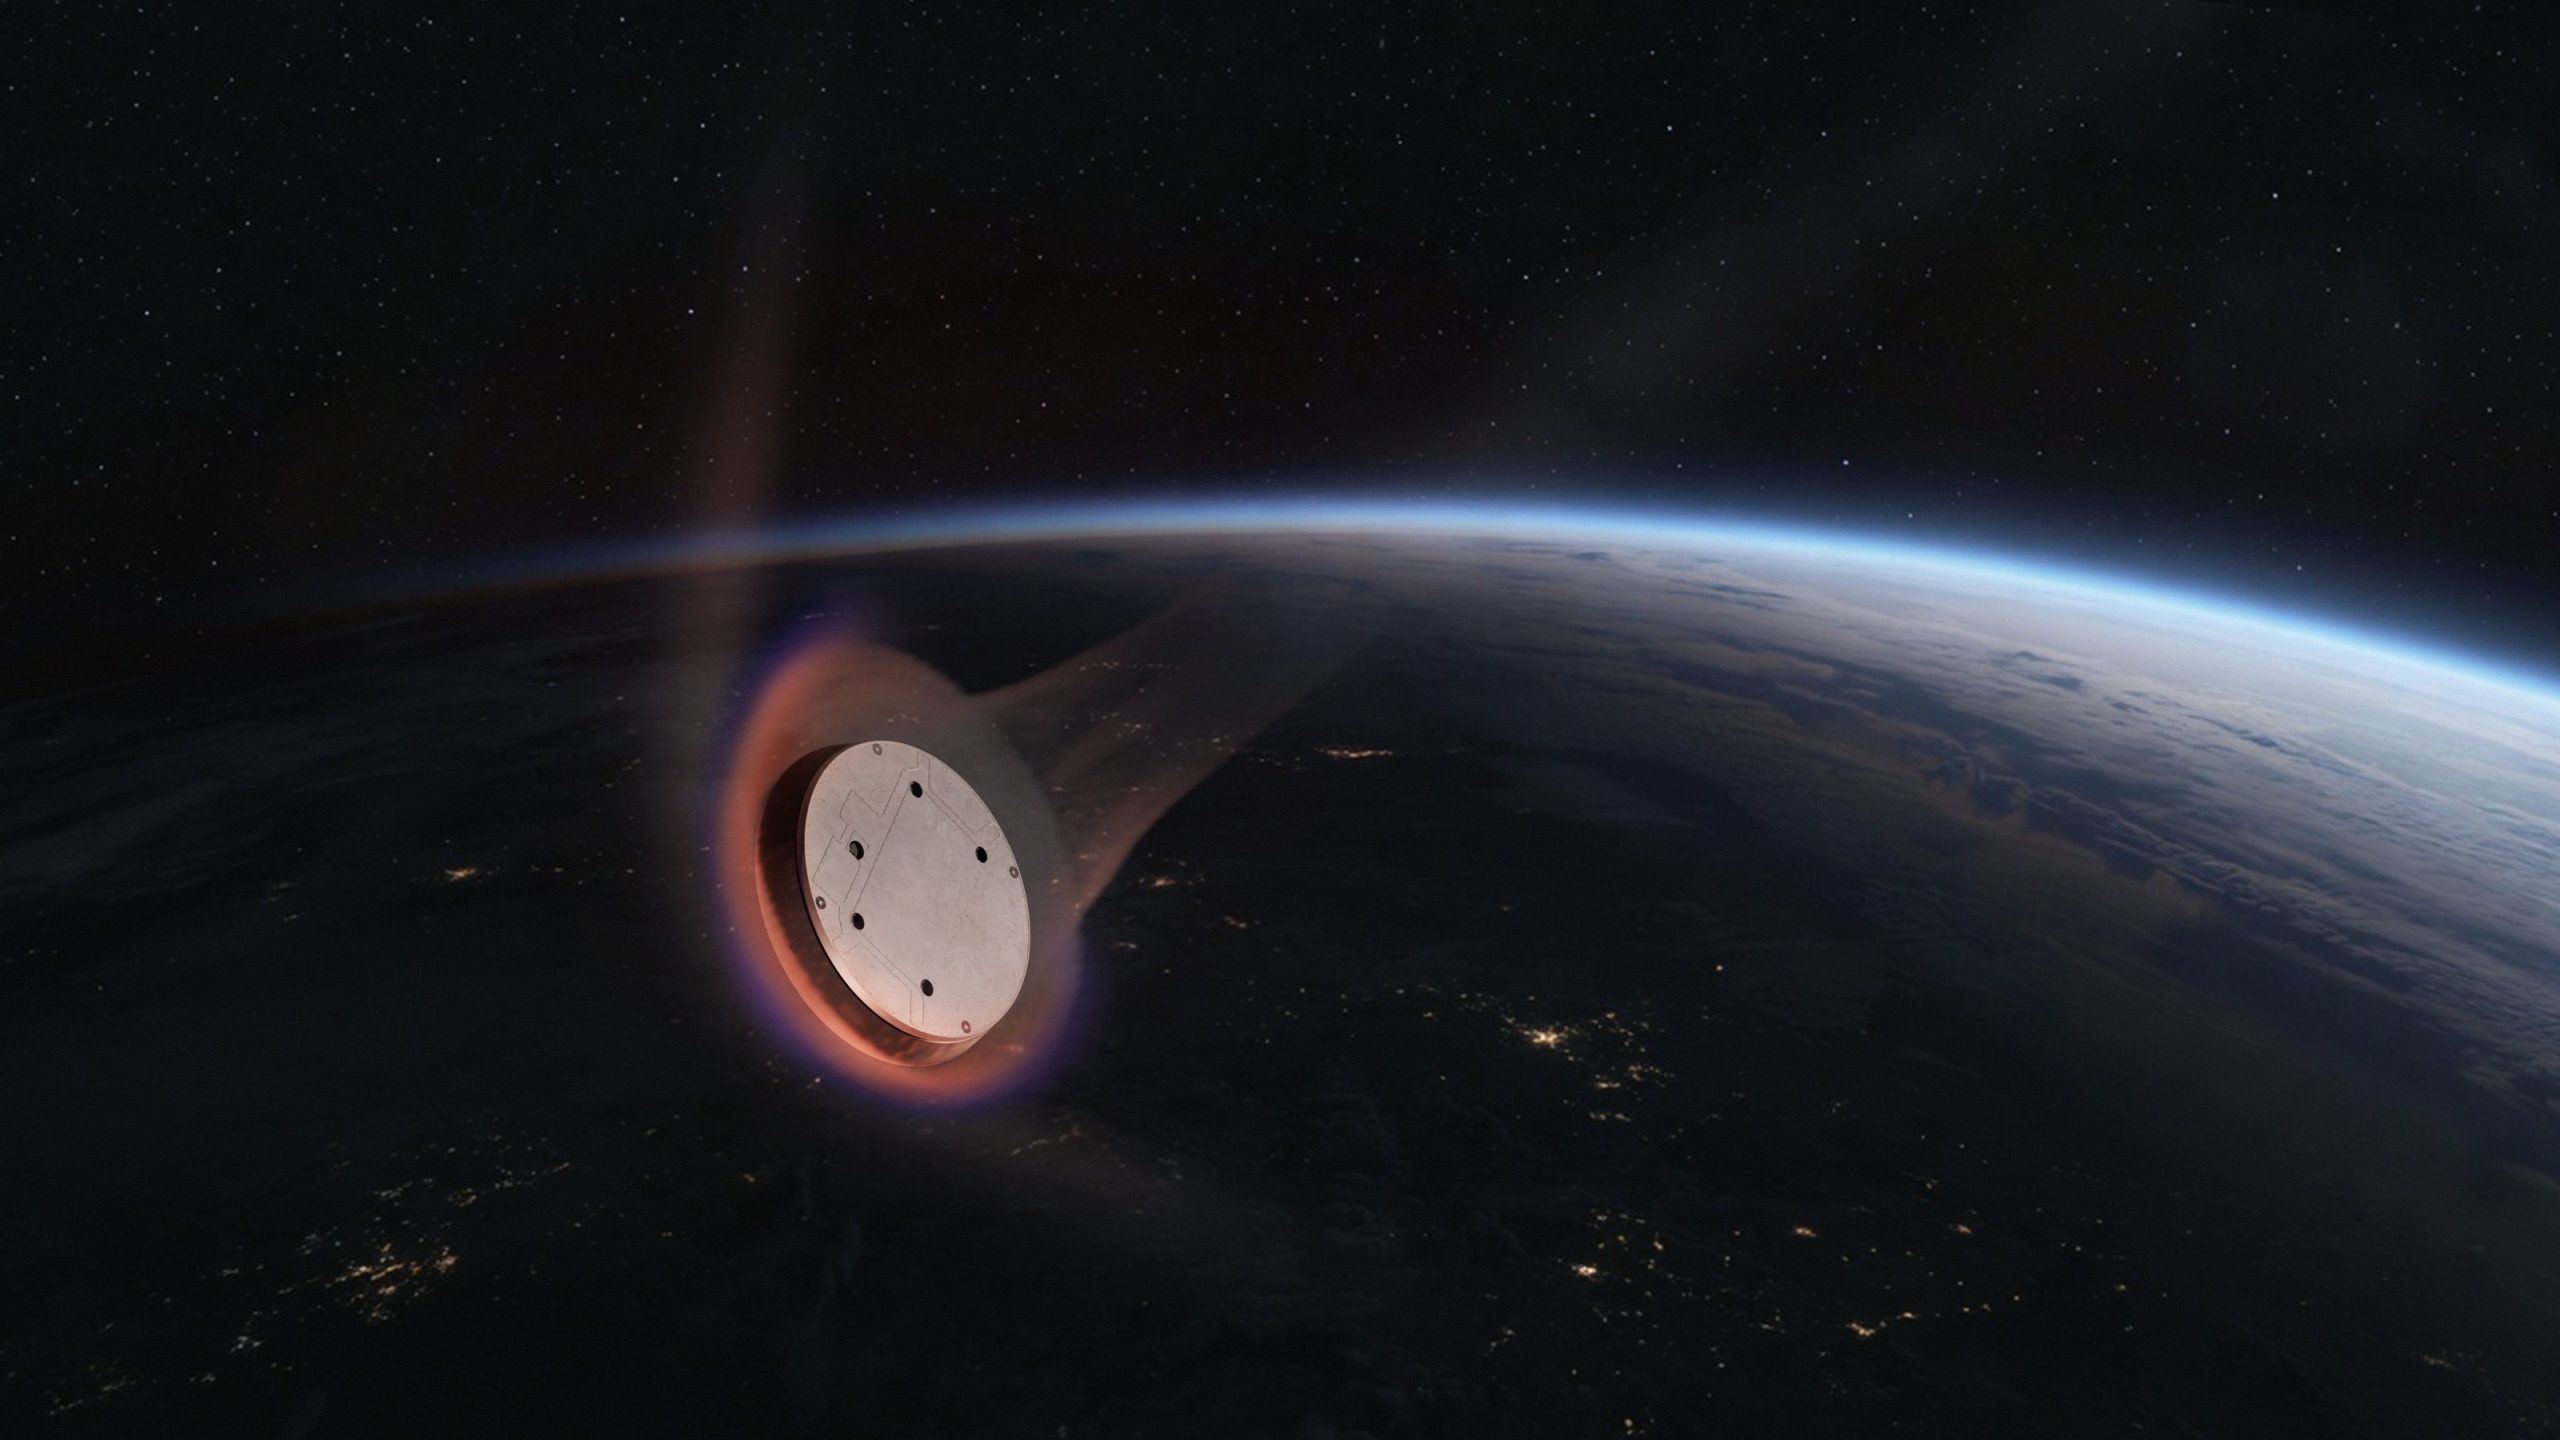
SpaceX launched its Starfall reentry capsule for the second time on Tuesday morning, flying it as the payload of the Bandwagon-5 rideshare mission. Falcon 9 lifted off from Space Launch Complex 40 in Florida at 7:04 a.m. ET with 32 payloads, and the first stage booster, on its 19th flight, landed on the droneship A Shortfall of Gravitas about nine minutes later.
Starfall was scheduled to separate last, 2 hours and 48 minutes after liftoff. The final customer satellite on SpaceX’s mission timeline comes off the upper stage about an hour and nine minutes in, which left a long gap before the capsule was due to be released alone. SpaceX later posted that the payload deployment sequence is complete. At liftoff, the company said Starfall “enables affordable, routine access to a microgravity environment, providing unique opportunities for on-orbit manufacturing, scientific research, and testing.”
Starfall enables affordable, routine access to a microgravity environment, providing unique opportunities for on-orbit manufacturing, scientific research, and testing https://t.co/y8kJg3QDor
— SpaceX (@SpaceX) October 20, 2026
As Teslarati reported before the first Starfall flight, SpaceX made no public announcement about the vehicle then, and nearly everything known came from FAA and FCC filings. This time Starfall is an item name on the official mission page, listed beside paying rideshare customers. SpaceX has still not said what, if anything, is aboard this Starfall, Spaceflight Now noted.
The FAA’s environmental assessment from May describes a disk about 10.2 feet wide and 2.5 feet tall that weighs roughly 4,600 pounds and can bring 2,200 pounds of payload back to Earth.
Interestingly, the same rocket also carries a competitor’s hardware. Varda Space Industries launched its W-Series 7 capsule on Bandwagon-5, a spacecraft about three times smaller than Starfall that will test whether microgravity can improve the solubility of a cancer drug called Protac. It is Varda’s ninth reentry capsule, and W-8 and W-9 launched earlier this month on Transporter-18. SpaceX has been Varda’s launch provider since the company’s first Falcon 9 rideshare contract in 2021.
SpaceX has not published where or how this Starfall will come down. The preview we ran in June described a recovery from the Pacific Ocean, and the company has not said whether this flight follows the same plan. The launch also arrives hours before SpaceX posts its third quarter results after the market closes, a report we previewed earlier this week.
Elon Musk
The Boring Company’s latest Tesla tunnel truck mod “fits like a glove”
The Boring Company has modified a Tesla powered tunnel truck to carry freight containers underground.
The Boring Company has found a second job for the Tesla hardware it already runs underground. In a post on X, Elon Musk’s tunneling company showed its latest Prufrock Liner Truck modified to carry a standard 20 foot shipping container. “Using TBC tunnels to transport freight,” the company wrote. “The latest Prufrock Liner Truck (using Tesla Model 3 batteries and drive units) has been modified to carry a standard 20′ shipping container. Fits like a glove!”
The photo shows a red container sitting on a long, low white chassis parked outside, with drive hardware visible at one end. The Boring Company did not say where or when freight hauling would start, which customers it has in mind, or how many trucks it is converting.
Using TBC tunnels to transport freight.
The latest Prufrock Liner Truck (using Tesla Model 3 batteries and drive units) has been modified to carry a standard 20’ shipping container.
Fits like a glove! https://t.co/VV0phWK4fc
— The Boring Company (@boringcompany) October 19, 2026
Until now, the liner trucks have hauled concrete. Teslarati reported in August on Liner Truck 3, which uses Model 3 battery packs and drive units to move more than 22,000 pounds of precast tunnel segments to the boring machine. It has 28 miles of range, tops out at 12 mph, and is piloted remotely from the company’s operations center in Texas. The freight version appears to be the same platform with a different bed, and The Boring Company has not said whether it will also be remotely piloted.
Freight has been on the company’s menu for years. When TBC updated its product lineup in 2021, its freight tunnel was described as sized to fit a standard shipping container, “barely.” The company later used the idea at Tesla’s own factory, where Prufrock 3 dug a tunnel to Giga Texas that now moves finished Cybertrucks away from the production line.
The Boring Company closed a $3 billion Series D in September at a $23 billion valuation, and Teslarati has covered how that money is tied to a UAE tunneling push and a faster Nashville build. In Nashville, Prufrock MB1 and MB2 are mining at the same time, and a third machine is expected to launch in late October. Each machine needs a steady supply of liner trucks, so any design that works for segments and containers alike gives the company more use out of the same Tesla parts.
The Vegas Loop remains the only Boring Company system open to the public, and it moves passengers in Tesla vehicles. A freight service would be a separate product, and the post gave no indication that one is close to launch. For now, it is a truck, a container and a short caption saying they fit together.

SpaceX reports its second earnings today: here’s what to expect

SpaceX just launched its secret Starfall saucer again

The Boring Company’s latest Tesla tunnel truck mod “fits like a glove”

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


