Investor's Corner
Tesla (TSLA) share price ‘far from an aberration’ based on 2020 developments

Tesla (NASDAQ: TSLA) has gained significant notoriety on Wall Street after an extremely successful year in terms of trading. After a 400% spike in TSLA’s trading price so far in 2020, some refer to the stock as an aberration or an outlier that will soon realize its true valuation when other car companies catch up. However, one of Tesla’s biggest investors, investment firm Baillie Gifford, is arguing the other way, stating that its developments in 2020 speak for themselves.
“Whilst the company and its colorful founder attract an unusually high degree of attention, emotion, and noise, the underlying return picture is far from an aberration. Returns are concentrated in a handful of big winners,” the firm’s managers said in a report on November 6th. “Tesla has made significant operational progress. It has successfully added capacity, and the production ramp of its latest model has progressed far more smoothly than for any of its previous vehicles. Demand for its products is strong, and the response from its traditional competitors remains muted,” it added, according to The Guardian.
Gifford is spot on with its assessment of Tesla. The year 2020 has been tough, but the Silicon Valley-based electric car maker has accelerated toward its product’s global dominance through brand loyalty and innovation. The proof of growth is shown in the company’s Quarterly Earnings Calls, with its most recent numbers describing increased demand and a need for more efficient manufacturing to keep up with orders. Tesla has been focused on increasing its manufacturing and production lines, looking for new facilities to lead the way with sources of innovation.
But Tesla “mania” hasn’t been friendly to all. The self-proclaimed and outspoken short-sellers admit that the EV revolution’s leader is harming their portfolios. Ask David Einhorn of Greenlight Capital Re, who said that his firm lost $22.8M during the first nine months of 2020.
Who Wears Short Shorts: David Einhorn’s Ghost Hunt for Tesla’s Weakness
Short-sellers are right when they say that Tesla has been an outlier, but not in a way that will benefit their portfolios. The electric automaker has realized significant growth financially and in terms of production and delivery rates during a time where other companies in the same industry have fought to remain relevant. Tesla is undoubtedly the leader in electric transportation, and other car companies have been vocal about the company’s lead in the sector. Volkswagen and Audi are two companies that have admitted Tesla is years ahead of the competition.
Baillie Gifford is the second-biggest winner from Tesla’s share price increases in 2020. The only entity that has won bigger: Tesla’s CEO Elon Musk.
The firm holds about £16.7B, or $21.96B, in Tesla shares. This figure would be larger if the firm weren’t forced to sell some of its TSLA holdings earlier this year when the concentration of its portfolio had overflown with the electric automaker’s value. To keep its portfolio balanced for investors, the firm sold some TSLA shares.
Tesla’s dominance of the EV sector certainly has made some rich, and Gifford is one of them. The firm’s loyalty to the Tesla mission has made its portfolio extremely valuable in a matter of nine months, and it believes that the company’s plans will only further solidify the presence of its electric car revolution.
Disclaimer: Joey Klender is a TSLA Shareholder.


Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.
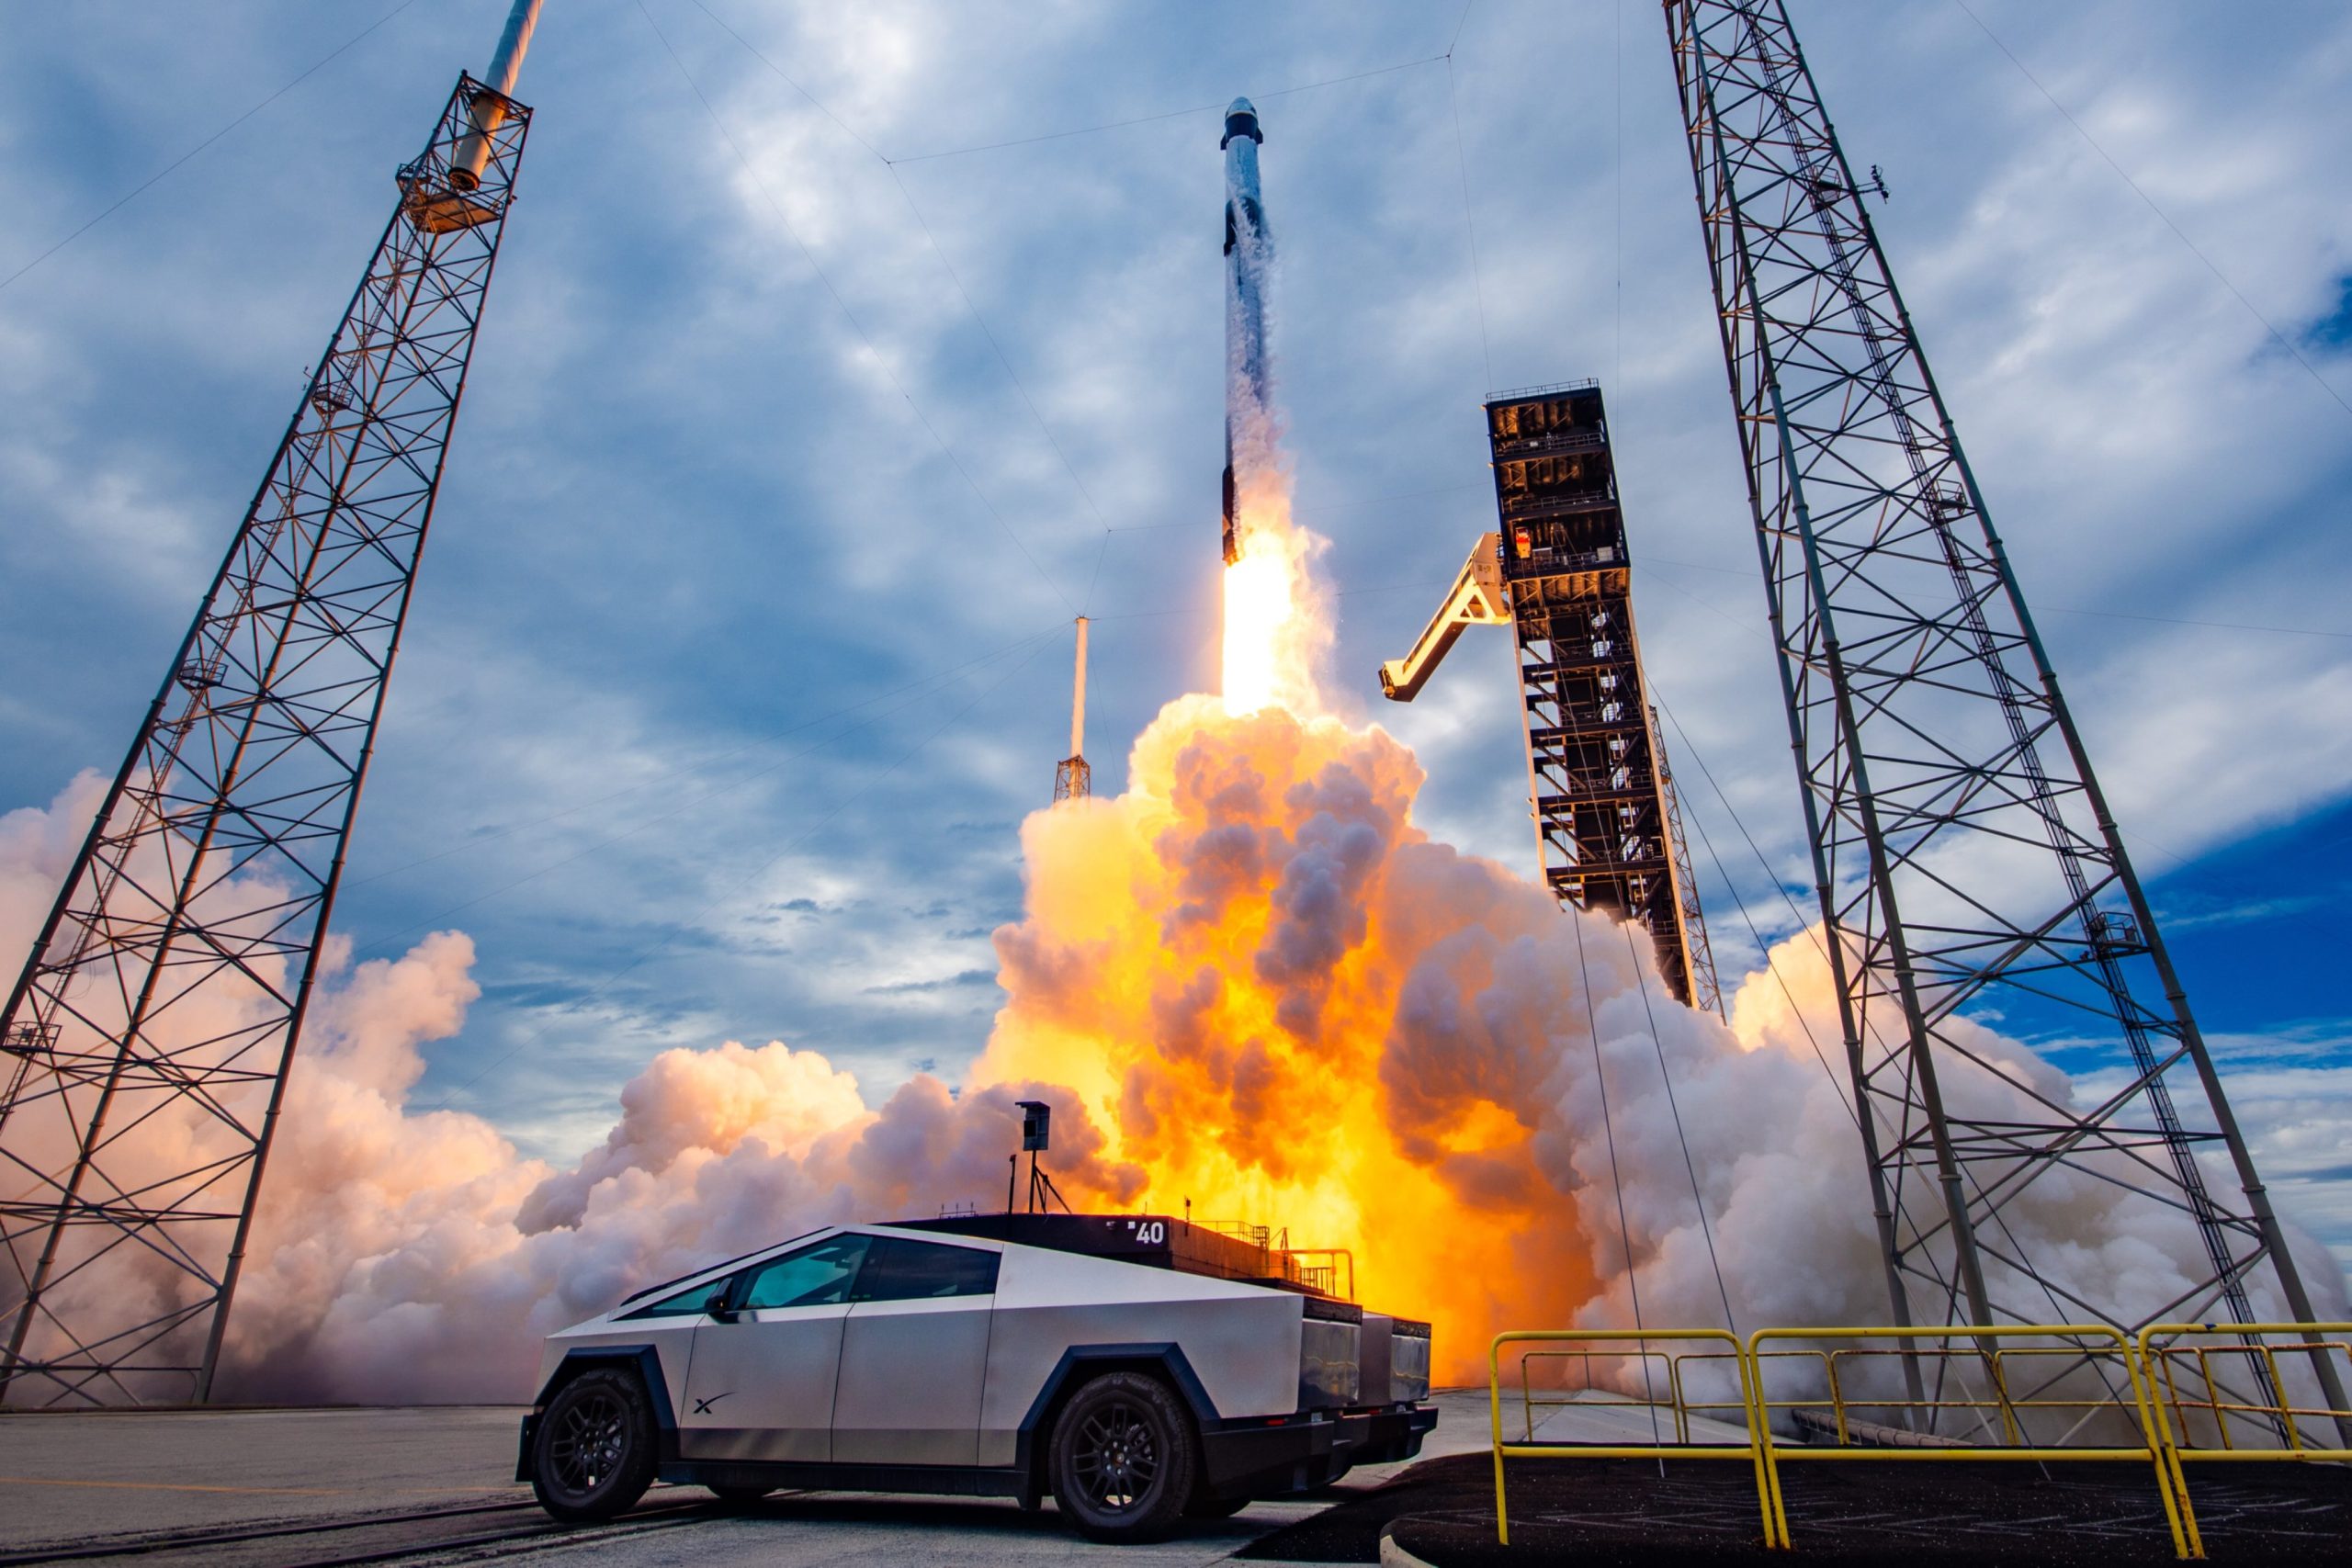
Wall Street analysts rapidly raised price targets on SpaceX (NASDAQ: SPCX) after the company reported a bullish third quarter for 2026 following the market close on October 20. Shares were sent sharply higher in after-hours and premarket trading.
SpaceX posted revenue of $14.6 billion, a 161 percent year-over-year increase that comfortably topped consensus estimates, which fell near $12.7 billion. The company also posted a net profit of $4.4 billion from a prior-year loss, with adjusted EBITDA reaching $8.8 billion.
More price target movement:
🚀 Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
🚀 Barclays raised its target to $300 from $254 (Overweight).
🚀 Citi increased its target to $240 from $200 (Buy),
🚀 UBS moved to $230 from $210 (Buy)
🚀TD Cowen raised its target to $224 from $200 (Buy).
🚀Morgan Stanley held an Overweight rating with a $300 target.
🚀Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.— TESLARATI (@Teslarati) October 21, 2026
Its Super Intelligence (AI) division generated roughly $7.6 billion and became the largest revenue contributor, growing nearly 830 percent year-over-year, while the Connectivity segment delivered $5.2 billion on strong subscriber additions that lifted the consumer base to 13.6 million for Starlink.
The Earnings Call proved especially catalytic, as CEO Elon Musk and CFO Bret Johnsen outlined Q1 2027 revenue guidance of $33 billion to $37 billion, which was far above the roughly $22 billion analysts had modeled, alongside fourth-quarter capital-expenditure plans of $35 billion to $40 billion focused on AI compute infrastructure at sites including Memphis and Southaven.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
Management targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end and discussed pathways to 13 gigawatts or more by the end of 2027. Musk described relentless demand from hyperscalers and other customers, with compute pricing supporting payback periods of less than a year and potentially as short as six months.
Additional highlights included Starship’s recent orbital success and V3 satellite deployment, Starlink pricing and enterprise momentum, rapid Grok Bot adoption, spectrum expansion plans, and the formation of special committees to explore a possible combination with Tesla.
These elements prompted a wave of price-target increases:
- JPMorgan more than doubled its target to $500 from $240 while maintaining an Overweight rating.
- Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
- Barclays raised its target to $300 from $254 (Overweight).
- Citi increased its target to $240 from $200 (Buy),
- UBS moved to $230 from $210 (Buy), and
- TD Cowen raised its target to $224 from $200 (Buy).
- Morgan Stanley held an Overweight rating with a $300 target.
- Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Shares, which closed at $147.79 on October 20, jumped roughly 8 percent in early premarket trading on October 21 as investors digested the results and the newly elevated Street targets.
The average analyst price target has moved higher, which reflects greater conviction in SpaceX’s trajectory across launch, connectivity, and the Super Intelligence business, even as elevated spending remains a point of focus.
Elon Musk
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Tesla and SpaceX formed special committees to weigh a merger, and Elon Musk supports it.

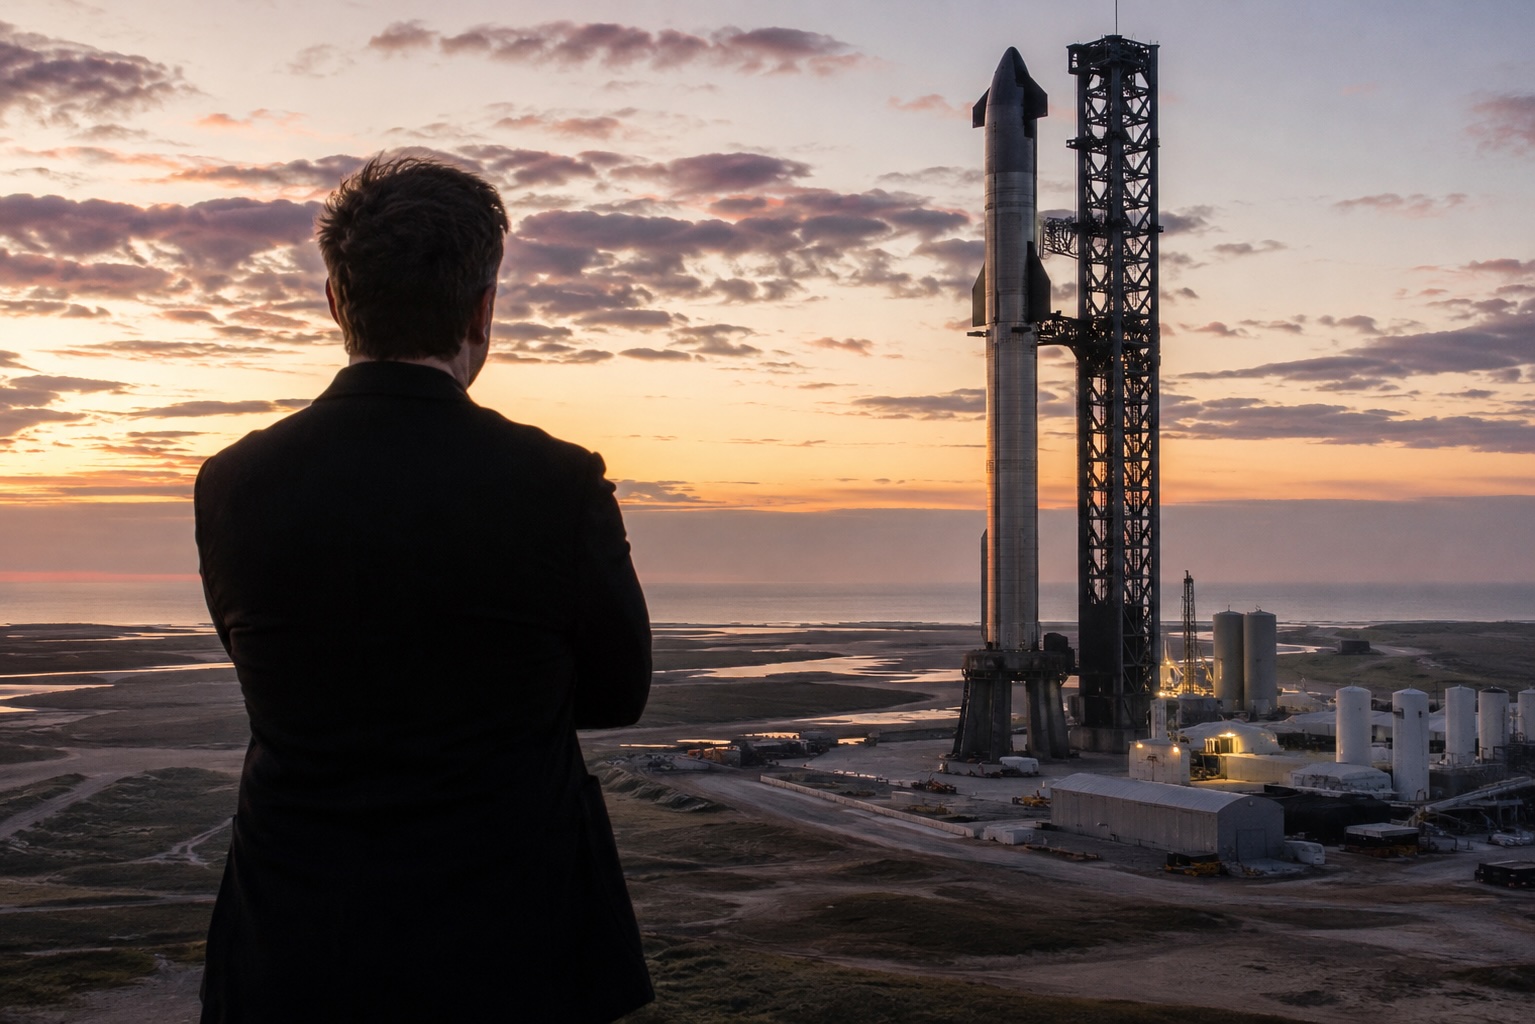
Elon Musk confirmed Tuesday that Tesla and SpaceX have each formed special committees of independent directors to study a possible merger, the first formal step toward combining the two companies after months of speculation.
Musk made the disclosure during SpaceX’s third quarter earnings call. “Both SpaceX and Tesla have formed special committees to discuss this idea at the request of shareholders,” he said. “Because I’m a conflicted party, I can’t actually be in the discussions of the special committees.” He described the setup as “an odd kabuki dance where two groups of people are talking and I can’t be in the conversation.”
Musk did not hide where he stands. “Do I think it would be a good idea? Yes,” he said, pointing to shared work on super intelligence software, chip design, the Terafab facility in Austin, robotics, mass to orbit and connectivity. “I do think there’s a lot of merit to combining the companies as we are pretty much in the super intelligence singularity.”
He also tried to cool expectations. The committees have not agreed on terms for any transaction, and Musk said assuming a merger is a certainty “would be overstating it.” Any deal would go to shareholders, and on the Tesla side it would need approval from 50 percent of all outstanding shares, not just the shares that are voted. Musk called that “quite a high hurdle.”
That bar has tripped Tesla up before. The company’s 2025 attempt to declassify its board won support from only 39.4 percent of outstanding shares and failed. Musk’s own voting stake sits near 20 percent after he exercised his 2018 options in June, so a deal would need broad backing from institutions and a retail base that often leaves votes uncast.
Timing is another open question. Tesla filed its proxy statement Monday for its December 3 annual meeting, and the ballot has only three items: director elections for Musk, Robyn Denholm and JB Straubel, a say on pay vote and auditor ratification. Barclays analyst Dan Levy had argued that an announcement would need to land by late October or early November to make the annual meeting, as Teslarati noted in its SpaceX earnings preview. With no terms agreed, any vote would likely require its own special meeting.
Elon Musk gives his most telling Tesla-SpaceX merger conversation yet
Musk has been edging toward this for weeks. At the All-In Summit in September, he asked “who can imagine what action one might take when there’s so much close collaboration,” Teslarati reported. Last week’s Roadster unveil, built around SpaceX derived cold gas thrusters, pushed the talk further. The two companies already share the Terafab chip project, and Tesla holds a small SpaceX stake that came from its earlier investment in xAI.
SpaceX brought strong numbers to the conversation. It reported Q3 revenue of $14.58 billion, up 161 percent year over year, with its Super Intelligence segment now its largest at $7.56 billion. A higher SpaceX valuation would shape any exchange ratio Tesla holders are offered.
Tesla reports its own third quarter results after the close on Wednesday, October 21. Investors had already ranked merger timing among the top retail questions for SpaceX’s call, and the committees will almost certainly come up again on Tesla’s.

Tesla reports Q3 Earnings today: here’s what to expect

SpaceX confirms Starship 15 launch window with massive ambitions

SpaceX stock gets a slew of price target boosts after bullish earnings call

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


