Investor's Corner
The epic battle between Elon Musk and the Tesla haters

In a fascinating article in Institutional Investor, Michelle Celarier writes that Tesla [NASDAQ: TSLA] is: “the biggest short in the U.S. market; about 27 percent of Tesla’s free float is short, for a value as high as $10 billion” according to S3 Analytics, a firm that tracks short sales. That said, “the stock has soared more than 1,300 percent since Tesla went public in 2010. It is the first automaker to go public since Ford in 1956, making it one of the darlings of the post-financial-crash bull market.”
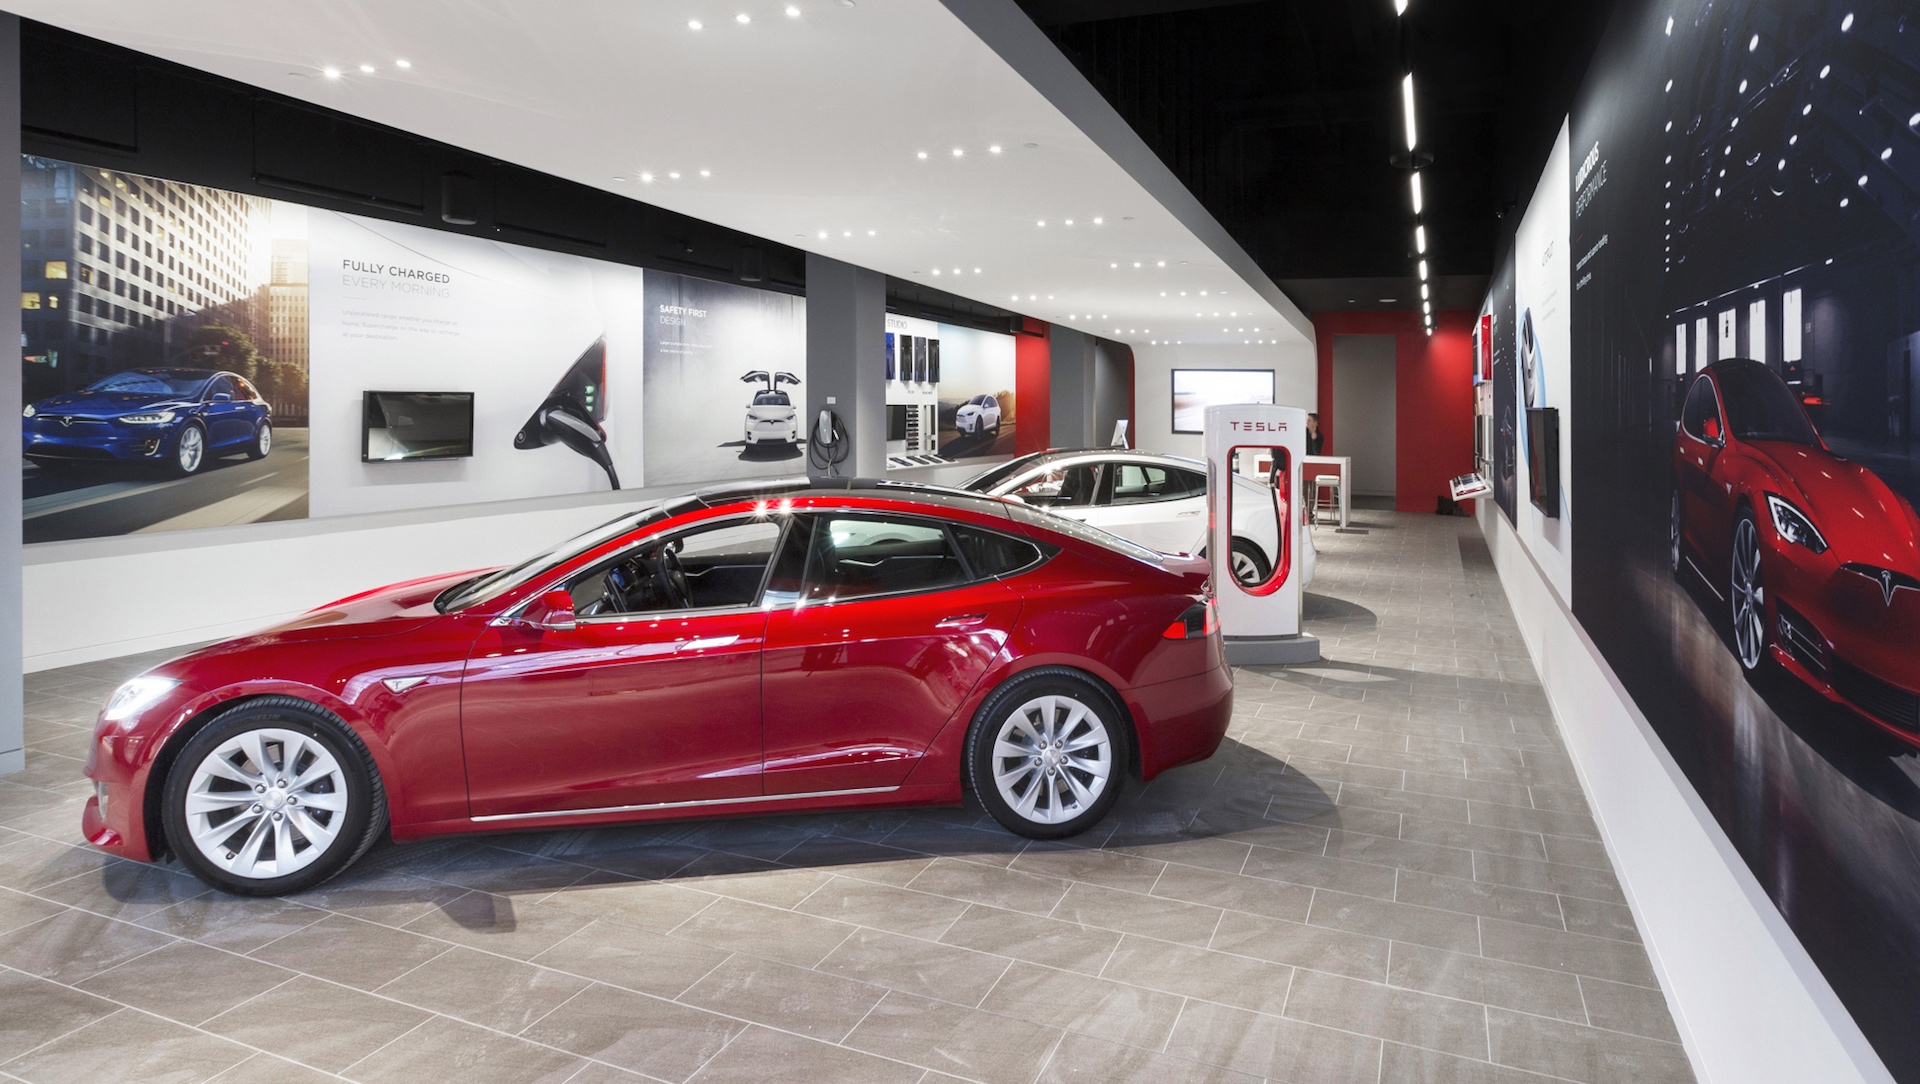
Photo credit: Tesla
It turns out that one of the most notorious Tesla shorts is Mark Spiegel. And Spiegel hasn’t even driven a Tesla yet. He says, “I’m more into sports cars.” According to Celarier, “Spiegel has become something of a zealot on Tesla. His small hedge fund, Stanphyl Capital Management, runs a mere $8.5 million, given that it was down 20 percent this year through August. That’s largely due to his short of Tesla, which had gained 74 percent this year, making it the worst-performing short of the year.”
However, there are bigger players out there shorting Tesla. Celarier reports that: “Everyone who’s anyone in Wall Street’s small and clubby world of short sellers has been short Tesla at one point or another… In the past, some of them also shorted Google and Amazon — other high flyers who weren’t making a profit — and somewhat sheepishly [now] admit they were wrong. Clearly, these guys are not dreamers from California’s La La Land, and Musk’s grand plans and his ‘save the world’ ethos can elicit a few eye rolls.”
Another well-known Tesla short, James Chanos of Kynikos Associates, “has been railing against Tesla for at least two years on CNBC and at numerous conferences. He has gone so far as to call Tesla a cult.” Speaking of Tesla’s CEO Elon Musk, Chanos proclaims, “People want to believe he’s some sort of visionary… In a milieu of boring people, they think he is changing the world. He’s not boring. He’s somebody they can attach their hopes and dreams to.”
Photo credit: David Paul Morris/Bloomberg
So why does Tesla attract so many arguments on Wall Street? On the one hand, “Looking at its balance sheet, Tesla is [considered] the perfect short. But its pioneering status in an industry facing wrenching technological upheaval, and its charismatic CEO, has won it legions of admirers and turned it into a battleground stock. Sure, Tesla’s lofty stock price makes it a risky buy — but also a perilous short.”
Anger and hope permeate both camps of investors. “Short sellers berate Tesla investors as momentum chasers, tree-huggers, or simply Elon Musk groupies, but these investors have bought into a vision that has already made great leaps toward building a sustainable energy ecosystem — a costly endeavor that has no shortage of well-heeled enemies.”
And while an army of short sellers persist, plenty of Wall Street’s power players remain steadfast Tesla longs: “The biggest holders, aside from Musk, are mutual funds like Fidelity Investments, which has owned the stock since the IPO. With a current 12.8 percent stake (down from a high of 15 percent), the mutual fund giant is the largest institutional investor in Tesla, and portfolio manager Kyle Weaver says Fidelity has a long-term perspective on the company that is playing out largely as expected.”
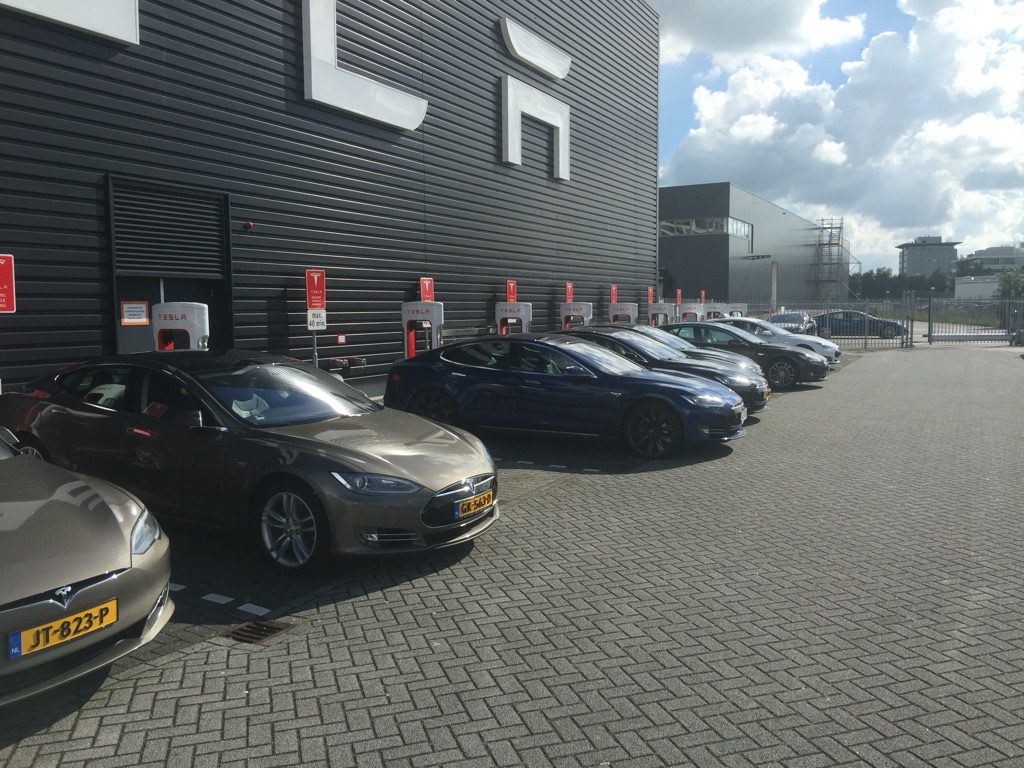
Tesla fleet lined up outside of the service center in Amsterdam [Photo credit: Teslarati App]
“It was the worst short I’ve ever had,” says Whitney Tilson, managing partner of Kase Capital Management, who was short when the stock went from $35 to $205. Last month, Tilson told investors he’s shutting down his funds due to poor performance. Tilson explains, “I can do the numbers and see how much money the company is losing, but you’re short an incredibly maniacally driven CEO, with maniacally driven engineers assaulting the world’s largest industry. If they succeed, Tesla could be a $400 billion market cap company.”“The internal combustion engine is toast long term. It’s game over. The costs of making an internal combustion engine do not go down, while the cost of battery technology has gone down every year,” says Fidelity’s Weaver. “The secular trends that will drive Tesla’s fundamentals are a decades-long trend.” He also applauds Tesla’s environmental mission, “I don’t want to bet against that in an emotional sense.”
Musk is also not afraid to openly attack Wall Street’s short sellers. Let’s not forget, “Musk, who has talked about being bullied as a child, seems to delight in taunting his tormentors. In 2013 he gloated on Twitter, ‘Seems to be some stormy weather over in Shortville these days,’” and once cautioned short sellers that a “tsunami of hurt” was coming in a televised interview.
Celarier writes, “To be sure, a mania surrounds Tesla… [and] betting against Musk is a tough proposition. Tesla has already survived near-bankruptcy events, and Musk has plenty of friends in tech companies with much higher valuations, like Larry Page at Google, that could afford to partner with Tesla or take it over. (Google had struck a handshake deal to buy Tesla during a near-death moment in 2013, according to Vance’s biography.)”
There’s also massive opportunity for Tesla in China: “Earlier this year, China’s Tencent Holdings took a 5 percent stake in Tesla. China is proposing to mandate a zero-emissions standard in 12 percent of new cars by 2020 and is considering letting wholly owned foreign electric-car companies operate there. The Chinese market is expected to be huge, and Tesla is charging ahead there. It is already building a new supercharger network in the country and plans to both build and sell cars there.”
Such realities make shorting Tesla, for all its financial shortcomings, a difficult call. As Tilson puts it, “I don’t want to be short open-ended situations. The tail risk is just too high.”
===
Note: Article by Matt Pressman, originally published on evannex.com
Source: Institutional Investor

Investor's Corner
Tesla’s flying Roadster just revealed something bigger than the car
Analysts say the Roadster demo puts a Tesla and SpaceX merger back on the table.

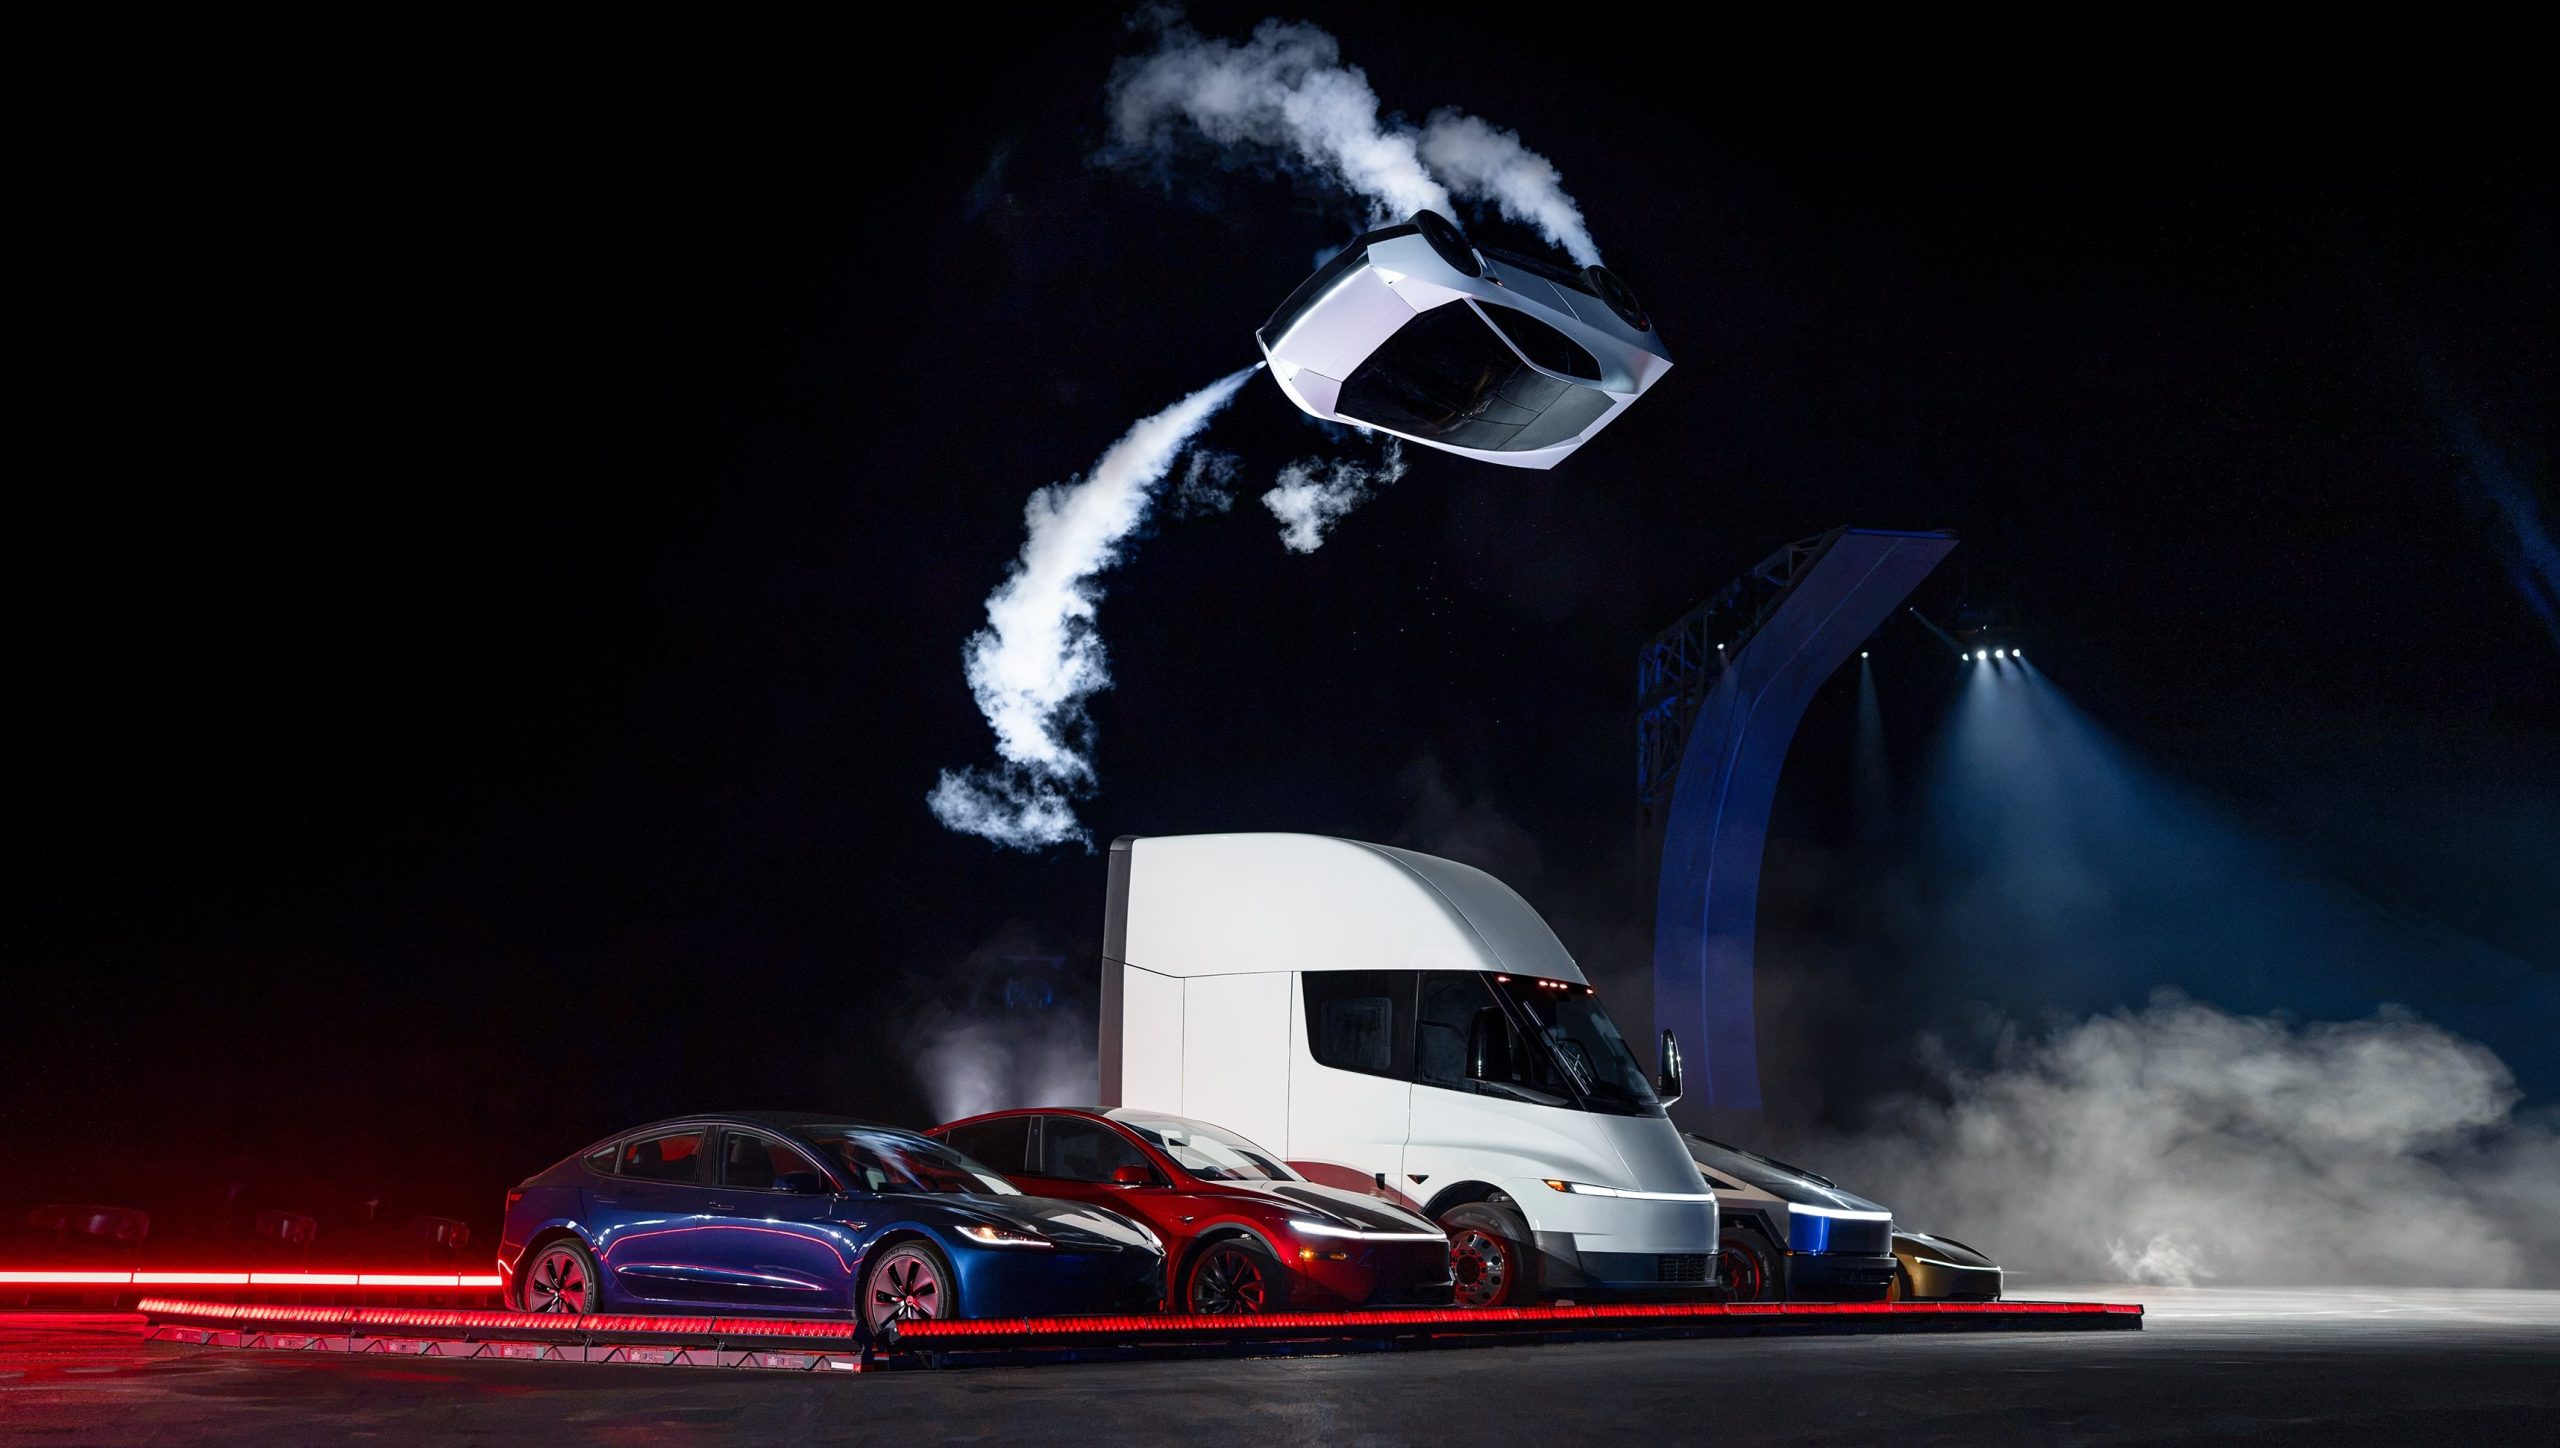
The Roadster unveiling near Waco ended Thursday night, and by Friday morning much of the investor reaction had less to do with the car than with who owns the rocket technology inside it.
Wedbush analyst Dan Ives said the event “puts the Tesla/SpaceX relationship on the table in a tangible way,” pointing to the propulsion, pressure vessel and control hardware sitting on a Tesla product. Gene Munster of Deepwater Asset Management called the demo “a ridiculous display of engineering” with “no commercial value” beyond embarrassing traditional automakers, though he said it showed Musk wants the two companies together.
The more specific forecast came a day earlier from Barclays. Analyst Dan Levy told clients a deal could be announced before Tesla’s annual meeting, which must happen by December 6, and that an announcement in late October or early November could make shareholder approval harder. Barclays expects SpaceX to be the buyer in an all stock deal, with Tesla holders receiving SpaceX shares at a premium, based on market values of roughly $2.1 trillion for SpaceX and $1.5 trillion for Tesla. If nothing lands around the meeting, the bank still sees an announcement within 6 to 12 months.
The Roadster demo just added more weight to merger speculations. Tesla’s demo used cold gas thrusters and pressure tanks of the kind SpaceX uses on Falcon 9, and Musk described the car as a collaboration between Tesla and SpaceX engineers, as we mentioned in our breakdown of the three Roadster configurations.
Musk has not publicly addressed a deal since the event, as far as we have seen. His most direct answer remains the one he gave at the All In Summit, when he said that with so much collaboration, “who can imagine what action one might take” without ruling anything out. Ives has held to a 2027 timeline since his March note, and Musk pushed back on the China piece of the speculation when ARK floated a year end announcement in August.
The next test is Tesla’s third quarter earnings call on October 21. However, we recall in July that Musk told analysts, “we can’t talk about combining companies and that kind of thing on an earnings call,” so a clear answer wouldn’t be expected.
Elon Musk
Elon Musk breaks his silence on the Starlink impact to Ukraine drones
Musk says the US military and president set Starshield limits, not SpaceX, amid Ukraine complaints.
Elon Musk says the speed limit cutting out Ukraine’s military Starlink terminals is not SpaceX’s decision. In a post on X Wednesday, Musk wrote that “Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.” He added that Starlink is a commercial service limited to civilian or defensive activities and “cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.”
He was replying to Mykhailo Fedorov, Ukraine’s former defense minister, who had thanked Musk for restoring connectivity at speeds up to 160 km/h and said removing the Starshield limit entirely is “now critical for Ukraine’s defense.”
Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.
Starlink is a commercial service owned and controlled by SpaceX. Usage of Starlink is limited to civilian or defensive activities and cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.
— Elon Musk (@elonmusk) October 14, 2026
The complaint started Tuesday night, when Ukrainian officials said military terminals began losing service above roughly 100 mph. Presidential adviser Serhiy Beskrestnov said the defense forces got no warning and several missions were disrupted, as Teslarati reported earlier Wednesday. The 7th Rapid Reaction Corps told Reuters connections dropped for 10 to 20 seconds at speeds well below the limit, which made drones harder to control. Poland’s foreign minister, Radoslaw Sikorski, asked Musk on X whether he is “playing politics with your products again.”
That is why the Starlink and Starshield distinction matters. SpaceX introduced Starshield in 2022 as the government version of Starlink, with an initial focus on Earth observation, communications and hosted payloads. It won a Space Force contract in 2023 with a $70 million ceiling. In December 2024, the Pentagon moved Ukraine’s terminals onto Starshield, covering about 3,000 units across two contracts. Ukraine’s military connections therefore run through a service that Musk now says sits under Washington’s control.
While Musk’s post describes who holds authority, it does not infer that anyone ordered the limit, and neither SpaceX nor the US government has confirmed who set it. Ukrainian officials have pointed to the timing, which follows President Trump’s push for an energy ceasefire and Musk’s Saturday post that “Zelensky has gone too far.” The BBC noted Trump denied threatening to restrict intelligence sharing with Kyiv, and no evidence has been presented that Washington requested the cap.
The episode also revives a promise from 2025. After Poland accused him of threatening Ukraine’s access, Musk said Starlink “will never turn off its terminals” and would not be used as a bargaining chip. Poland has since supplied more than 29,000 terminals to Ukraine. Teslarati also covered Kyiv’s search for Starlink alternatives in 2025, and the latest dispute gives that search new urgency.
Investor's Corner
Tesla opens the Q&A for its biggest earnings call yet
Tesla opens its Q3 earnings Q&A, and Cybercab, Robotaxi, Optimus and regulators loom over October 21.
Tesla has opened its shareholder question portal for the Q3 2026 earnings call, with the Say Q&A page already listing questions. Investors have until 4:00 p.m. EDT on October 20 to submit and vote on what management should answer.
The call is set for Wednesday, October 21. Tesla will post results after the market closes, with a live webcast at 4:30 p.m. CT, or 5:30 p.m. ET, through its investor relations site.
Say ranks questions by the number of shares behind the votes, which gives institutional holders extra weight over the retail crowd.
Ahead of Q2, retail investors asked why Robotaxi growth had stalled, when Cybercab would start customer rides, and where the Optimus Gen 3 ramp stood, while an institutional holder asked how Tesla and SpaceX would split Terafab duties. Cybercab has since answered one of those. Tesla said last week it has 300 plus Cybercabs serving Austin, up eightfold in 30 days, with Dallas named as the next city. The questions now are likely to move from when to how fast.
There is also a regulatory question hanging over the call. NHTSA has demanded sworn answers on how the pedal free Cybercab was certified against federal safety standards, with responses due October 30, nine days after the call. Whether an analyst raises it live is unknown, but it is the kind of exposure that tends to find its way into a Q&A.
The numbers will not be the main draw. Tesla already reported 486,532 deliveries and 13.7 GWh of storage for the quarter. Consensus sits around 43 to 45 cents per share on roughly $27.8 billion in revenue, according to Zacks, after a Q2 report that missed on EPS. Goldman Sachs, which holds a Neutral rating and a $360 target, argues the outlook for Robotaxi, FSD and Optimus will matter more to the stock than the quarter itself.
The call also lands six days after the rescheduled Roadster event, which Tesla will stream on X on Thursday, October 15, at 7:55 p.m. CT. If the Roadster shows up with a production date or a SpaceX thruster package, expect it to climb the voting list before the deadline.

Tesla’s flying Roadster just revealed something bigger than the car

How Tesla’s Roadster fan system and thrusters are built to dominate the corners

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Elon Musk’s Boring Company lands a new Middle East deal, and Nashville is about to get faster


