Investor's Corner
Tesla’s Q3 2018 earnings call: What we expect to see

In a rather surprising announcement on Monday, Tesla revealed that it was releasing its Q3 2018 earnings report after the closing bell on Wednesday. The earlier-than-expected earnings call appears to have fostered positive sentiments among the company’s investors, and coupled with a change of heart from a staunch TSLA short-seller, Tesla stock (NASDAQ:TSLA) saw a 12.72% rise on Tuesday, bringing the company within reach of the $300-per-share-mark once more.
While Tesla was able to hit its production and delivery targets in Q3, questions remain about whether the company was able to turn a profit as promised by CEO Elon Musk. That said, Wall Street analysts polled by FactSet expect Tesla to post revenue of $6.05 billion and a GAAP EPS of -$0.95, partly due to a major increase in Model 3 deliveries in the third quarter. Non-GAAP EPS consensus is a more favorable -$0.03.
With these in mind, here are some pertinent updates and information we are expecting to see in Tesla’s Q3 2018 earnings call.
Profitability and Cash-Flow Updates
Earlier this year, Elon Musk boldly declared that Tesla would be profitable and cash-flow positive in the second half of the year. The company went through great lengths in its efforts to achieve this ambitious target, from laying off 9% of its employees last June to allowing owners to help out the company deliver as many vehicles as possible in the final weeks of the third quarter.
Wall Street analysts polled by FactSet expect the company to report a modest amount of positive free cash flow for the third and fourth quarter. Non-GAAP EPS is also expected to improve to $0.78 in Q4. In the upcoming earnings call, Tesla would likely offer some updates on its profit outlook in its shareholder letter.
Model 3 Production and Margins
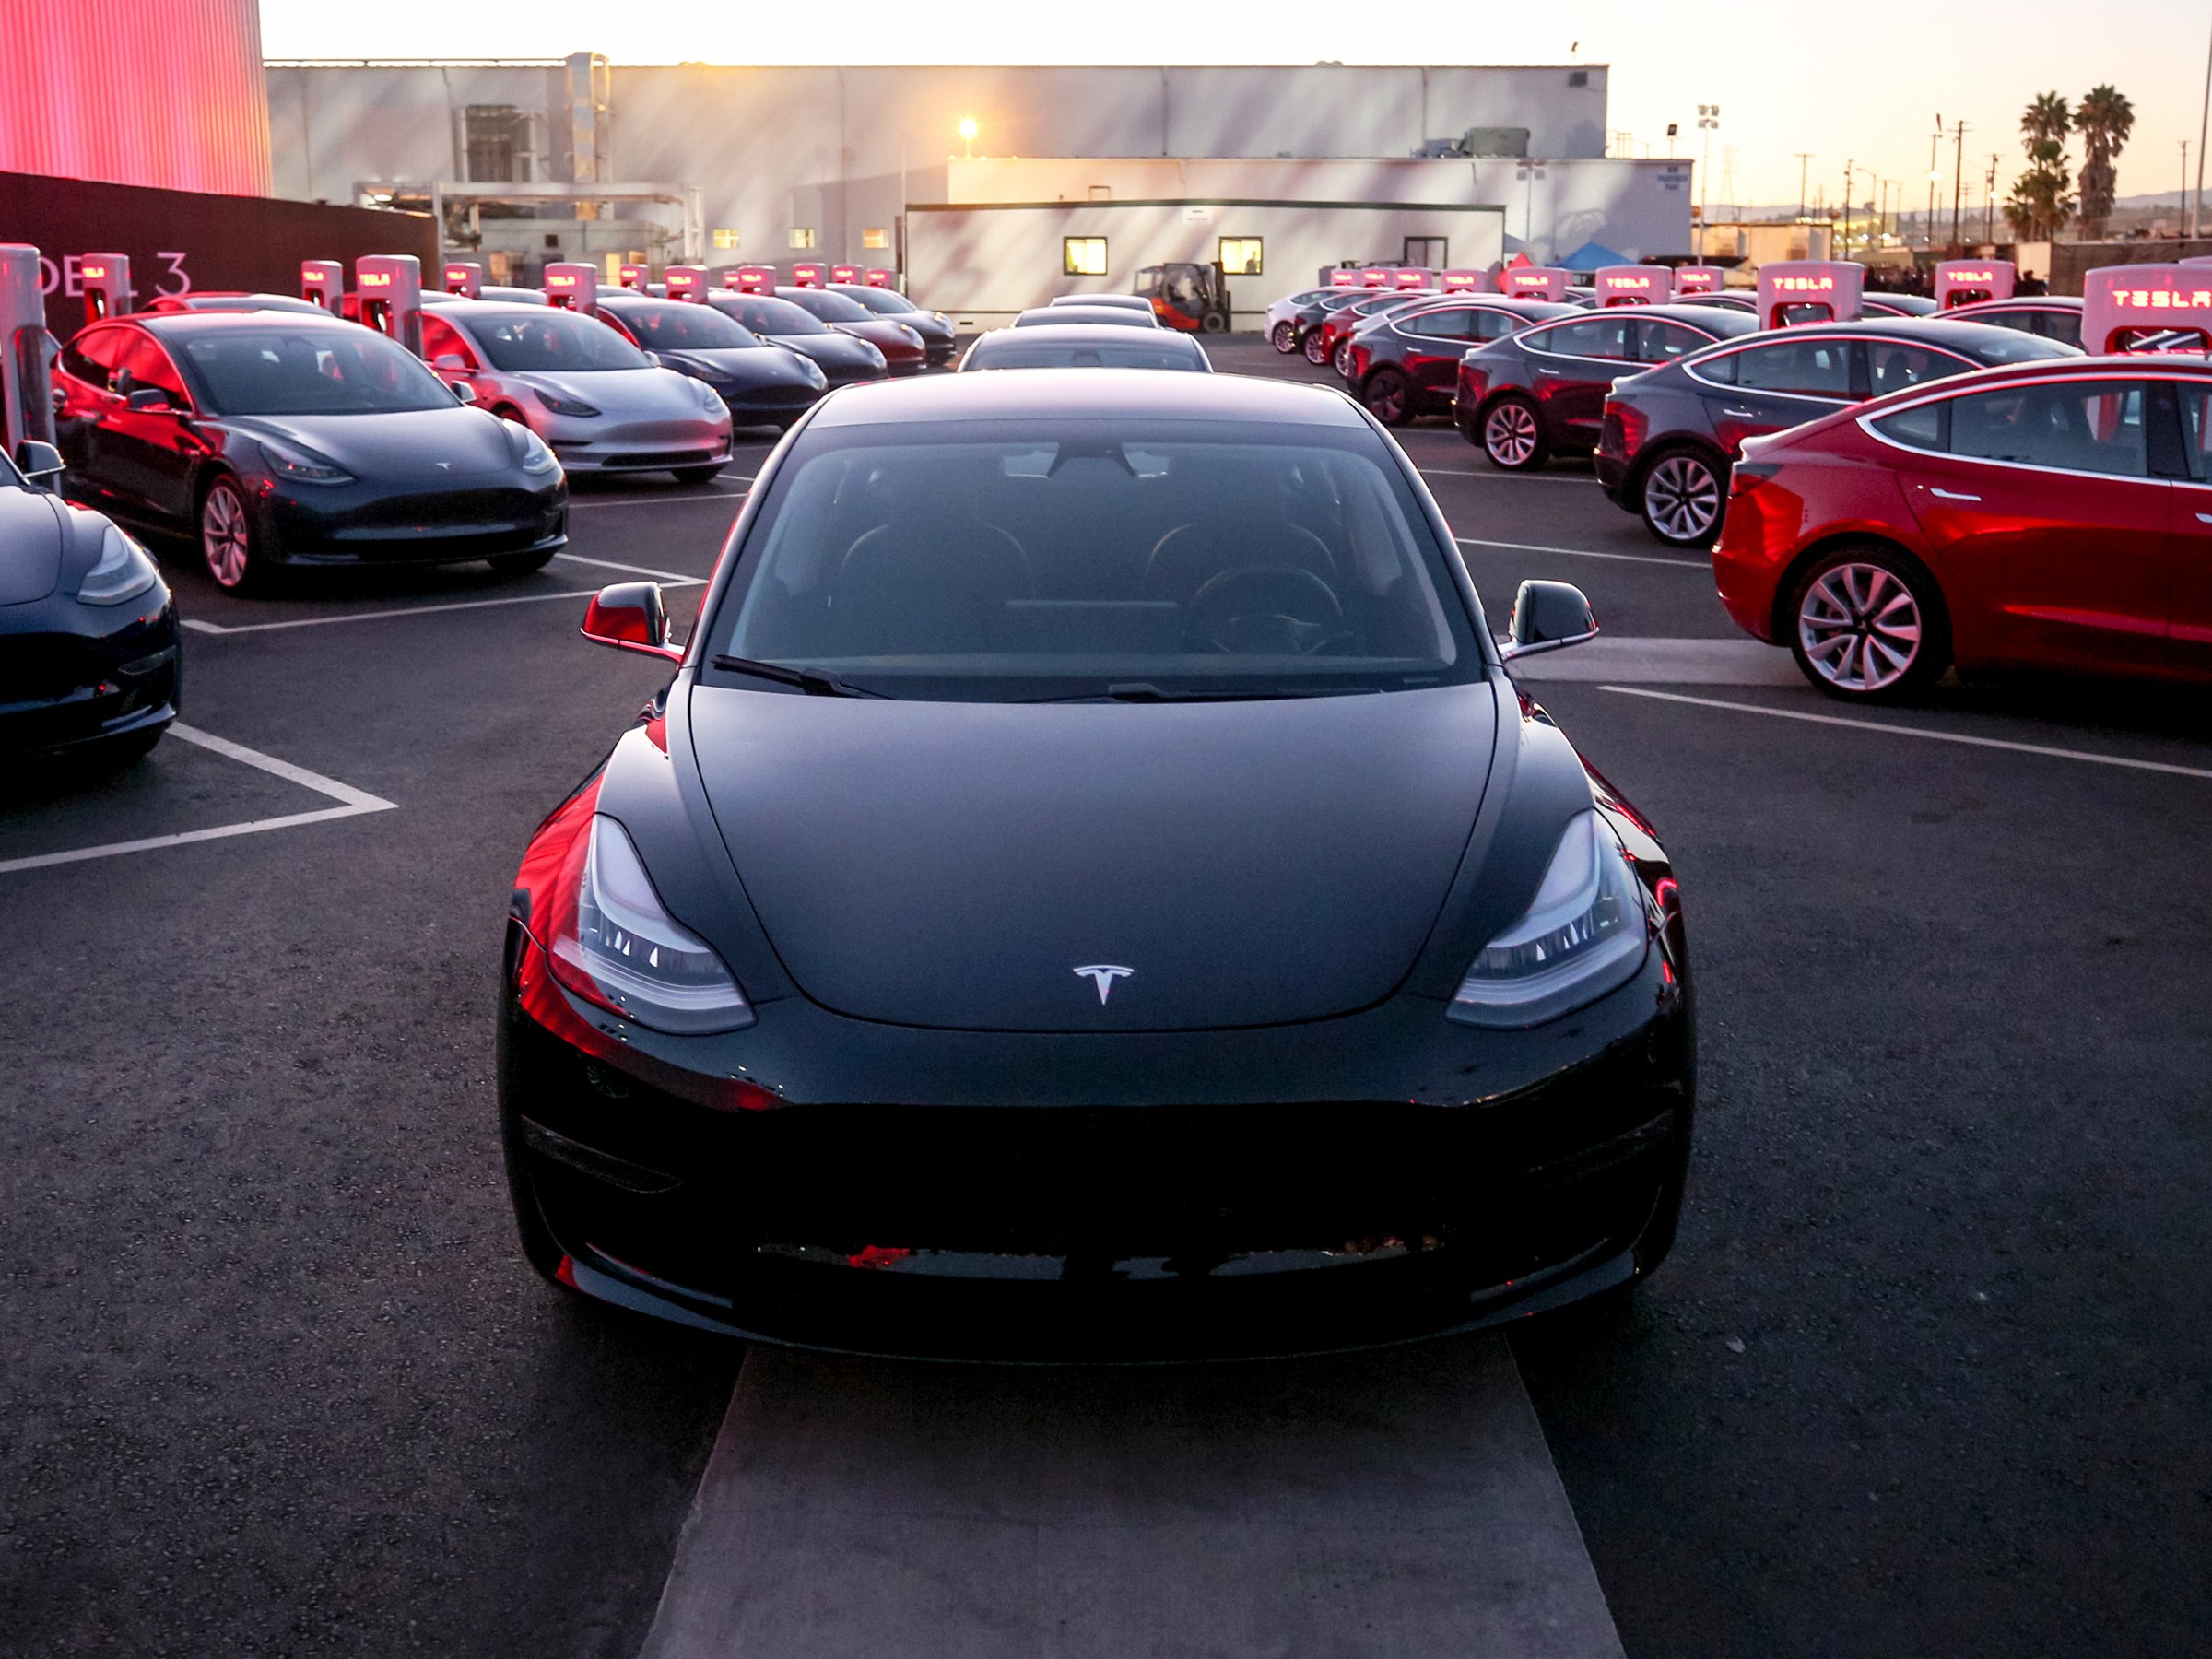
In Tesla’s Q2 shareholder letter, the company stated that it is aiming to grow Model 3 production to 10,000 units per week as soon as it can. Tesla also aimed to produce the Model 3 at a rate of 6,000 per week by late August — a goal that the company was unable to attain. In today’s earnings call, Tesla is expected to provide an updated guidance for the Model 3 ramp.
Back in August, Tesla noted that it expects Model 3 gross margins (GM) to improve to 15% and 20% in Q4. These figures are a bit more conservative than Tesla’s initial forecasts for the vehicle, which estimated gross margins to be at 25% when production is stabilized at 5,000 units per week. The upcoming earnings call should provide some guidance as to where the Model 3’s gross margins are at this point, and where it could be at the end of Q4.
The $35,000 base Model 3 and the Model Y
Tesla has pretty much hit its stride with the production of the Long Range RWD, Dual Motor AWD, and Dual Motor Performance Model 3. Earlier this month, the company also revealed the Mid Range RWD Model 3, a vehicle that places the electric car’s price closer to Elon Musk’s $35,000 starting price for the electric sedan. Considering that the company has left its self-imposed production hell, the time might be right for Tesla to provide some updated guidance as to when the long-promised $35,000 Model 3 would enter production.
Updates on other upcoming vehicles are also expected, particularly the next car in the company’s lineup — the Model Y. Considering that Elon Musk has teased an unveiling sometime early next year for the crossover SUV, there is a good chance that the upcoming Q3 2018 earnings call would provide a more concrete date for the highly-anticipated vehicle’s unveiling.
Tesla Energy Updates
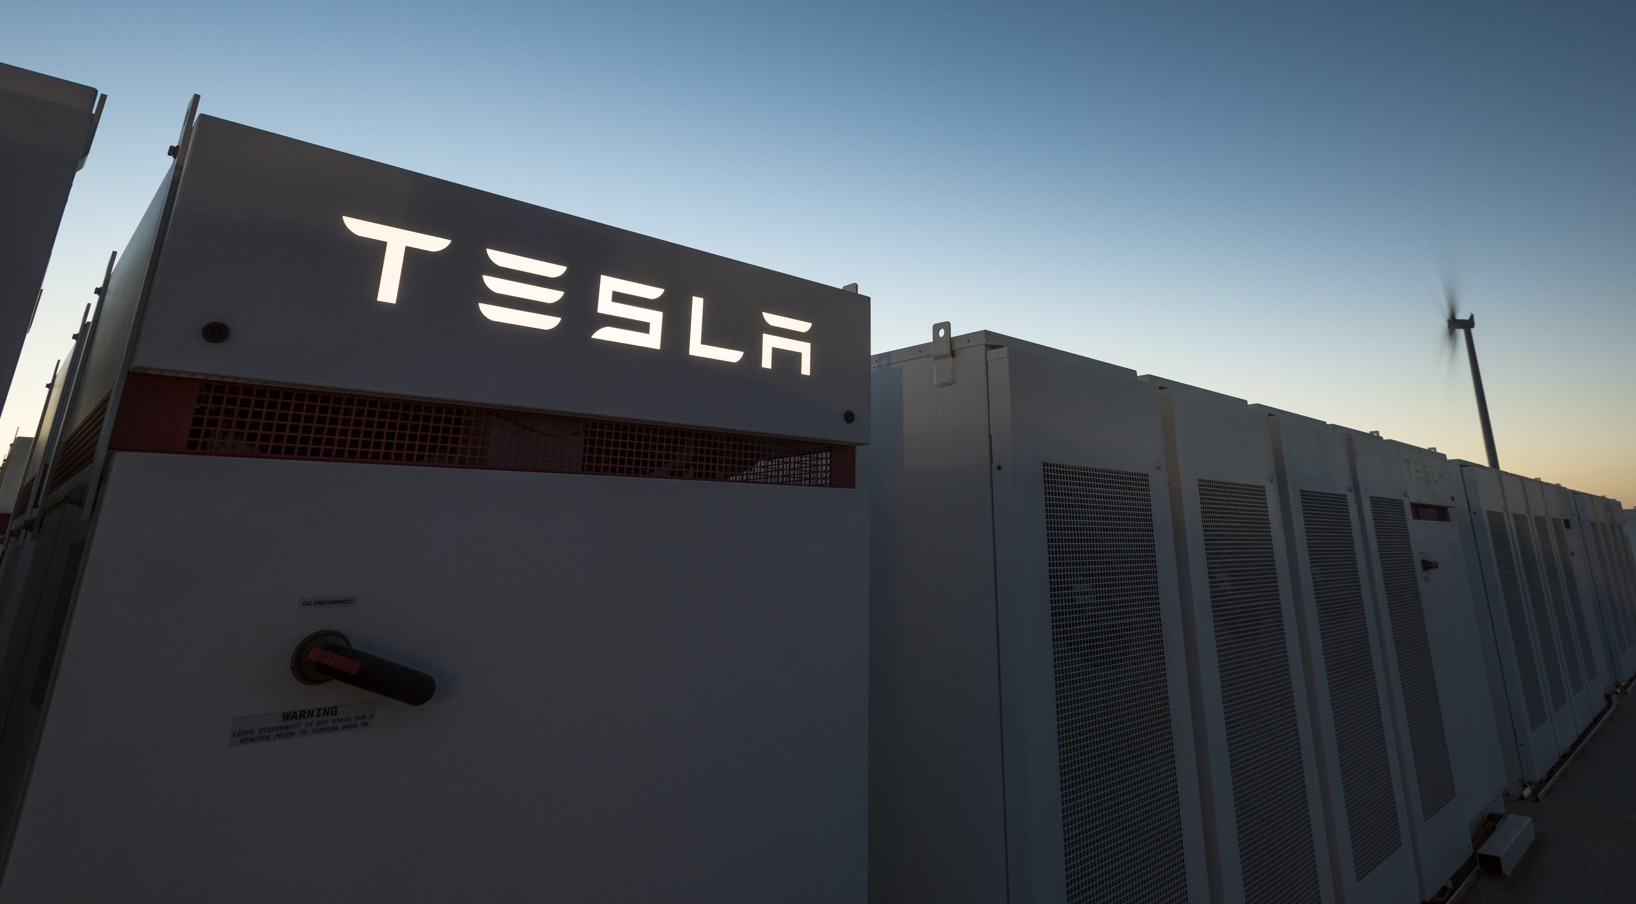
Tesla Energy does not attract as many headlines as the company’s electric car business. Despite this, the company’s executives including CEO Elon Musk and CTO JB Straubel have both noted that Tesla’s energy storage business would likely match the company’s electric car division in the near future. This was highlighted recently by legendary investor Ron Baron, who stated that Tesla could become a $1 trillion company by 2030, comprised of a $500 billion electric car division and a $500 billion battery storage business.
Wall Street analysts’ consensus for Tesla Energy estimates the business to post revenue of $377 million (up 19%), and a gross profit of just $20 million. Announcements on upcoming battery storage projects are also expected to be discussed in the upcoming call.
Tesla’s New Chairman
As part of his settlement with the Securities and Exchange Commission, Elon Musk agreed to step down as Tesla’s Chairman. Reports eventually emerged that board member James Murdoch was in line to take on Musk’s role. These reports were eventually debunked by Elon Musk himself on Twitter, though, leaving Tesla’s next chairman still a large question mark.
On Wednesday’s earnings call, expectations are high that the company would provide some updates on its search for a new Chairman to replace Elon Musk. Other terms of the CEO’s settlement with the SEC, particularly the addition of two new independent board members, would likely be discussed as well.
Tesla’s Q3 Update letter would be posted on Tesla’s Investor Relations website after markets close today. At 3:30 pm Pacific Time (6:30 pm Eastern Time), Tesla would start its Q3 earnings call.

Elon Musk
SpaceX’s Anthropic deal has a catch, and Elon Musk just addressed it
Elon Musk says SpaceX’s Anthropic compute deal cuts both ways after Chamath floats higher prices.

Elon Musk pushed back on Sunday against the idea that SpaceX’s compute contract with Anthropic is a one way bet, after venture capitalist Chamath Palihapitiya argued the company could use a termination clause to charge the AI lab far more.
“It works both ways, of course. If compute becomes plentiful and cheap, SpaceX revenue will drop. No crying in the casino for either party,” Musk wrote on X Sunday evening, replying to a clip of Palihapitiya’s comments shared by AI commentator Rohan Paul.
On the All-In podcast released Sunday, Palihapitiya said either side can walk away from the agreement on 90 days’ notice. If data center supply tightens, he argued, SpaceX could exercise that option and bring the contract back at two to three times the current price, and Anthropic would have little choice but to accept. He called it “the kingmaking move,” according to BigGo Finance.
The clause itself is not new. SpaceX disclosed in its IPO filings in May that Anthropic would pay $1.25 billion per month for dedicated capacity at its Colossus clusters through May 2029, nearly $45 billion in total, with both companies able to terminate on 90 days’ notice, as Teslarati reported at the time. SpaceX’s later compute deals with Google and Reflection AI carry similar exit terms.
What has changed is the political backdrop. Palihapitiya’s thesis rests on incoming Democratic governors pulling tax incentives for data centers and slowing new construction. In Texas, Gov.-elect Gina Hinojosa campaigned on a moratorium on new data center approvals, and Deutsche Bank analysts warned last week that SpaceX’s Texas compute capacity could face delays. SpaceX and Tesla shares both fell after the midterm results.
A slowdown would favor companies that already own capacity. SpaceX acquired xAI in February and has been renting data centers to outside AI labs before the space is needed for Grok. At the Baron Investment Conference on Friday, Musk said SpaceX was “getting 50 billion a year for 35 billion dollar investments” and that it can bring a data center online in eight or nine months, compared to two and a half years for competitors. He also said SpaceX is tracking toward an annualized revenue rate above $100 billion in December, with a “best guess” of $500 billion by December 2027.
Musk’s reply points to the other side of the clause. Anthropic has signed large compute agreements with Amazon, Google and Microsoft, and if that capacity comes online faster than new construction slows, the AI lab would have its own leverage to renegotiate or leave. Musk has called Anthropic “obviously currently the leader in AI,” and it remains one of SpaceX’s largest compute customers.
SpaceX shares rose more than 2 percent in overnight trading late Sunday after closing Friday at $134.27, according to Stocktwits.

Tesla and SpaceX shares fell on Wednesday after Democrats swept both chambers of Congress. The decline stood out as broader market securities recovered and turned positive, while both of Musk’s publicly traded companies lagged.
CEO Elon Musk already joked about the unsuccessful campaigning for the Republicans, but now the new party will make pretty drastic changes to how it handles Tesla and SpaceX, and those companies will adjust their outlook.
Let’s take a deeper look.
Tesla ($TSLA)
Tesla shares traded lower during the regular session after Democrats secured both the House and Senate. The stock was down 2.32 percent at around 1:45 p.m. on the East Coast, trading at around $389.30.
The pressure is tied to more than the raw scale of Musk’s political spending, estimated at $450–474 million this cycle with roughly $224 million directed at Texas. In that state, Tesla now faces a Democratic governor and a Democratic senator after Gina Hinojosa unseated Greg Abbott and James Talarico defeated Ken Paxton.
The Austin Gigafactory, Robotaxi pilot programs in multiple Texas cities, and any related AI compute expansion sit under a new state executive who campaigned against certain corporate subsidies and floated a moratorium on new data-center construction.
Federally, Democratic control of key committees opens the door to deeper examination of Tesla’s autonomous-driving safety record, federal energy-storage and manufacturing incentives, and the national-security implications of any combination with SpaceX.
Investors are also weighing whether the company’s historically close alignment with the prior Republican leadership will invite slower permitting, additional hearings, or tighter rules on Full Self-Driving deployment.
For Tesla, the political shift adds near-term friction around state permitting and federal regulatory approvals for autonomy and energy storage. A potential merger with SpaceX may face slower review even if it proceeds.
Core growth drivers such as vehicle deliveries, energy deployments, and robotaxi rollout remain intact, yet the stock now carries a higher political-risk premium that could weigh on valuation until the company demonstrates workable relationships with the new Texas leadership and congressional majorities.
SpaceX ($SPCX)
SpaceX shares also declined in live trading on November 4 following the Democratic midterm sweep. The stock traded at $134.97, down 4.49 percent. The drop occurred even as broader indexes stabilized, highlighting a company-specific reaction to the election outcome.
Musk’s large contributions, concentrated in Texas races that both companies lost, place SpaceX’s Starbase launch facility and headquarters under a new Democratic governor.
At the federal level, Democratic control of Congress enables greater scrutiny of NASA, the Department of Defense, and other contracts that support a meaningful share of revenue, along with reviews of Starlink national-security uses and any Tesla merger. Analysts have noted that empowered committees can hold hearings and request documents on these relationships.
For SpaceX, the results raise the risk of delayed contract awards, higher compliance costs, and tighter constraints on AI and satellite infrastructure expansion, particularly in Texas where a data-center moratorium has been discussed.
A merger with Tesla could encounter political friction that slows integration of launch, connectivity, and autonomy capabilities.
While Starlink growth and launch cadence continue as primary drivers, the company faces a more contested path for federal funding and state-level operations, requiring management to rebuild ties with the new congressional majorities and Texas leadership to limit the overhang.
Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.
Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.

SpaceX’s Anthropic deal has a catch, and Elon Musk just addressed it

Elon Musk spotlights the Starlink rescue that got through where no cell tower could


