
New Street Research managing partner Pierre Ferragu recently explained why Tesla’s (NASDAQ:TSLA) EV credits is only icing on the cake for the electric car maker. Tesla reported a revenue of $8.771 billion with a net income of $331 million in Q3, with regulatory credits accounting for $397 million of the EV maker’s earnings.
When asked about how regulatory credits have boosted Tesla’s numbers this year, Ferragu told Fox Business that the EV credits aren’t a big part of the electric car maker’s future valuation at all. This is partly due to regulatory credits being short-term, and Tesla’s vehicle margins.
“Why are you looking at profits of this year? You know Tesla is trading on maybe, like over 100x that, more than 100x that, so that’s not reason to drive our valuation of TSLA. What really matters is how much profit Tesla makes in 2025, in 2030. We’ve had a string of conversations about that,” said Ferragu.
He explained his stance further, saying: “So, to give you a sense of that, in 2025, I have Tesla making $16 of earnings per share just out of the auto business. And in that, there’s absolutely no credit revenues. We don’t have credit revenues in our model. Credit revenues are very short-term, have a very short duration, so you arrive at about $1.5 billion in pure profit this year. So that’s like free money Tesla gets and Tesla will be able to reinvest in their business.”
A big portion of Tesla’s EV credits come from its Fiat pooling deal which was estimated to be worth $1.8 billion through 2023 by Baird analyst Ben Kallo. Recently, Honda joined Tesla’s pooling deal with Fiat Chrysler Automobiles (FCA), probably increasing TSLA’s profitability with EV credits.
Many TSLA bulls, specifically retail investors who have accumulated a good number of shares over the years, agree with Ferragu’s assessment of Tesla’s use of EV credits. As TSLA Bull @stevenmarkryan explained, EV credits are more of a byproduct of Tesla doing what it is already doing. During his interview with Fox Business, Ferragu strived to explain Tesla’s profitability without EV credits on the table.
“But that money is going away relatively rapidly in the next three or four years. And that’s not part of the overall picture. What really matters today is to look at the gross margins of Tesla excluding the regulatory credits. And excluding credits, Tesla’s gross margins is about 20%, it’s a leading gross margin for a car manufacturer. And it continues to expand as the Model Y is a higher margin, the Model Y is included in the mix. That’s what really matters, and credits have nothing to blame there,” Ferragu said.
Morgan Stanley recently raised its price target for TSLA to $540. “Mine is a tad above that. It’s $578. They’re getting closer to the truth,” Ferragu commented during his interview.
In October, Ferragu released a New Street Research analysis on Tesla and set his $578 TSLA price target for the company. The analysis hinted at a decade of hyper-growth for Tesla. In it, Ferragu and his fellow analysts estimated that Tesla had an addressable market of 20 million units. The S3XY lineup directly addressed 8 million units with an additional “trading up” opportunity of 12 million units. The Cybertruck added an extra 3 million units to the equation.
Recently, Tesla joined the Zero Emission Transportation Association (ZETA) along with 28 other companies, like Rivian, Duke Energy, Seimens, and Lucid Motors. ZETA wants to reach 100% EV adoption by 2030 in the United States. In Europe, the EU Commission plans to enforce stricter emission standards that could kill the combustion engine by 2025. Other countries seem be preparing for an EV-lead auto industry as well, which could bring about Tesla’s hyper-growth in the next decade.


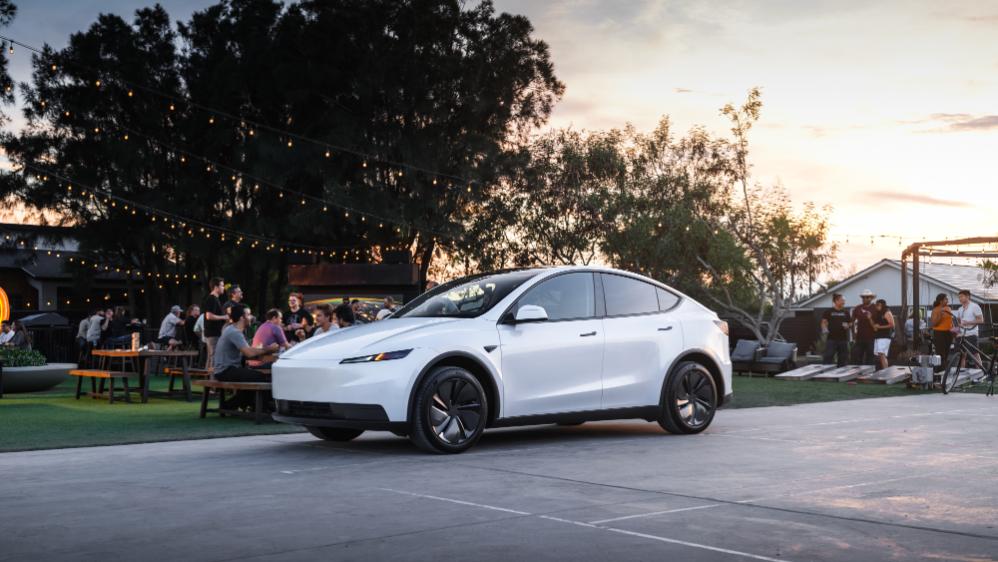
Tesla has trimmed its Model Y offerings as its Standard All-Wheel-Drive configuration has been removed from the online configurator after roughly nine months on sale. The move follows the removal of the Cybertruck, as its trims have also been minimized as that vehicle heads for total discontinuation at the end of Summer 2027.
Launched in February 2026 as a mid-tier dual-motor option between the Rear-Wheel-Drive model and the Premium trims, the Standard All-Wheel-Drive Model Y offered 294 miles of range and a 4.6-second 0-60 mph time in a stripped-down package.
🚨 Tesla has pulled the $41,990 Model Y AWD from its U.S. configurator after nine months on sale.
The cheapest AWD Model Y you can order is now the $49,990 Premium AWD, with Premium deliveries quoted for Jan–Mar 2027.
The $39,990 RWD stays, and AWD units remain in inventory. https://t.co/uROJp2lVpx
— TESLARATI (@Teslarati) November 13, 2026
With it gone, the cheapest new AWD Model Y buyers can configure is now the Premium AWD at $49,990, with estimated deliveries pushed into January–March 2027. The $39,990 rear-wheel-drive Model Y remains available for custom orders, and some AWD units are still listed in inventory.
The move arrives days after Tesla sharply narrowed its Cybertruck lineup. New orders for the Dual Motor AWD and Premium AWD versions have been disabled, leaving only the high-performance Cyberbeast—priced around $109,990 before fees—as the sole configurable option.
Elon Musk has stated that Cybertruck production at Gigafactory Texas will wind down around the middle to late summer of 2027 to free manufacturing space for greater Cybercab output. Tesla has raised prices on remaining trims and is prioritizing higher-margin builds while working through an existing order backlog that exceeds what the line can complete before conversion.
These parallel decisions reflect a broader effort to simplify Tesla’s retail customer lineup. Lower-volume or lower-margin variants are being phased out or deprioritized in favor of core, higher-spec models that generate stronger profitability and clearer production planning.
For the Model Y, this concentrates volume on the remaining RWD and Premium configurations while Premium deliveries already stretch into 2027. For the Cybertruck, it accelerates the transition away from a stainless-steel pickup that underperformed relative to initial volume expectations.
Tesla Model Y Standard Full Review: Is it worth the lower price?
The freed capacity and reduced complexity directly support Cybercab scaling. Tesla began pilot Cybercab production at Giga Texas in early 2026, launched paid autonomous rides in Austin in September, and is preparing for substantial volume growth.
By streamlining the existing vehicle portfolio, the company is reallocating factory space, engineering attention, and supply-chain resources toward its purpose-built Robotaxi, which lacks a steering wheel or pedals and is designed exclusively for unsupervised autonomy.
The result is a leaner retail lineup today and a clearer path to high-volume Cybercab deployment tomorrow.
Elon Musk
SpaceX Starship is going for a catch that could change spaceflight forever
SpaceX will try to catch both Starship stages today, a first for any orbital rocket.

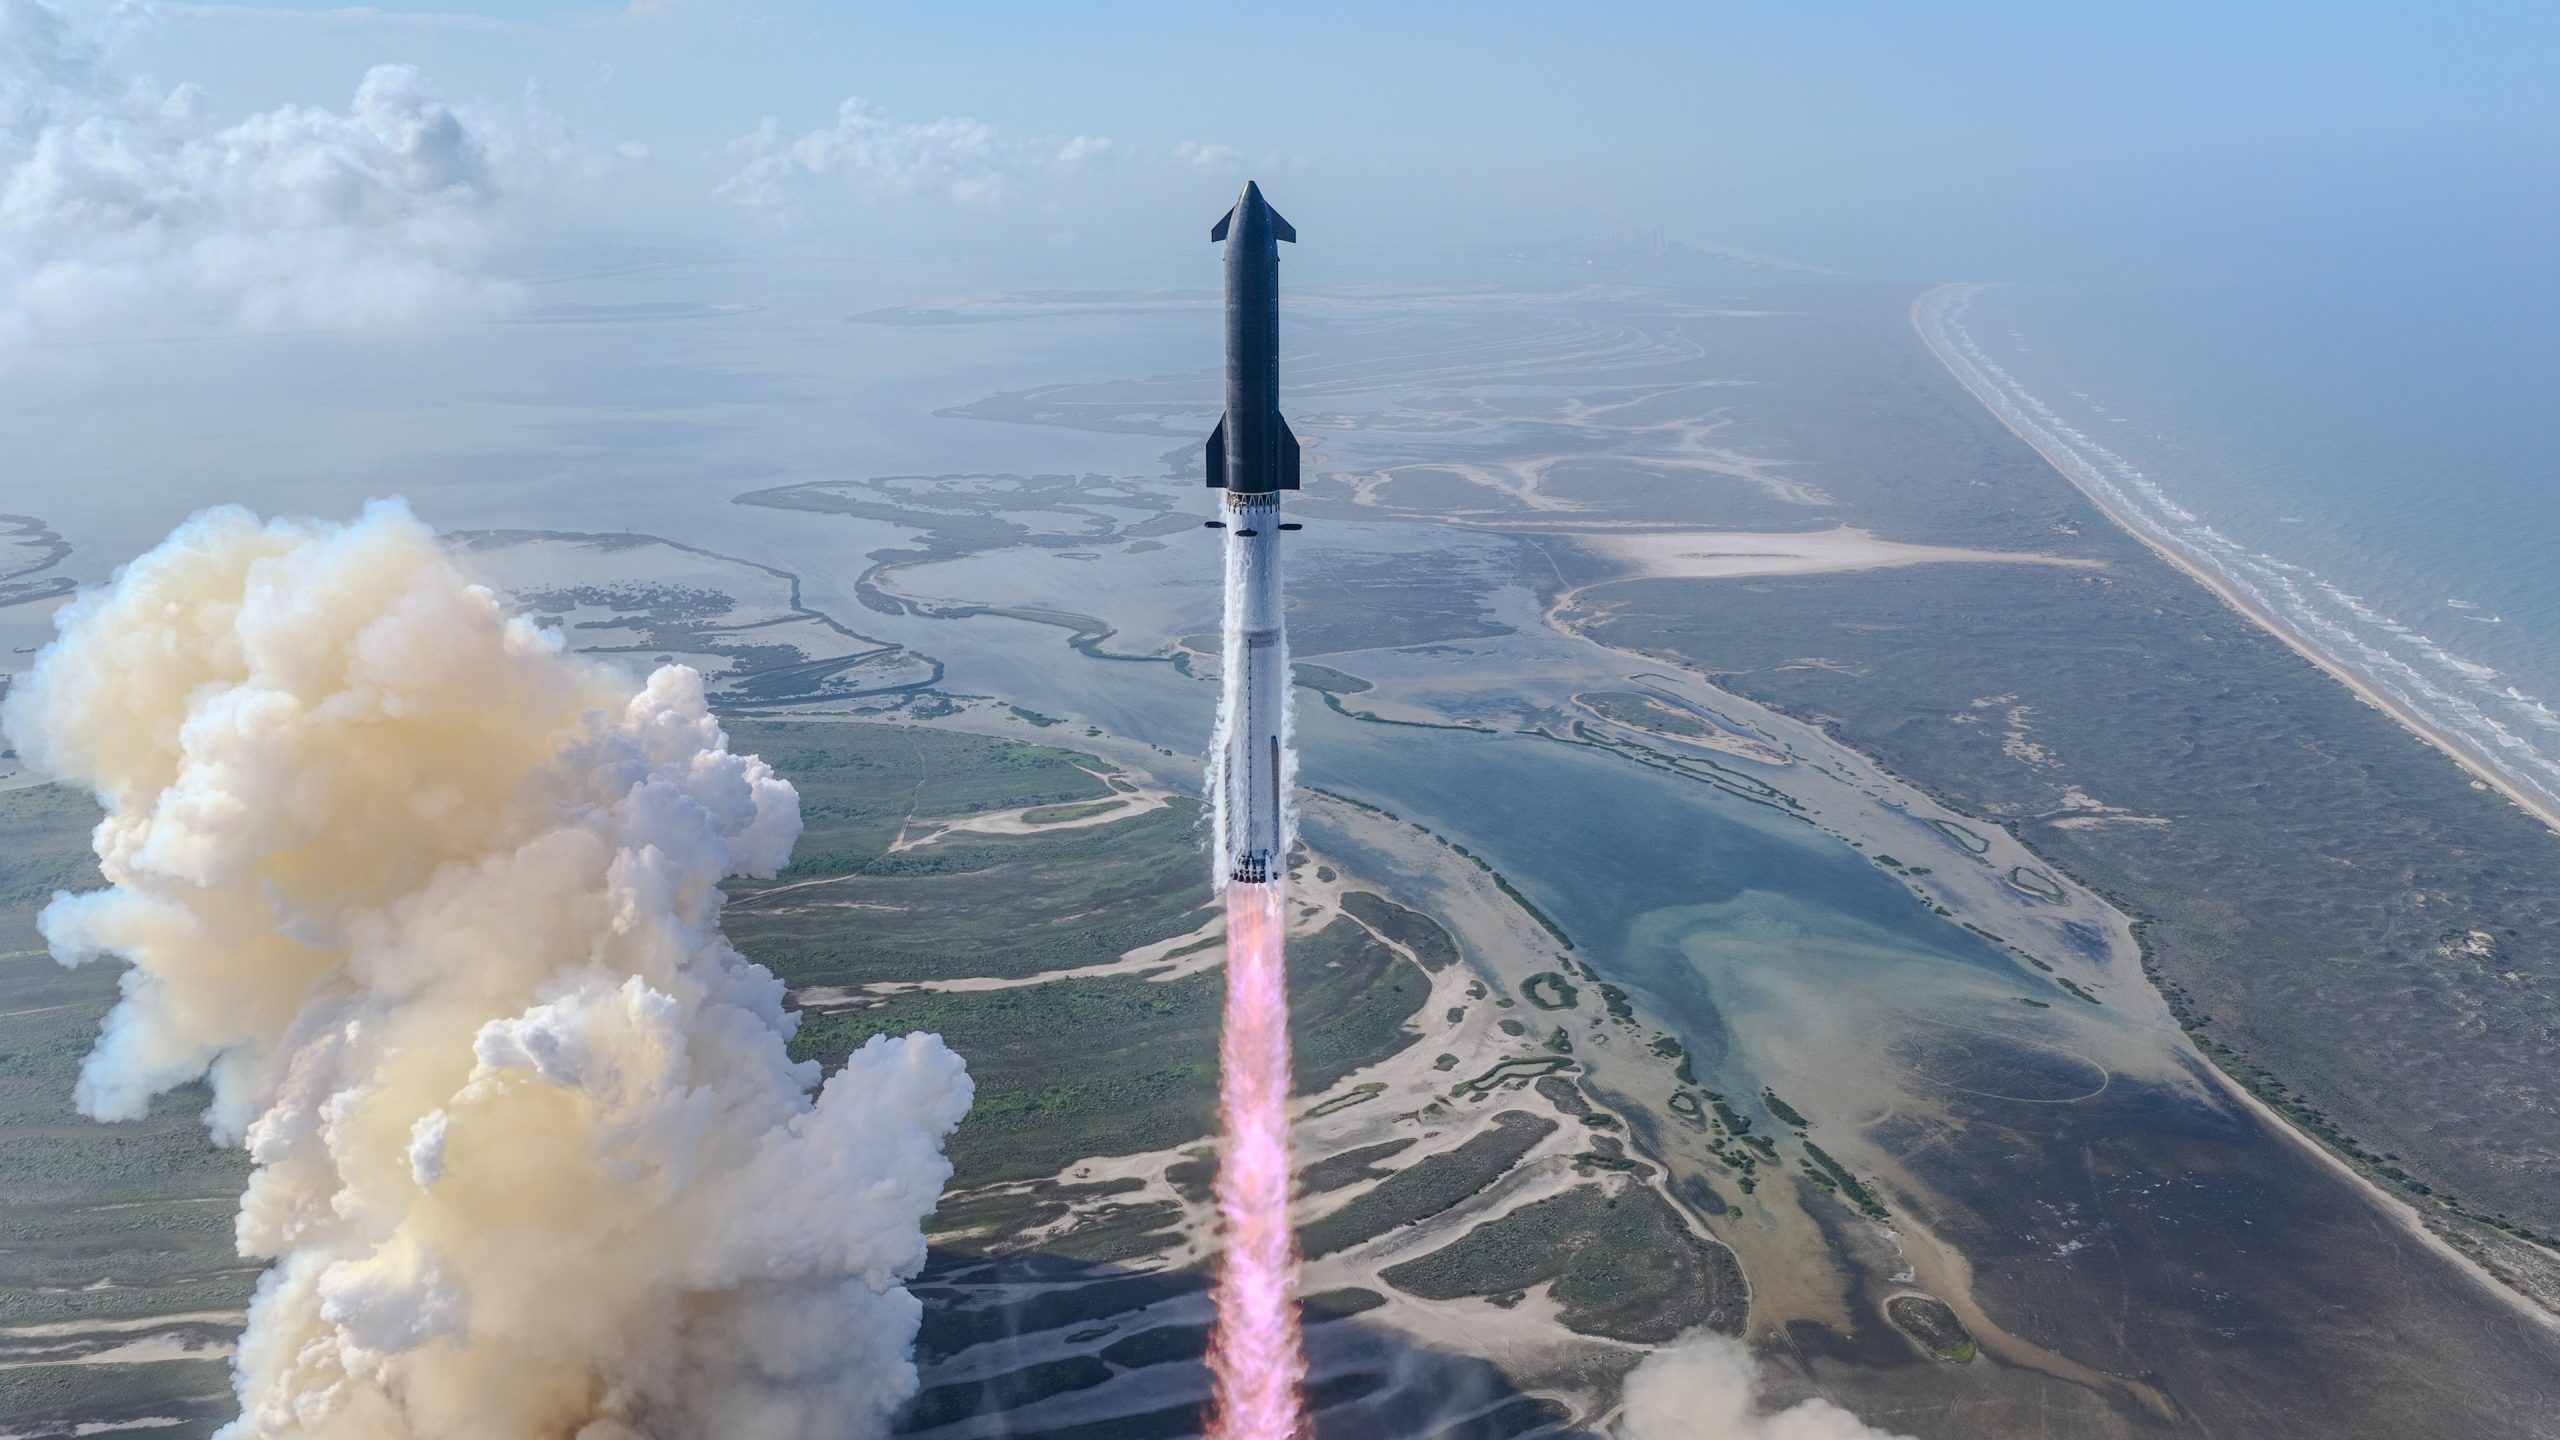
SpaceX is set to launch Starship Flight 15 from Starbase on Friday afternoon, and if both stages make it back to the tower, the mission will go down as the first time an orbital rocket has ever been fully recovered. The 75 minute launch window opens at 4:45 p.m. CT from Pad 2, a day after SpaceX rolled Ship 42 out to the pad and shared photos of the move on X.
The first catch comes quickly. About six and a half minutes after liftoff, Booster 22 is scheduled to fly back to Starbase and settle into the launch tower’s chopstick arms, the first catch attempt for SpaceX’s V3 Super Heavy. SpaceX has caught the booster three times before most recently in March 2025.
Ship 42 moves to the Starbase pad ahead of launch https://t.co/pMUFTHneJQ — SpaceX (@SpaceX) November 13, 2026
The second catch is the one that has never been done. Ship 42 will climb to an orbit about 275 kilometers up, deploy 26 Starlink V3 satellites and complete about 14 orbits. Three of those satellites carry cameras to inspect the ship’s heat shield before it commits to coming home. If its reentry, landing burn and tower approach systems pass their checks, the ship will fire its engines to leave orbit, fall through the atmosphere in its belly flop position, flip vertical and drop into the tower about 22 and a half hours after launch, on Saturday afternoon. SpaceX gave a preview of that maneuver in an animation during its third quarter earnings webcast.
Elon Musk described a successful double catch on that call as “the first time that an orbital launch vehicle has been fully recovered” and a “profound technology milestone,” putting the odds of catching the ship at “more likely than not.” SpaceX has called it a potential “breakthrough moment in making Starship a reliable, rapidly reusable rocket,”
Reuse is where the economics change. Falcon 9 lands its boosters routinely, but its upper stage is thrown away on every flight. Starship is designed so both stages can be refueled and flown again, which is key to cutting launch costs. That matters for Starlink, where each V3 satellite is expected to carry roughly 10 times the download capacity of the V2 Mini satellites flying today, and for Starmind, SpaceX’s planned constellation of AI compute satellites.
It matters for NASA too. Starship is the lunar lander for the Artemis program, and reaching the Moon requires refilling a ship in orbit using several tanker flights. That plan only works if Starships can fly again and again. Musk has said he expects Starship to reach a weekly launch cadence in the first half of 2027.
Investors are paying attention. Morgan Stanley’s Adam Jonas wrote this week that a catch of both stages would likely be “a material positive” for SpaceX stock.
The last Starship flight in September reached orbit for the first time but ended after about three hours with a splashdown in the Pacific, short of its planned 10 hours, after some engines shut down. Since then, Booster 22 has completed a full 33 engine static fire and Ship 42 a six engine firing, as Teslarati previously reported. As of Friday morning, SpaceX was still waiting on the FAA to approve a license change covering the ship’s return over land.
Elon Musk
Tesla and SpaceX merger talks hit a new stage, and one hurdle remains
Tesla and SpaceX merger talks are reportedly advancing, and a deal could arrive by December.
Tesla and SpaceX are moving closer to a combination, with a deal announcement possible as soon as December, Bloomberg reported on Thursday, citing people familiar with the matter. The companies have also discussed a scenario in which the announcement slips into early 2027.
Boards and advisers on both sides are now working through the terms of the deal and the governance structure of the combined company, according to the report. One open item is how many SpaceX shares Tesla investors would receive. Bloomberg had previously reported that the two companies were aiming to announce a deal in the first half of next year and close it before the end of President Donald Trump’s term, so a December announcement would pull that schedule forward by months.
Tesla shares rose as much as 1.9% to $398.35 after the report, while SpaceX gained 0.6% to $140.63. SpaceX carries a market value of about $1.9 trillion following its June IPO, and Tesla is valued at about $1.55 trillion, which would make a combination the largest corporate deal on record. Neither company responded to requests for comment.
The talks became official on October 20, when Elon Musk said on SpaceX’s third quarter earnings call that both companies had formed special committees of independent directors to study a merger, as Teslarati reported. Musk said he could not take part because he is “a conflicted party” and called the process “an odd kabuki dance.” He also noted that Tesla would need approval from 50 percent of all outstanding shares, a bar the company missed in 2025 when a board declassification proposal won support from only 39.4 percent.
China remains the biggest structural problem. Bloomberg’s sources said the companies still need to work out how to isolate Tesla’s large and profitable manufacturing business in China from SpaceX’s U.S. government and defense contracts. JPMorgan analyst Rajat Gupta described those two factors last month as “key dynamics that are at odds with each other” for regulatory and shareholder approval. Musk has repeatedly said Tesla has no plans to separate its China business, a position he restated in August after ARK Invest predicted a merger announcement before the end of the year.
Washington adds another layer. Democrats took control of Congress in this month’s midterms and have pledged to investigate Musk’s business and political activities, which could bring added scrutiny to a deal involving one of the Pentagon’s most important launch and satellite contractors.
The report also lands three weeks before Tesla’s December 3 annual meeting at Giga Texas. That ballot has only three items, led by the re-election of Musk, board chair Robyn Denholm and JB Straubel, and includes no merger proposal. Any deal announced in December would likely require a separate special meeting for Tesla shareholders to vote on it.
The two companies already share a growing list of projects, including the Terafab semiconductor plant in Texas. Tesla’s next generation Roadster, which uses cold gas thrusters built on SpaceX hardware, turned up on display at SpaceX headquarters last month and has become one of the clearest public examples of that overlap.

Tesla trims Model Y offerings as All-Wheel-Drive gets the axe

SpaceX Starship is going for a catch that could change spaceflight forever


