SpaceX
SpaceX CEO Elon Musk says that BFR could cost less to build than Falcon 9

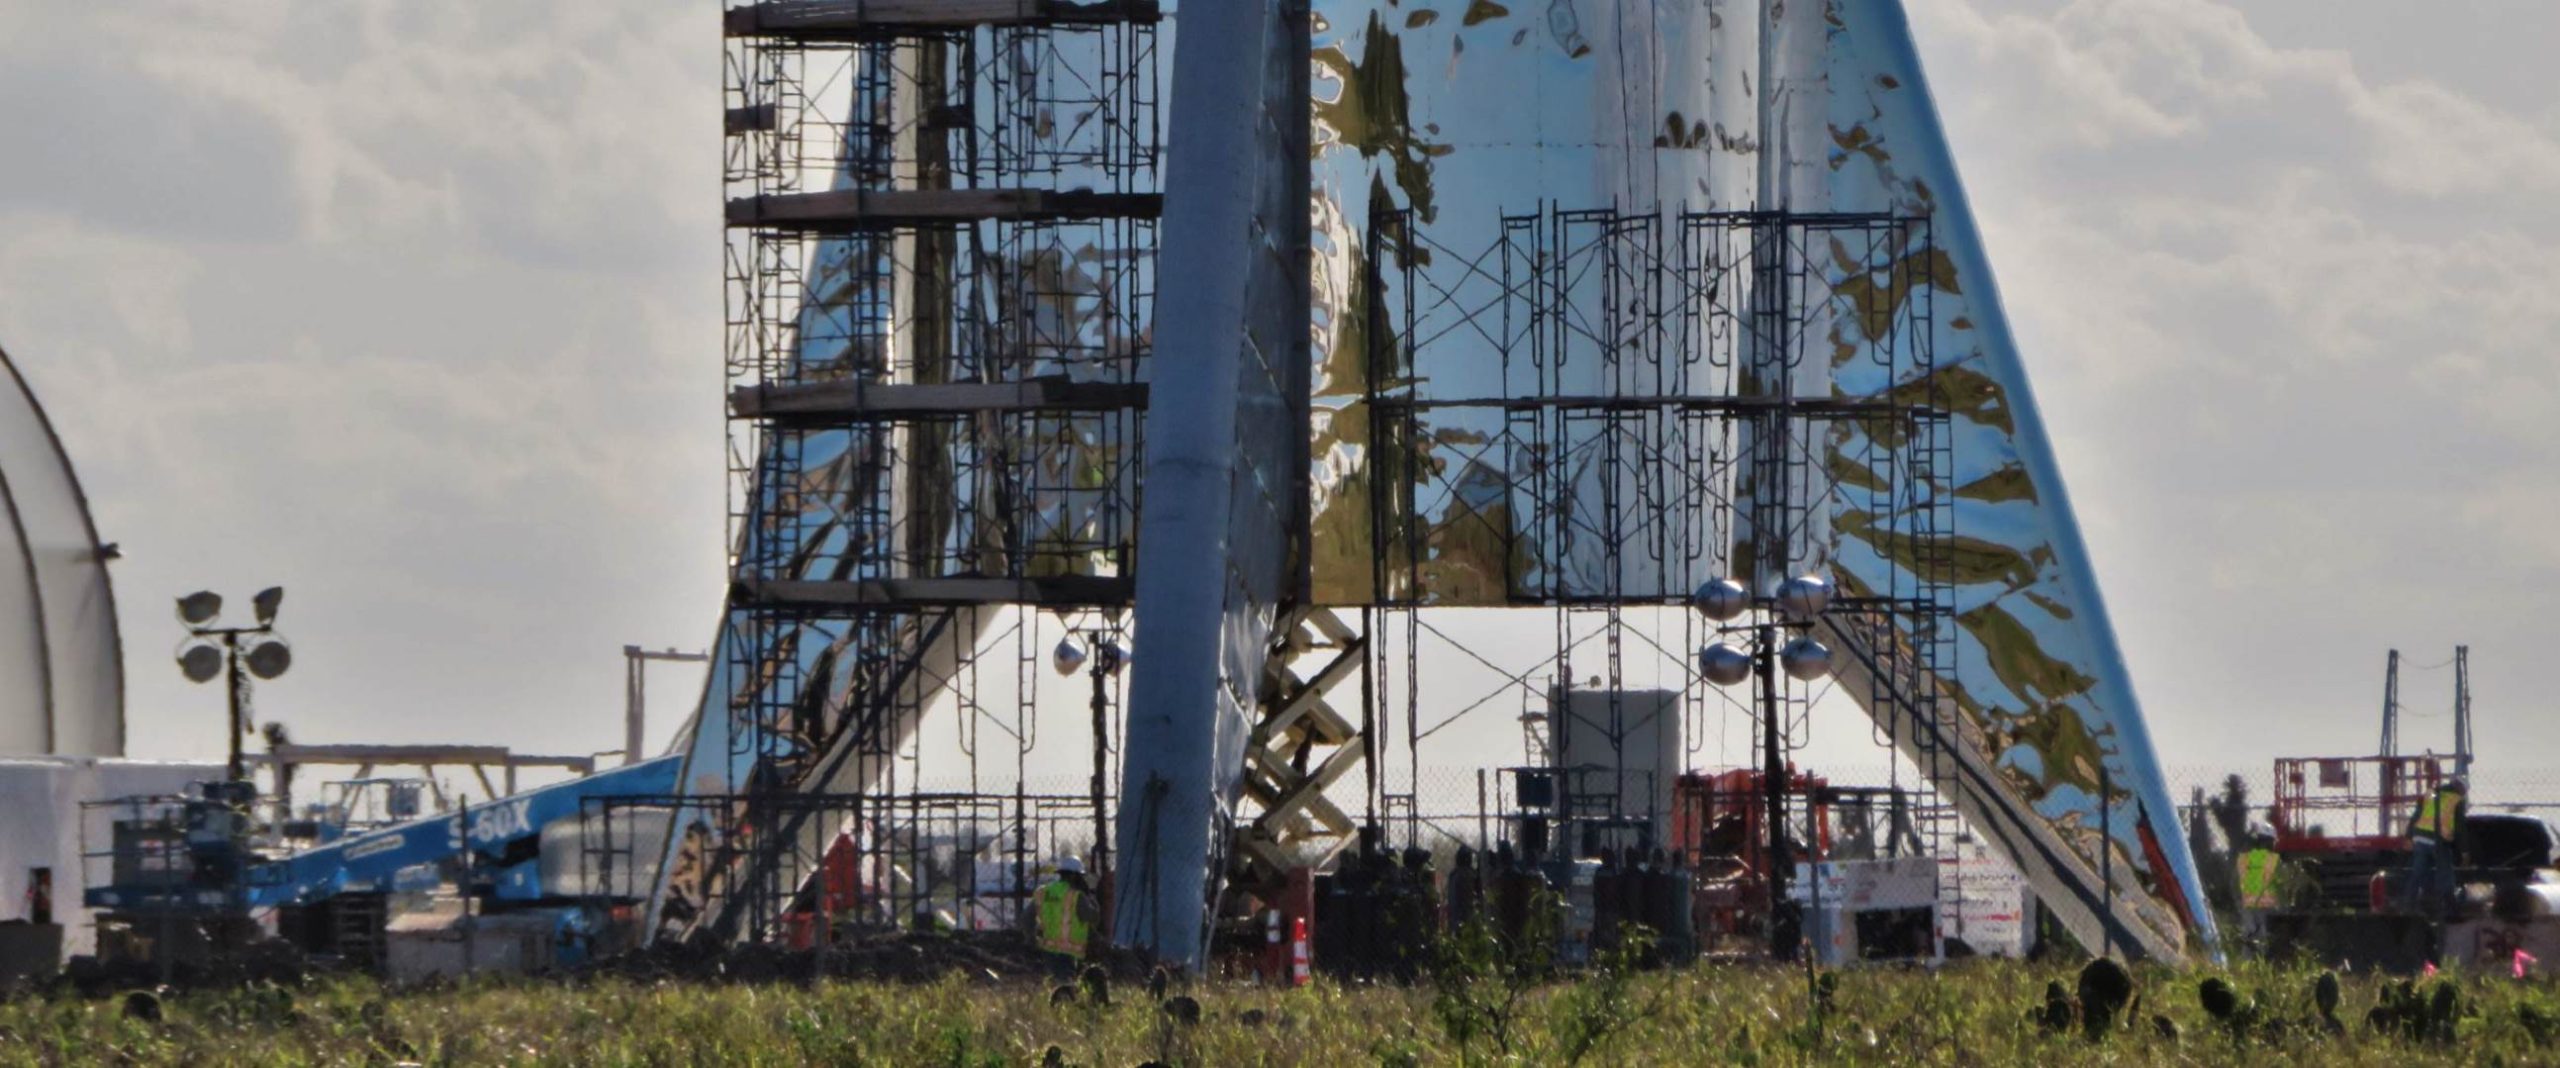
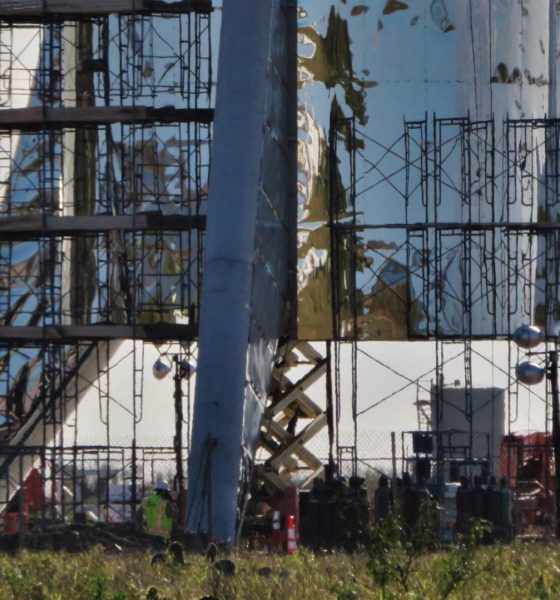
SpaceX CEO Elon Musk believes that there may be a path for the company to ultimately build the massive Starship spacecraft and Super Heavy booster (formerly BFR) for less than Falcon 9/Falcon Heavy, a rocket 3-9 times smaller than BFR.
While it certainly ranks high on the list of wild and wacky things the CEO has said over the years, there may be a few ways – albeit with healthy qualifications – that Starship/Super Heavy production costs could ultimately compare favorably with SpaceX’s Falcon family of launch vehicles. Nevertheless, there are at least as many ways in which the next-gen rocket can (or should) never be able to beat the production cost of what is effectively a far simpler rocket.
This will sound implausible, but I think there’s a path to build Starship / Super Heavy for less than Falcon 9
— Elon Musk (@elonmusk) February 11, 2019
Dirty boosters done dirt cheap
On the one hand, Musk might not necessarily be wrong, especially if one throws the CEO several bones in the interpretation of his brief tweet. BFR at its simplest is going to require a full 38 main rocket engines to achieve its nominal performance goals, 7 on Starship and 31 on Super Heavy. As a dramatically more advanced, larger, and far more complex engine, Raptor will (with very little doubt) cost far more per engine than the relatively simple Merlin 1D. BFR avionics (flight computers, electronics, wiring, harnesses) are likely to be more of a known quantity, meaning that costs will probably be comparable or even lower than Falcon 9’s when measured as a proportion of overall vehicle cost. Assuming that BFR can use the exact same cold gas thruster assemblies currently flying on Falcon 9, that cost should only grow proportionally with vehicle size. Finally, Starship will not require a deployable payload fairing (~10% of Falcon 9’s production cost).
All of those things mean that Starship/Super Heavy will probably be starting off with far better cost efficiency than Falcon 9 was able to, thanks to almost a decade of interim experience both building, flying, and refurbishing the rocket since its 2010 debut. Still, BFR will have to account for entirely new structures like six large tripod fins/wings and their actuators, wholly new thrust structures (akin to Falcon 9’s octaweb) for both stages, and more. Considering Starship on its own, the production of a human-rated spacecraft capable of safely housing dozens of people in space for weeks or months will almost without a doubt rival the cost of airliner production, where a 737 – with almost half a century of production and flight heritage – still holds a price tag of $100-130+ million.
-
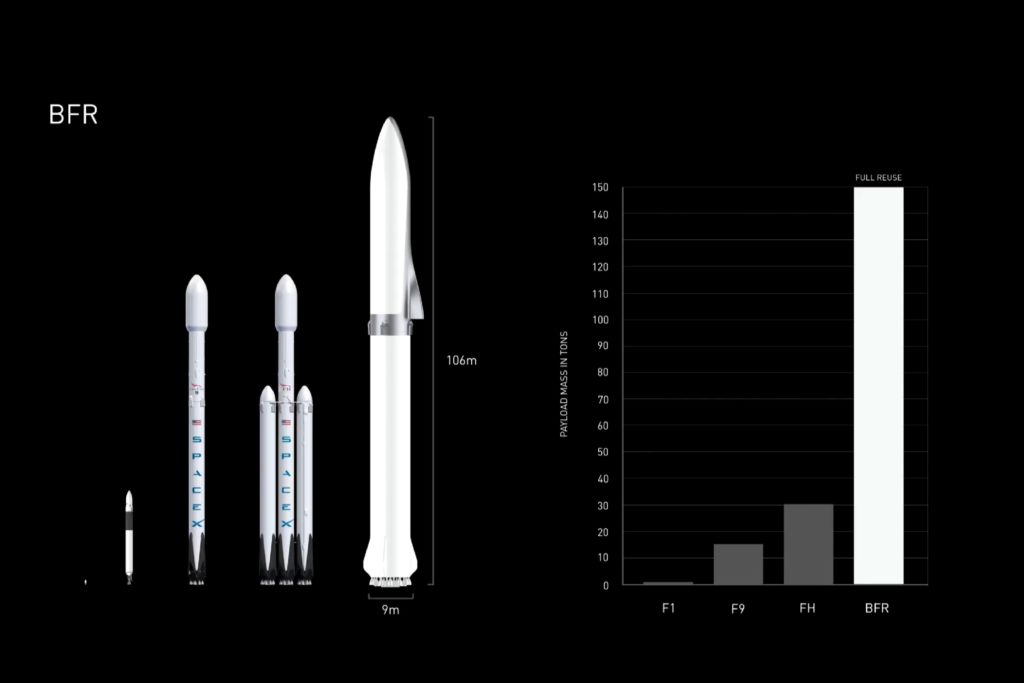
- BFR shown to scale with Falcon 1, 9, and Heavy. (SpaceX)
-
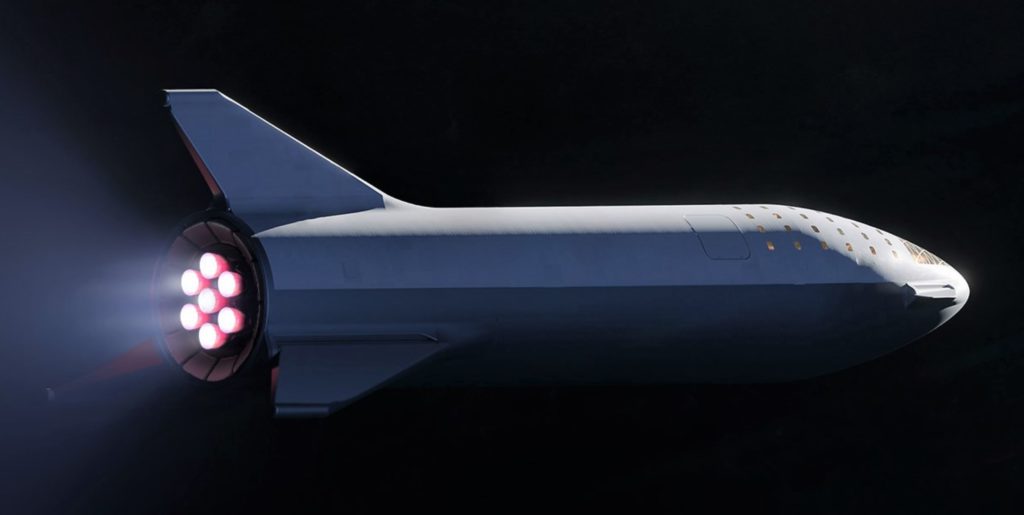
- A September 2018 render of Starship (then BFS) shows one of the vehicle’s two hinged wings/fins/legs. (SpaceX)
-
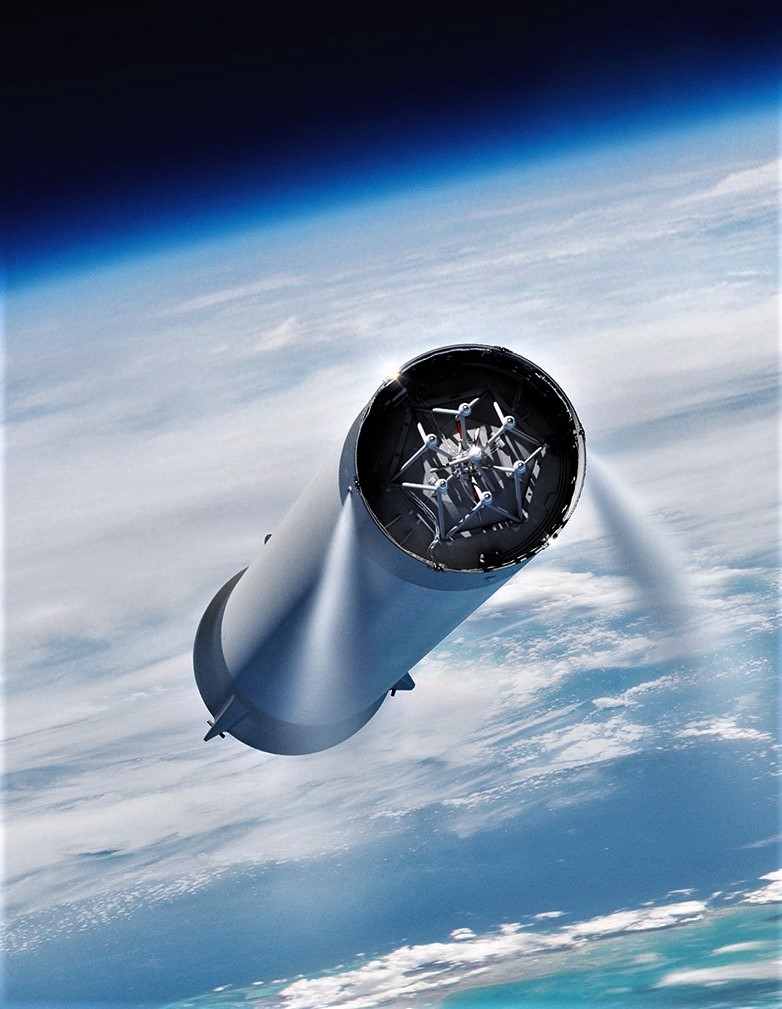
- BFR’s booster, now known as Super Heavy. (SpaceX)
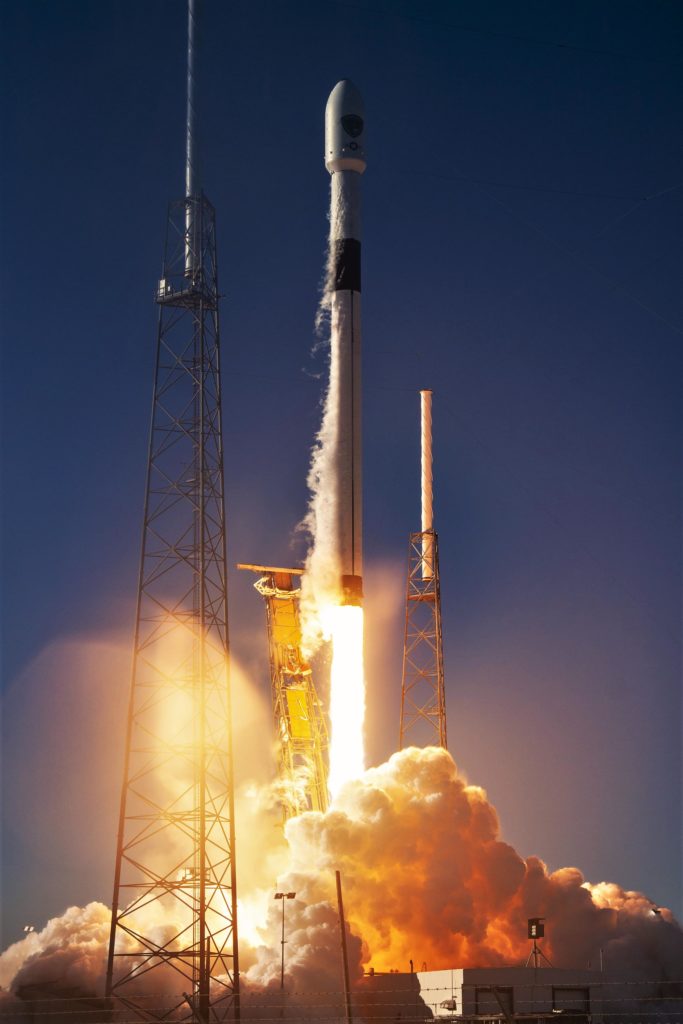
-
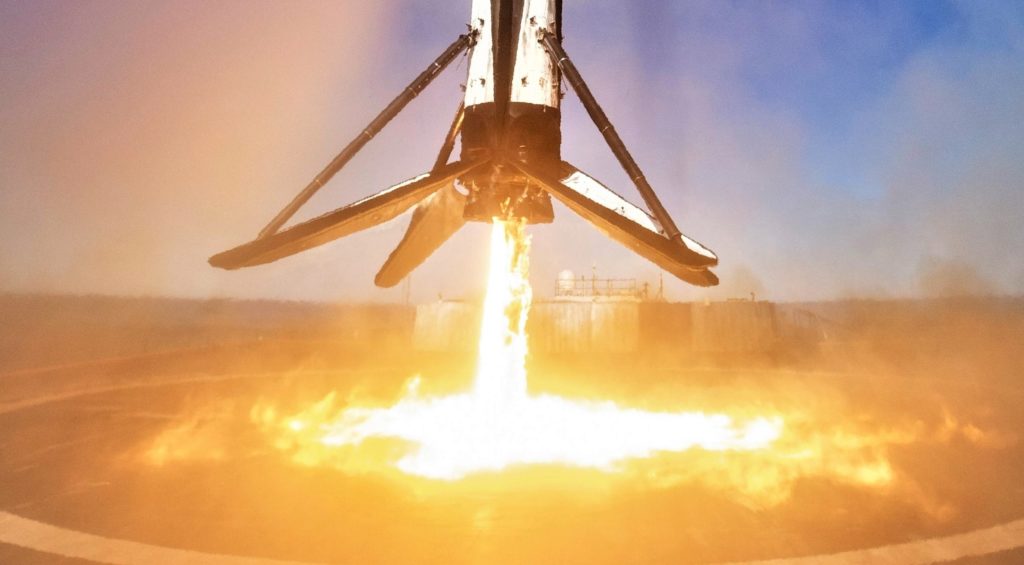
- Sadly, this is a not a sight that will greet Falcon 9 booster B1046’s fourth launch – Crew Dragon’s critical In-Flight Abort test. (SpaceX)
Adding one more assumption, the most lenient interpretation of Musk’s tweet assumes that he is really only subjecting the overall structure (sans engines and any crew-relevant hardware) of BFR relative to Falcon 9. In other words, could a ~300-ton stainless steel rocket structure (BFR) cost the same amount or less to fabricate than a ~30-ton aluminum-lithium alloy rocket structure (Falcon 9/Heavy)? From the very roughest of numerical comparisons, Musk estimated the cost of the stainless steel alloys (300-series) to be used for BFR at around $3 per pound ($6.60/kg), while aluminum-lithium alloys used in aerospace (and on Falcon 9) are sold for around $20/lb ($44/kg)*. As such, simply buying the materials to build the basic structures of BFR and Falcon 9 would cost around and $7.5M and $5M, respectively.
Assuming that the process of assembling, welding, and integrating Starship and Super Heavy structures is somehow 5-10 times cheaper, easier, and less labor-intensive, it’s actually not inconceivable that the cost of building BFR’s structure could ultimately compete with Falcon 9 after production has stabilized after the new rocket’s prototyping phase is over and manufacturing processes are mature.
*Very rough estimate, difficult to find a public cost per unit mass from modern Al-Li suppliers

Costs vs. benefits
On the opposite hand, stainless steel rockets do not have a history of being uniquely cost-effective relative to vehicles using alternative materials. The only orbital-class launch vehicles to use stainless steel (and balloon) tanks are the Atlas booster and the Centaur upper stage, with Atlas dating back to the late 1950s and Centaur beginning launches in the early ’60s. Stainless steel Atlas launches ended in 2005 with the final Atlas III mission, while multiple forms of Centaur continue to fly regularly on ULA’s Atlas V and Delta IV.
Based on a 1966 contract between NASA and General Dynamics placed shortly after Centaur’s tortured development had largely been completed, Centaur upper stages were priced around $25M apiece (2018 USD). In 1980, the hardware for a dedicated Atlas-Centaur launch of a ~1500 kg Comstar I satellite to GTO cost the US the 2018 equivalent of a bit less than $40M ($71M including miscellaneous administrative costs) – $22.4M for Centaur and $17.6M for Atlas. For Atlas, the rocket’s airframe (tanks and general structure) was purchased for around $8.5M. That version of Atlas-Centaur (Atlas-SLV3D Centaur-D1A) was capable of lifting around 5100 kg (11,250 lb) into Low Earth Orbit (LEO) and 1800 kg (~4000 lb) to geostationary transfer orbit (GTO), while it stood around 40m (130 ft) tall, had a tank diameter of 3.05m (10 ft), and weighed ~150t (330,000 lb) fully fueled.
-
- Atlas shows off its shiny steel balloon tanks. (SDASM)
-
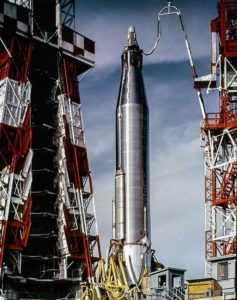
- The original space-faring Atlas, known as SM-65, seen here with a Mercury space capsule. (NASA)
-
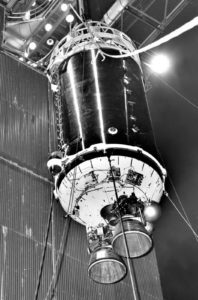
- A Centaur upper stage is pictured here in 1964. (NASA)
-
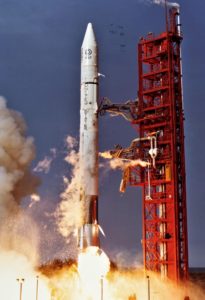
- Atlas SLV3D is pictured here launching a Comstar I satellite.
-
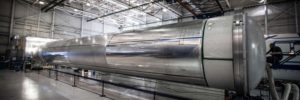
- A Falcon 9 booster is seen here near the end of its tank welding, just prior to painting. (SpaceX)
-
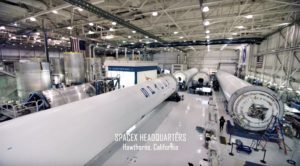
- An overview of SpaceX’s Hawthorne factory floor in early 2018. (SpaceX)
In a very loose sense, that particular stainless steel Atlas variant was about half as large and half as capable as the first flight-worthy version of Falcon 9 at roughly the same price at launch ($60-70M). What does this jaunt through the history books tell us about the prospects of a stainless steel Starship and Super Heavy? Well, not much. The problem with trying to understand and pick apart official claims about SpaceX’s next-generation launch architecture is quite simple: only one family of rockets in the history of the industry (Atlas) regularly flew with stainless steel propellant tanks, a half-century lineage that completed its final launch in 2005.
Generally speaking, an industrial sample size of more or less one makes it far from easy to come to any particular conclusions about a given technology or practice, and SpaceX – according to CEO Elon Musk – fully intends to push past the state of the art of stainless steel rocket tankage with BFR. Ultimately, American Marietta/Martin Marietta/Lockheed Martin was never able to produce launch vehicle variants of the stainless steel Atlas family at a cost more than marginally competitive with Falcon 9, despite the latter rocket’s use of a far more expensive metal alloy throughout its primary tanks and structure.
At least 10X cheaper
— Elon Musk (@elonmusk) February 11, 2019
At some point, it’s even worth asking whether the per-unit cost of Starship and Super Heavy should be relevant at all to their design and construction, at least within reason. If the goal of BFR is to drastically lower the cost of launch by radically improving the ease of reuse, it would be truly bizarre (and utterly unintuitive) if those goals could somehow be achieved without dramatically raising the cost of initial hardware procurement. Perhaps the best close comparison to BFR’s goals, modern airliners are eyewateringly expensive ($100-500M apiece) as a consequence of the extraordinary reliability, performance, efficiency, and longevity customers and regulatory agencies demand from them, although those costs are admittedly not the absolute lowest they could be in a perfect manufacturing scenario.
At the end of the day, it appears that Musk is increasingly of the opinion that the pivot to stainless steel could ultimately make BFR simultaneously “better, faster, [&] cheaper”. However improbable that may be, if it does turn out to be the case, Starship and Super Heavy could be an unfathomable leap ahead for reliable and affordable access to space. It could also be another case of Musk’s excitement and optimism getting the better of him and hyping a given product well beyond what it ultimately is able to achieve. Time will tell!
Check out Teslarati’s newsletters for prompt updates, on-the-ground perspectives, and unique glimpses of SpaceX’s rocket launch and recovery processes!

Elon Musk
Tesla’s Roadster appearance at SpaceX has merger watchers talking
Tesla’s next generation Roadster was spotted at SpaceX’s Hawthorne headquarters, two weeks after its unveiling.

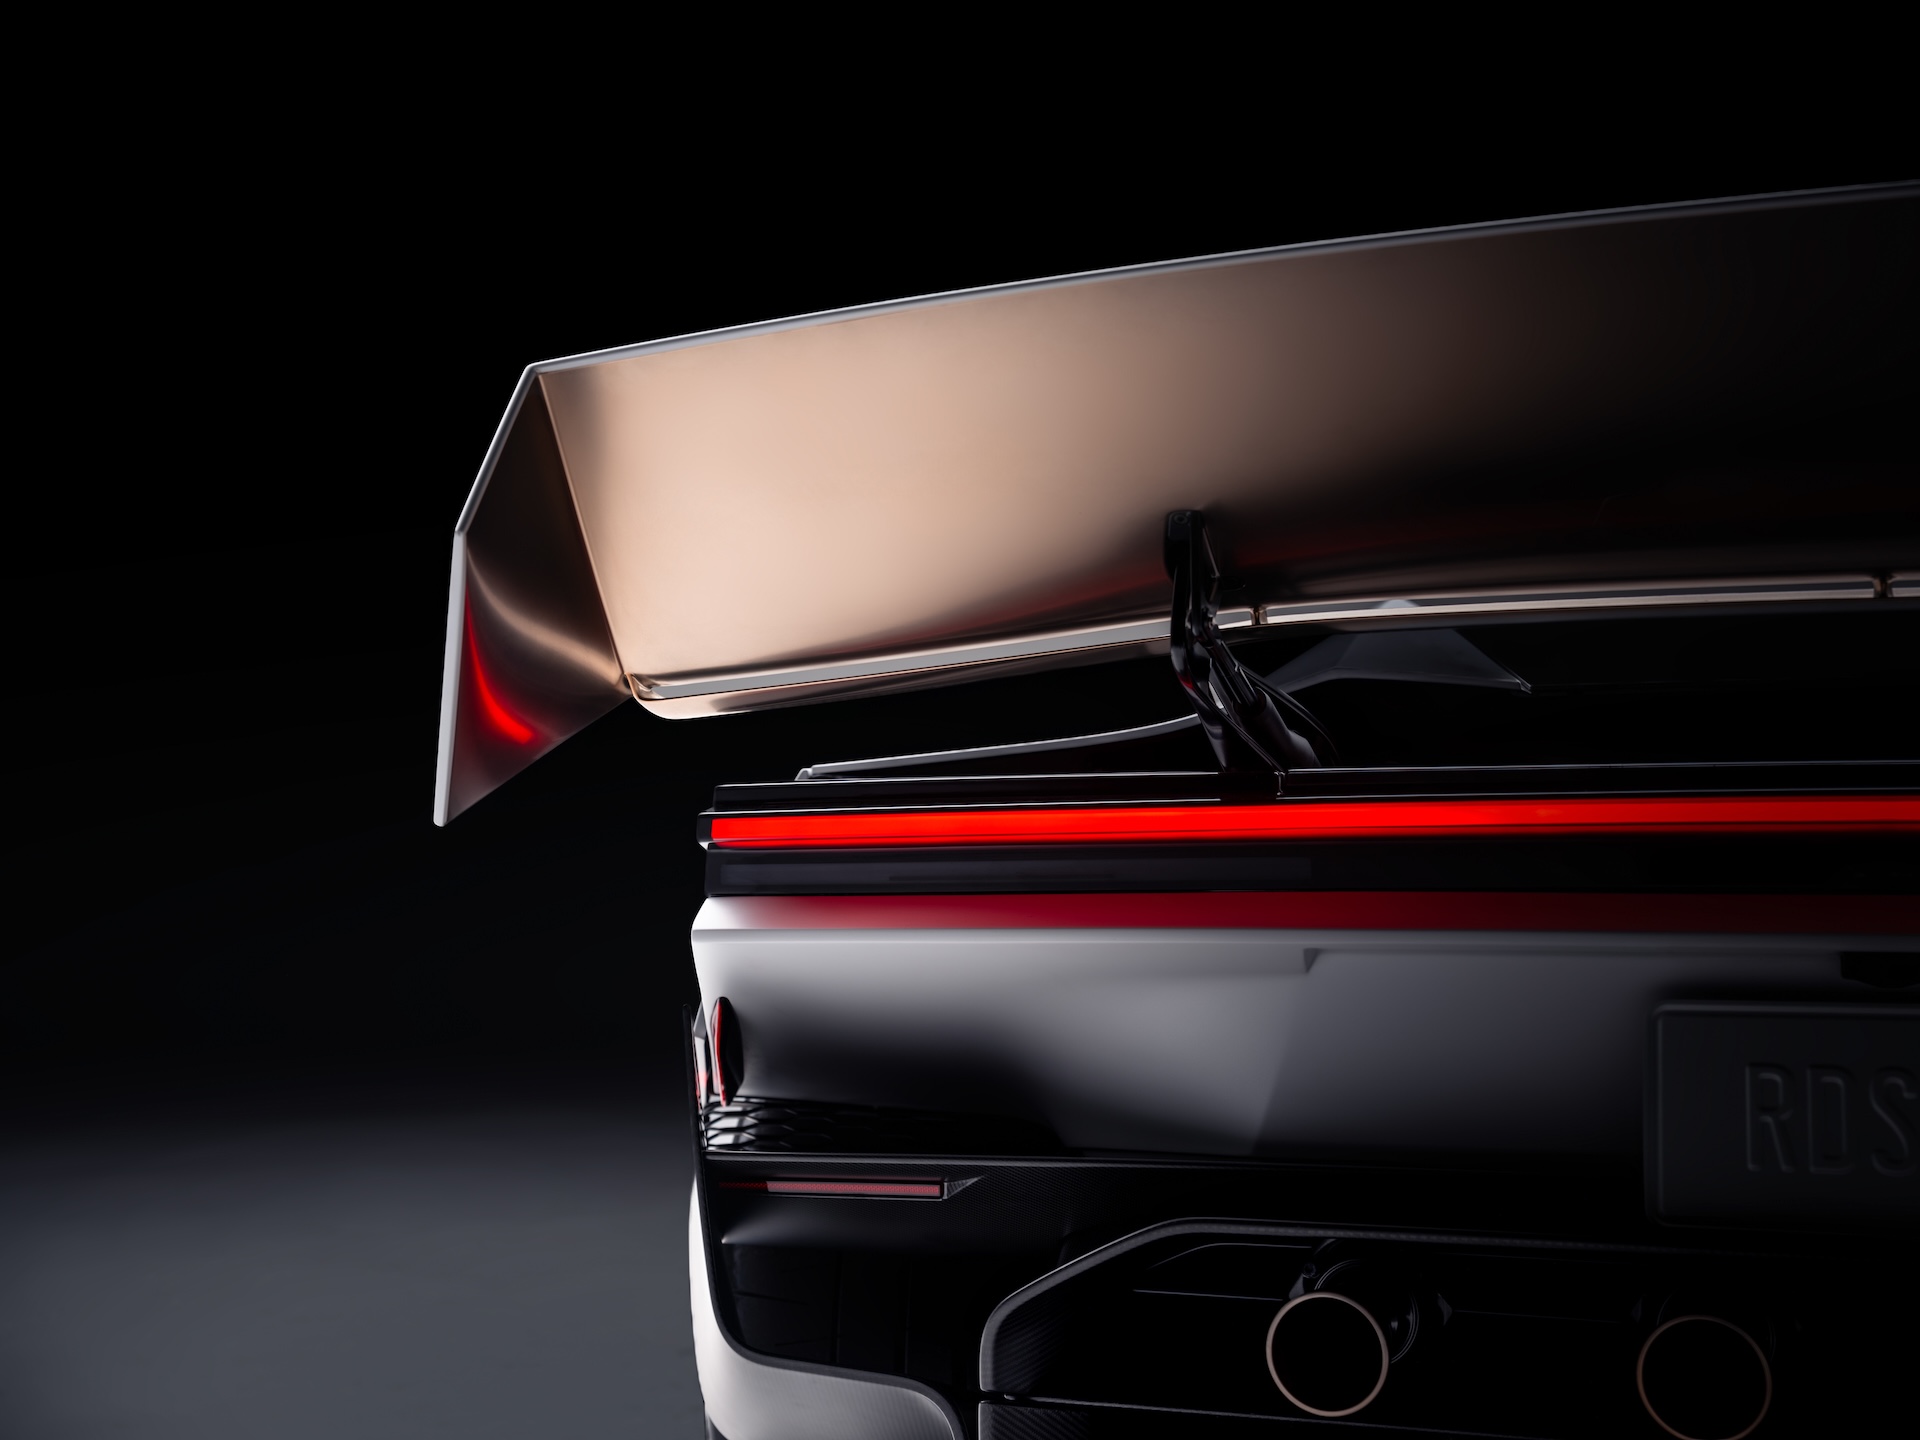
Tesla’s next generation Roadster turned up at SpaceX’s headquarters in Hawthorne, California on Wednesday, less than two weeks after the car flew off a ramp at its unveiling in Texas.
Photos shared on X by SpaceX Engineer (@DeannaRiceSPCX) show the new Roadster parked outdoors beside the famed Falcon 9 that stands outside company headquarters at the corner of Crenshaw Boulevard and Jack Northrop Avenue. Rocket B1019 was the first orbital-class booster ever to land after a launch on December 21, 2015 after it sent 11 Orbcomm satellites to orbit and then flew back to Landing Zone 1 at Cape Canaveral, which would be the first landing in what became SpaceX’s reusable rocket program. SpaceX chose not to fly it again. After a test fire in Florida, the booster was shipped to Hawthorne and raised upright as a permanent monument in August 2016, as Teslarati reported at the time. Putting the Roadster, which flies on SpaceX cold gas thrusters, next to the rocket that started SpaceX’s landings is symbolic in itself.
Small car, big rocket ambitions 🚀🚗 #roadster #falcon9 #spacex #tesla https://t.co/H32xUSXoCl
— Deanna Rice (@DeannaRiceSPCX) October 29, 2026
The Thrust and Rocket versions of the Roadster use cold gas thrusters fed by composite overwrapped pressure vessels, the same type of tank SpaceX flies on Falcon 9, and Elon Musk described the car as the work of Tesla and SpaceX engineers working together. Tesla lists 0 to 60 mph in under 0.9 seconds for Thrust and under 0.59 seconds for Rocket, while the base Performance model relies on a fan and ground sealing system for grip, as Teslarati detailed in its breakdown of the three Roadster configurations.
Tesla has kept the car in the spotlight since the October 15 event near Waco. Last week, the company posted a video of the Roadster’s fighter jet inspired cockpit, including a Track Mode screen with a “Thruster · 5,500 PSI” readout, which we covered in our look at the Roadster’s center display. Musk also said owners will be able to ask the car to perform the stunts autonomously, and promised a looping track at Tesla’s Texas headquarters.
The visit comes as special committees at Tesla and SpaceX weigh a possible merger, a step Musk confirmed on SpaceX’s third quarter earnings call. The Roadster, built on SpaceX hardware, has become one of the clearest examples of the two companies already building products together.
Musk said at the unveiling that Roadster production will begin in 2028. Reservations are open with a $50,000 payment, Thrust is listed as a limited release and Rocket is invite only. Tesla says the car is not approved for public road use.
News
Verizon, AT&T and T-Mobile are trying to shut Starlink out before FCC vote
AT&T, Verizon and T-Mobile want 290 MHz cut from an FCC satellite plan before Thursday.
AT&T, Verizon and T-Mobile are asking the Federal Communications Commission to pull nearly 300 MHz of spectrum out of a proposal that would let satellite companies like SpaceX offer cell service directly to ordinary phones. The request lands one day before the agency votes on it.
The FCC will vote Thursday, October 29, on a notice of proposed rulemaking that would make an additional 482 MHz available for direct to device service, expanding the number of eligible bands from five to 13, according to the FCC fact sheet. It would also scrap the rule requiring a satellite operator to lease spectrum from carriers, replacing it with a certification that the operator has coexistence agreements in place or holds the terrestrial license itself.
That second path matters for SpaceX. As Teslarati reported earlier this month, SpaceX agreed to buy Grain Management’s nationwide 800 MHz portfolio to turn Starlink Mobile into a full US carrier, adding to the spectrum it already bought from EchoStar.
The carriers want two bands removed, 2.5 GHz and 3.45 GHz, which make up 290 MHz of the 482 MHz on the table. Through industry group CTIA, they argued that about 300 million users depend on those bands and that satellite operations in them are not technically feasible. T-Mobile, which calls 2.5 GHz the foundation of its Ultra Capacity 5G network, said in its own filing that satellite interference could wipe out up to 96% of a cell site’s uplink coverage area and cut uplink speeds by 88% to 99%.
Executives from all three carriers met with FCC staff on October 20, and T-Mobile CEO Srini Gopalan met separately with FCC Chairman Brendan Carr. T-Mobile’s role stands out because it is still SpaceX’s US launch partner for Starlink Mobile. The three carriers have also teamed up on their own satellite joint venture to pool spectrum, a move widely seen as a response to Starlink.
SpaceX is asking for the opposite. In an October 23 filing after meetings with FCC staff and commissioners’ offices, the company asked regulators to add the 902 to 928 MHz band to the proposal. “Doing so now saves time later,” SpaceX wrote. The company also asked the FCC to modernize interference rules and align satellite deployment requirements with those for terrestrial cell networks, saying the goal is to let satellite and ground networks work together so Americans stay connected wherever they are.
The carriers have not been shy about how they view SpaceX as a competitor. On Verizon’s third quarter earnings call Monday, its chief executive said Starlink Mobile “just can’t compete with a terrestrial network” and estimated SpaceX would need four to six years and $300 billion to $500 billion to build a full US carrier network.
Thursday’s vote will not settle which bands survive. Adopting the notice opens a public comment period, with final rules to come later in the proceeding. The FCC already considered and rejected 2.5 GHz for satellite coverage once, in 2024. SpaceX also is not the only satellite player watching: the FCC approved Amazon’s $11.6 billion acquisition of Globalstar on October 27, giving its planned direct to device fleet its own mobile satellite spectrum.

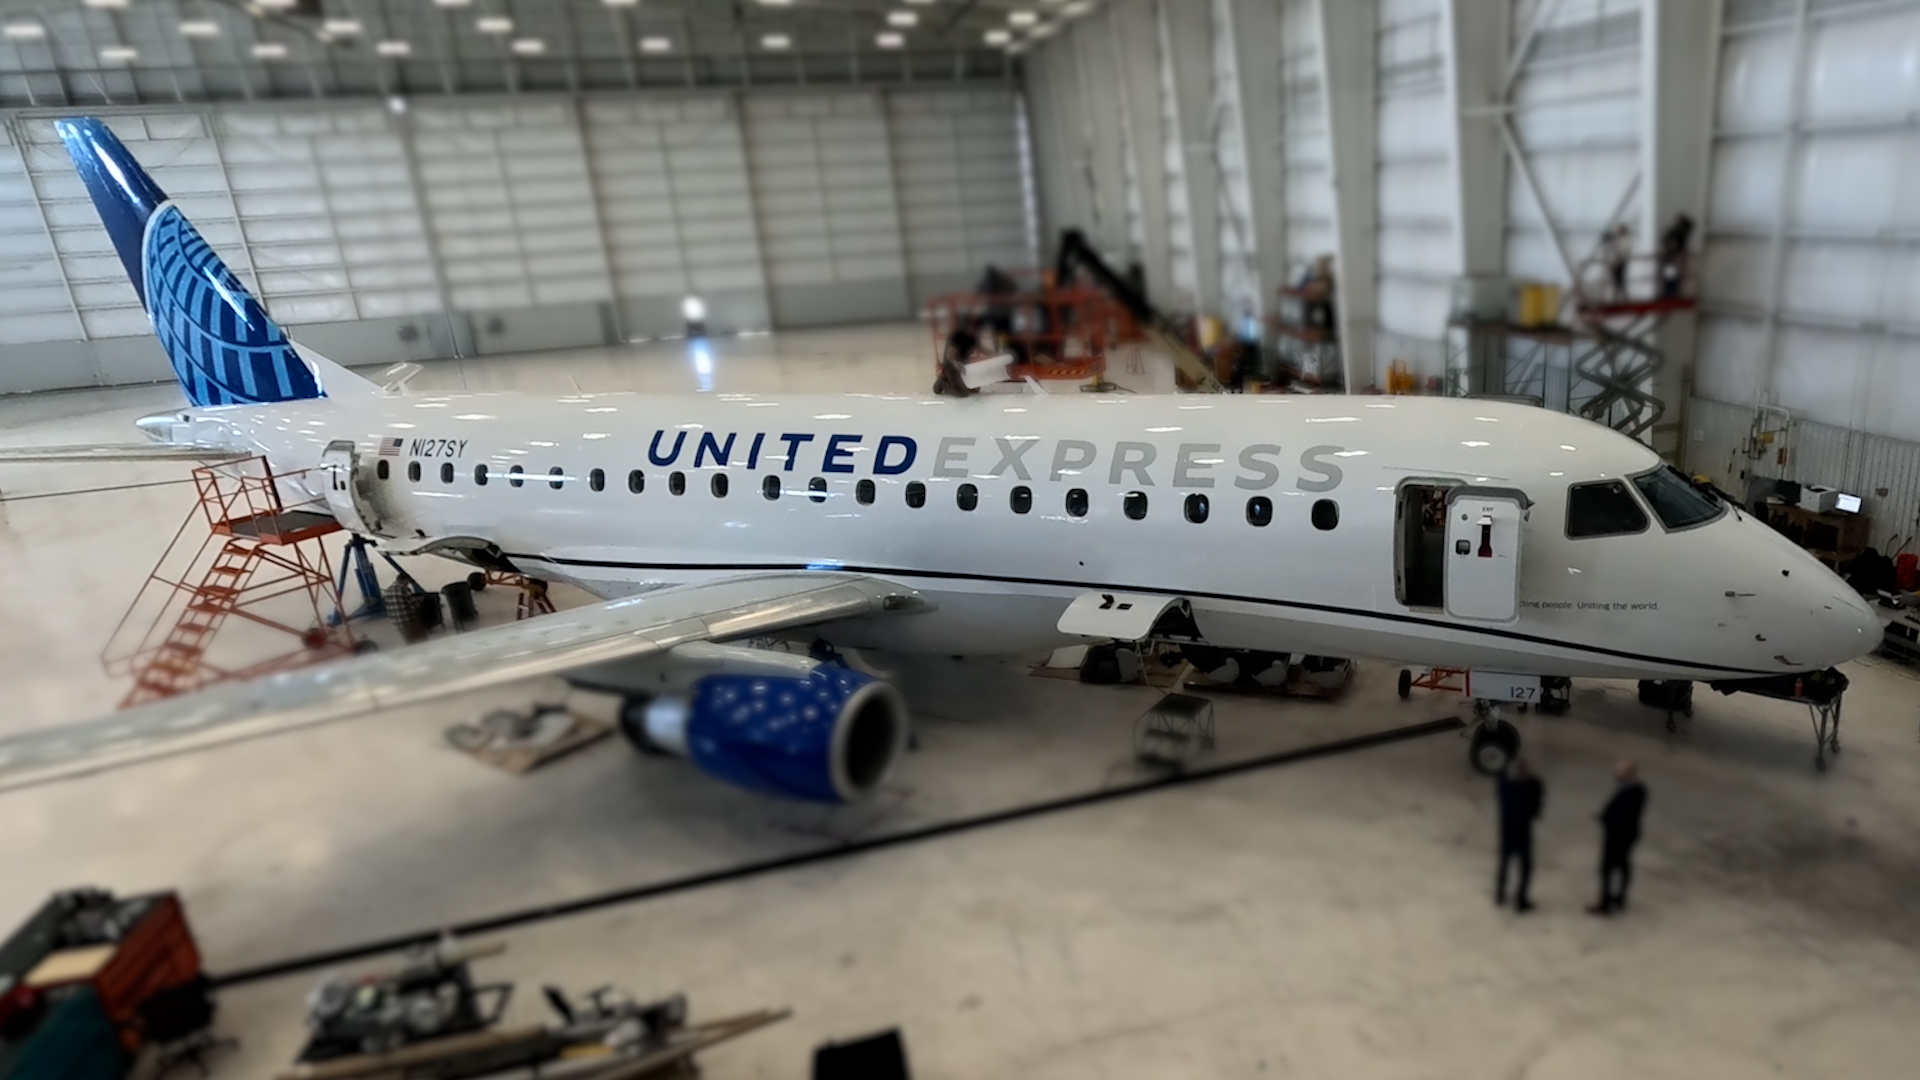
United Airlines CEO Scott Kirby said that SpaceX’s Starlink satellite internet is its leading competitive advantage in the U.S. airline industry. However, in recent comments, while he described the service as “the biggest competitive advantage” the carrier currently holds, he also acknowledged that the edge is temporary.
“…everybody eventually is going to have high-speed low earth orbit internet connectivity. It’s going to be a must-have. We are going to have a few years of being the only airline that has it at scale, and that’s our mission,” Kirby said. Until everyone has it, United aims to capitalize on its head start by converting trial users into long-term loyal customers.
🚨 United CEO Scott Kirby calls Starlink “the biggest competitive advantage,” but says it’s temporary.
“I think it’s the biggest competitive advantage. And it’s temporary. Like it’s not, everybody eventually is going to have high speed low earth orbit internet connectivity. It’s going to be a must-have. But we are going to have a few years of being the only airline that has it at scale, and that’s our mission.”
“I think we’re going to convince customers that United is the best airline and we’re going to get customers to switch their loyalty, to get our credit card, switch their loyalty to United. Not because of Starlink. They’re going to try us for Starlink and they’re going to stay with all the other technology, and everything else is better, and the technology in particular is so much better than technology other, and it’s accelerating because we’ve got the right tech stack, and because we’re like, our gap is getting wider and wider with our technology every day.”
Next: LAX becomes United’s first 100% Starlink hub in the first half of next year, and the United app will show your Starlink odds for each flight. https://t.co/hToyFWaWj7
— TESLARATI (@Teslarati) October 27, 2026
United has moved faster than its rivals on Starlink installations. As of mid-to-late October 2026, the system was on roughly 43 percent of its fleet, with plans to reach 61 percent by year-end, 87 percent by June 2027, and full fleet coverage by the end of next year.
The airline already operates more Starlink-equipped flights than the rest of the U.S. industry combined. Los Angeles International Airport is scheduled to become United’s first 100 percent Starlink hub in the first half of 2027, and the carrier’s app will display the likelihood that any given flight has the service.
Kirby has pointed to early evidence that the offering influences booking decisions. Some passengers loyal to other airlines are already switching flights for Starlink connectivity, something the airline, along with American Airlines, has tried to leverage against competing airlines. Both companies used status-match programs, and some of those customers are pursuing company-specific credit cards, which signals an intent to stay.
Once onboard, these customers encounter the airline’s broader investments in aircraft, larger seat-back screens, oversized bins, connection tools, and a mobile app that Kirby says outperforms competitors. Wi-Fi satisfaction scores on Starlink-equipped planes have been reported to be nearly double those on aircraft with other systems.
Competitors are moving slowly to do the same. Southwest Airlines began installations in 2025 and expects to complete them soon. Delta is pursuing Amazon’s Leo system, while American expects to start Starlink work in early 2027 and has not yet detailed regional-fleet plans. This timeline gap gives United a multi-year window in which it remains the only major U.S. carrier offering Starlink at scale.
Kirby has framed the strategy as pressing that advantage while simultaneously widening gaps in other technology areas so that customers who try United for the Wi-Fi remain for the overall experience.
The approach reflects a calculated bet that superior in-flight connectivity can accelerate share gains and support longer-term financial targets, including a 10 percent pre-tax margin goal.
High-speed internet is particularly valued by premium and business travelers who can work or stream reliably. As low-Earth-orbit service becomes ubiquitous, the temporary nature of the pure connectivity edge means United’s retention will depend on whether its other product and operational improvements keep pace.

Tesla’s Roadster appearance at SpaceX has merger watchers talking

Verizon, AT&T and T-Mobile are trying to shut Starlink out before FCC vote


