News
Tesla gives Fiat a wake up call: ‘fake’ electric cars can still manipulate EU emissions standards

New CO2 regulations set to take effect in Europe have several loopholes in place that could derail the goal of reducing new car emissions by 37.5% in the region by 2030, according to a study published by advocacy group Transport & Environment. In a worst-case modeling scenario, gaming of the rules could also result in almost two million fewer zero or low emissions vehicles coming to market between 2025 and 2030, and of those in the market, half might be plug-in hybrids built for compliance, not innovation.
In order to propel the creation of a battery electric auto industry in the region, European Union members and parties participating in the discussions over the new CO2 regulations included incentives in the agreement that were tied to specific vehicle sales. Auto manufacturers with 15% of their sales coming from zero and low emission vehicles by 2025 and 35% from 2030 onwards will have their CO2 targets reduced by a maximum of 5%. This effectively means a company’s new fleet-wide CO2 output would only need to be reduced to 34.4% by 2030 instead of 37.5%, as calculated in the study.
Companies have further been allowed to pool their fleets together to help reach these goals, something which Tesla has recently taken advantage of by partnering with Fiat Chrysler. As a manufacturer of zero-emission vehicles, counting Tesla’s fleet with Fiat’s lowers the average per-vehicle CO2 output, thus lessening the burden for Fiat to meet the emissions standards while Tesla profits from the deal.

On its face, the 5% trade-off for lower emissions standards would be the entry of new, more innovative clean energy vehicles on the market; however, the inclusion of plug-in hybrids in that calculation could be problematic and used to game the system. In order to qualify as a low emissions vehicle, a hybrid car only needs to be under a threshold of 50 g/km CO2 output during testing which assumes full use of the vehicle’s battery. Because most of these plug-in hybrids have very low battery ranges, they’re often not used in practice in favor of the internal combustion engine, thus increasing their real-world CO2 output to around 120 g/km.
The technology behind plug-in hybrids is less innovative and therefore cheaper to produce, so the financial appeal of producing more of these types of vehicles over battery-only electric vehicles is high. The Transport & Environment study estimates that this effect will lead to about 2 million fewer all-electric cars being produced in favor of the cheaper, ‘fake’ electric compliance hybrids.
Other loopholes in the EU regulations also contribute to a reduction in CO2 outcomes. Fourteen countries where non-existent or nascent low emissions vehicle markets were identified will receive nearly double the emissions credit for eco-friendly cars sold to encourage development in the regions.


Simply, a large manufacturer could register thousands of vehicles in one of these markets, acquire double credit for each vehicle, and then quickly sell the vehicles in an established market where demand is higher. When sold, the cars would technically be “used” for record keeping purposes, but new to consumers and presented that way. This would circumvent the point of developing a low emissions market in those countries, further limiting the expansion of low emissions car availability.
The EU member states where double credits apply are Ireland, Greece, Poland, Slovenia, Croatia, the Czech Republic, Slovakia, Bulgaria, Romania, Estonia, Latvia, Lithuania, Cyprus, and Malta.
The final (possible) loophole identified in the Transport & Environment study lies with the inclusion of Norway in the EU regional calculations. The country has not yet formally been included in the 2025/30 standards but is part of the 2020/1 standards currently in effect and will likely be included in the upcoming rules.
Norway is requiring 100% of its vehicles to have zero emissions by 2025, thus guaranteeing sales of those types of cars in a market where ICE vehicles are not competitive. Automakers could concentrate their sales in that region and make less effort to sell in the rest of Europe, all while still remaining compliant with the regulations. Reaching compliance in this manner is another way the intent of the coming CO2 reduction requirements can be manipulated.

The authors of the Transport & Environment study have laid out their proposals to overcome these loopholes, but considering that they were included to win the support of the auto industry in the region, further changes to the regulations seem unlikely. Also, the study could be taking an overly pessimistic view of the possible outcomes the loopholes could lead to.
Consumer markets, even without significant CO2-related regulation, are already showing trends towards increasing low emission vehicle demands, especially for battery electric vehicles like those sold by Tesla. This “Tesla Effect” has been noted by the upper echelons of legacy auto and several have committed to billions in electric fleet investments. Porsche is unveiling its first production electric vehicle, the Taycan, this September and has plans to retire its diesel-powered lineup and embrace electrification. Ford has also recently committed to electrifying its F-series, most notably the classic F-150, as well as invest $11 billion dollars to produce 40 electrified vehicles by 2022.



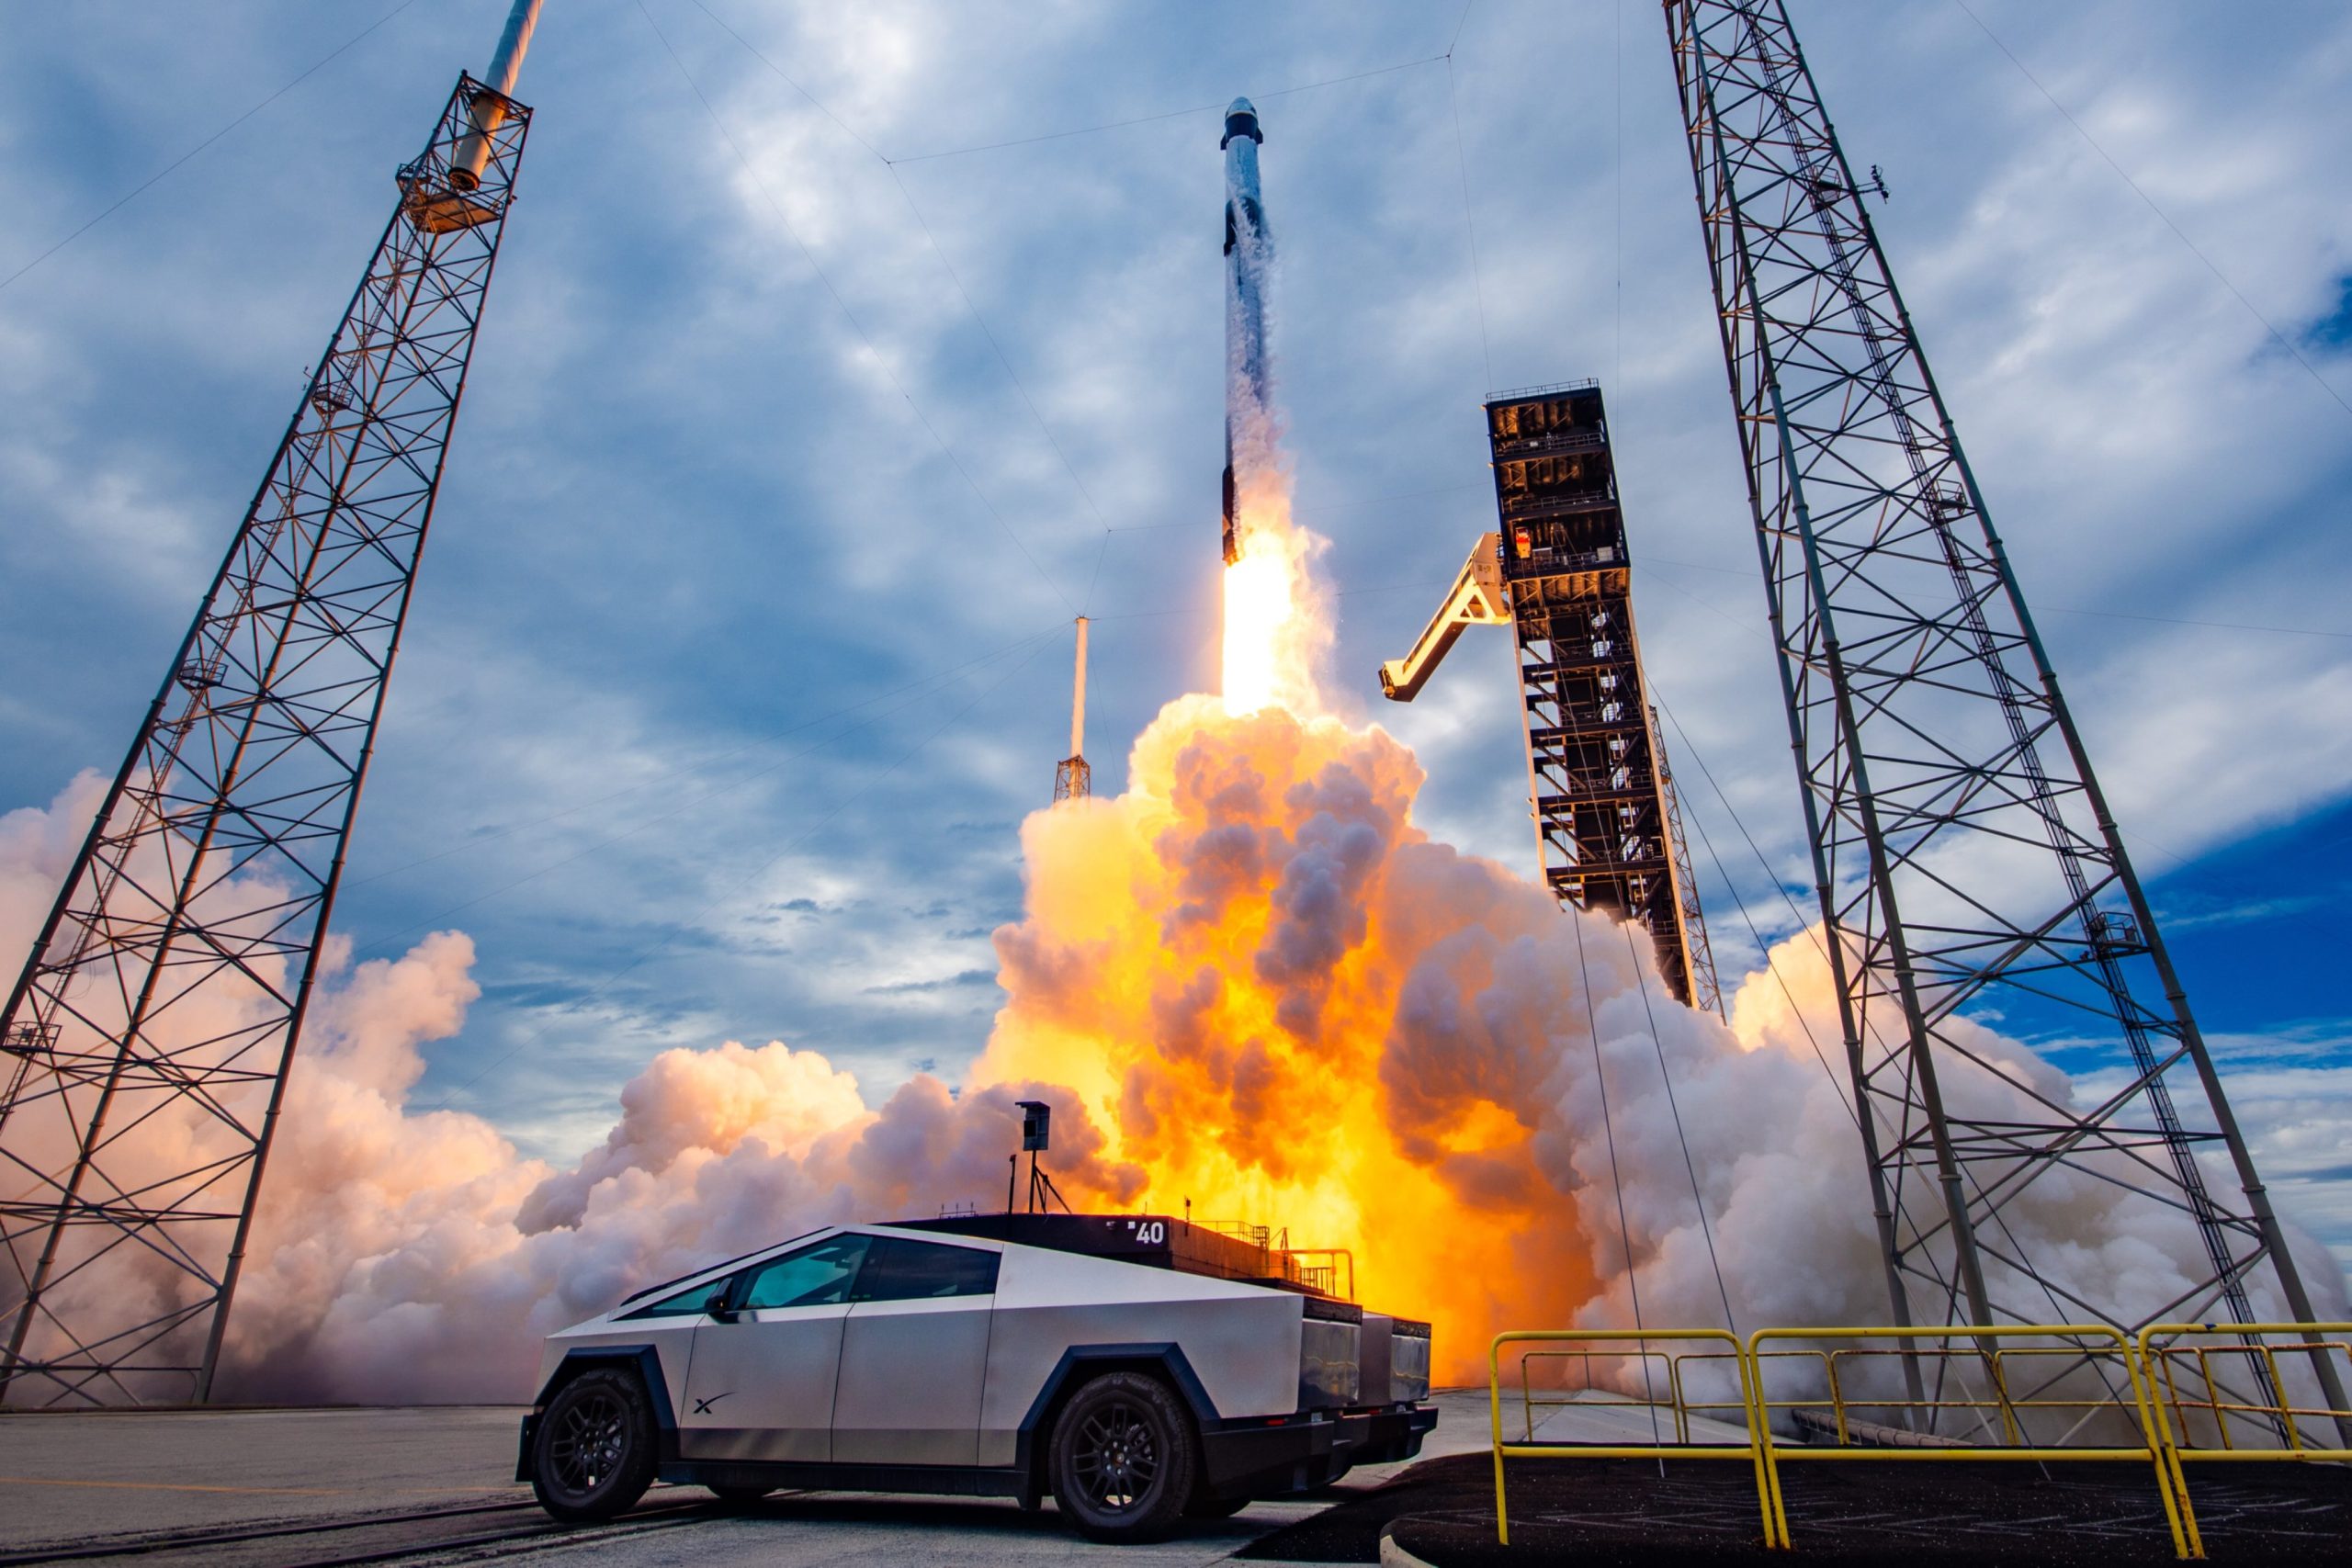
Wall Street analysts rapidly raised price targets on SpaceX (NASDAQ: SPCX) after the company reported a bullish third quarter for 2026 following the market close on October 20. Shares were sent sharply higher in after-hours and premarket trading.
SpaceX posted revenue of $14.6 billion, a 161 percent year-over-year increase that comfortably topped consensus estimates, which fell near $12.7 billion. The company also posted a net profit of $4.4 billion from a prior-year loss, with adjusted EBITDA reaching $8.8 billion.
More price target movement:
🚀 Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
🚀 Barclays raised its target to $300 from $254 (Overweight).
🚀 Citi increased its target to $240 from $200 (Buy),
🚀 UBS moved to $230 from $210 (Buy)
🚀TD Cowen raised its target to $224 from $200 (Buy).
🚀Morgan Stanley held an Overweight rating with a $300 target.
🚀Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.— TESLARATI (@Teslarati) October 21, 2026
Its Super Intelligence (AI) division generated roughly $7.6 billion and became the largest revenue contributor, growing nearly 830 percent year-over-year, while the Connectivity segment delivered $5.2 billion on strong subscriber additions that lifted the consumer base to 13.6 million for Starlink.
The Earnings Call proved especially catalytic, as CEO Elon Musk and CFO Bret Johnsen outlined Q1 2027 revenue guidance of $33 billion to $37 billion, which was far above the roughly $22 billion analysts had modeled, alongside fourth-quarter capital-expenditure plans of $35 billion to $40 billion focused on AI compute infrastructure at sites including Memphis and Southaven.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
Management targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end and discussed pathways to 13 gigawatts or more by the end of 2027. Musk described relentless demand from hyperscalers and other customers, with compute pricing supporting payback periods of less than a year and potentially as short as six months.
Additional highlights included Starship’s recent orbital success and V3 satellite deployment, Starlink pricing and enterprise momentum, rapid Grok Bot adoption, spectrum expansion plans, and the formation of special committees to explore a possible combination with Tesla.
These elements prompted a wave of price-target increases:
- JPMorgan more than doubled its target to $500 from $240 while maintaining an Overweight rating.
- Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
- Barclays raised its target to $300 from $254 (Overweight).
- Citi increased its target to $240 from $200 (Buy),
- UBS moved to $230 from $210 (Buy), and
- TD Cowen raised its target to $224 from $200 (Buy).
- Morgan Stanley held an Overweight rating with a $300 target.
- Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Shares, which closed at $147.79 on October 20, jumped roughly 8 percent in early premarket trading on October 21 as investors digested the results and the newly elevated Street targets.
The average analyst price target has moved higher, which reflects greater conviction in SpaceX’s trajectory across launch, connectivity, and the Super Intelligence business, even as elevated spending remains a point of focus.
Elon Musk
SpaceX showcases exactly how it plans to catch Starship next month
SpaceX played a new Starship Flight 15 simulation showing the ship caught by tower chopsticks.

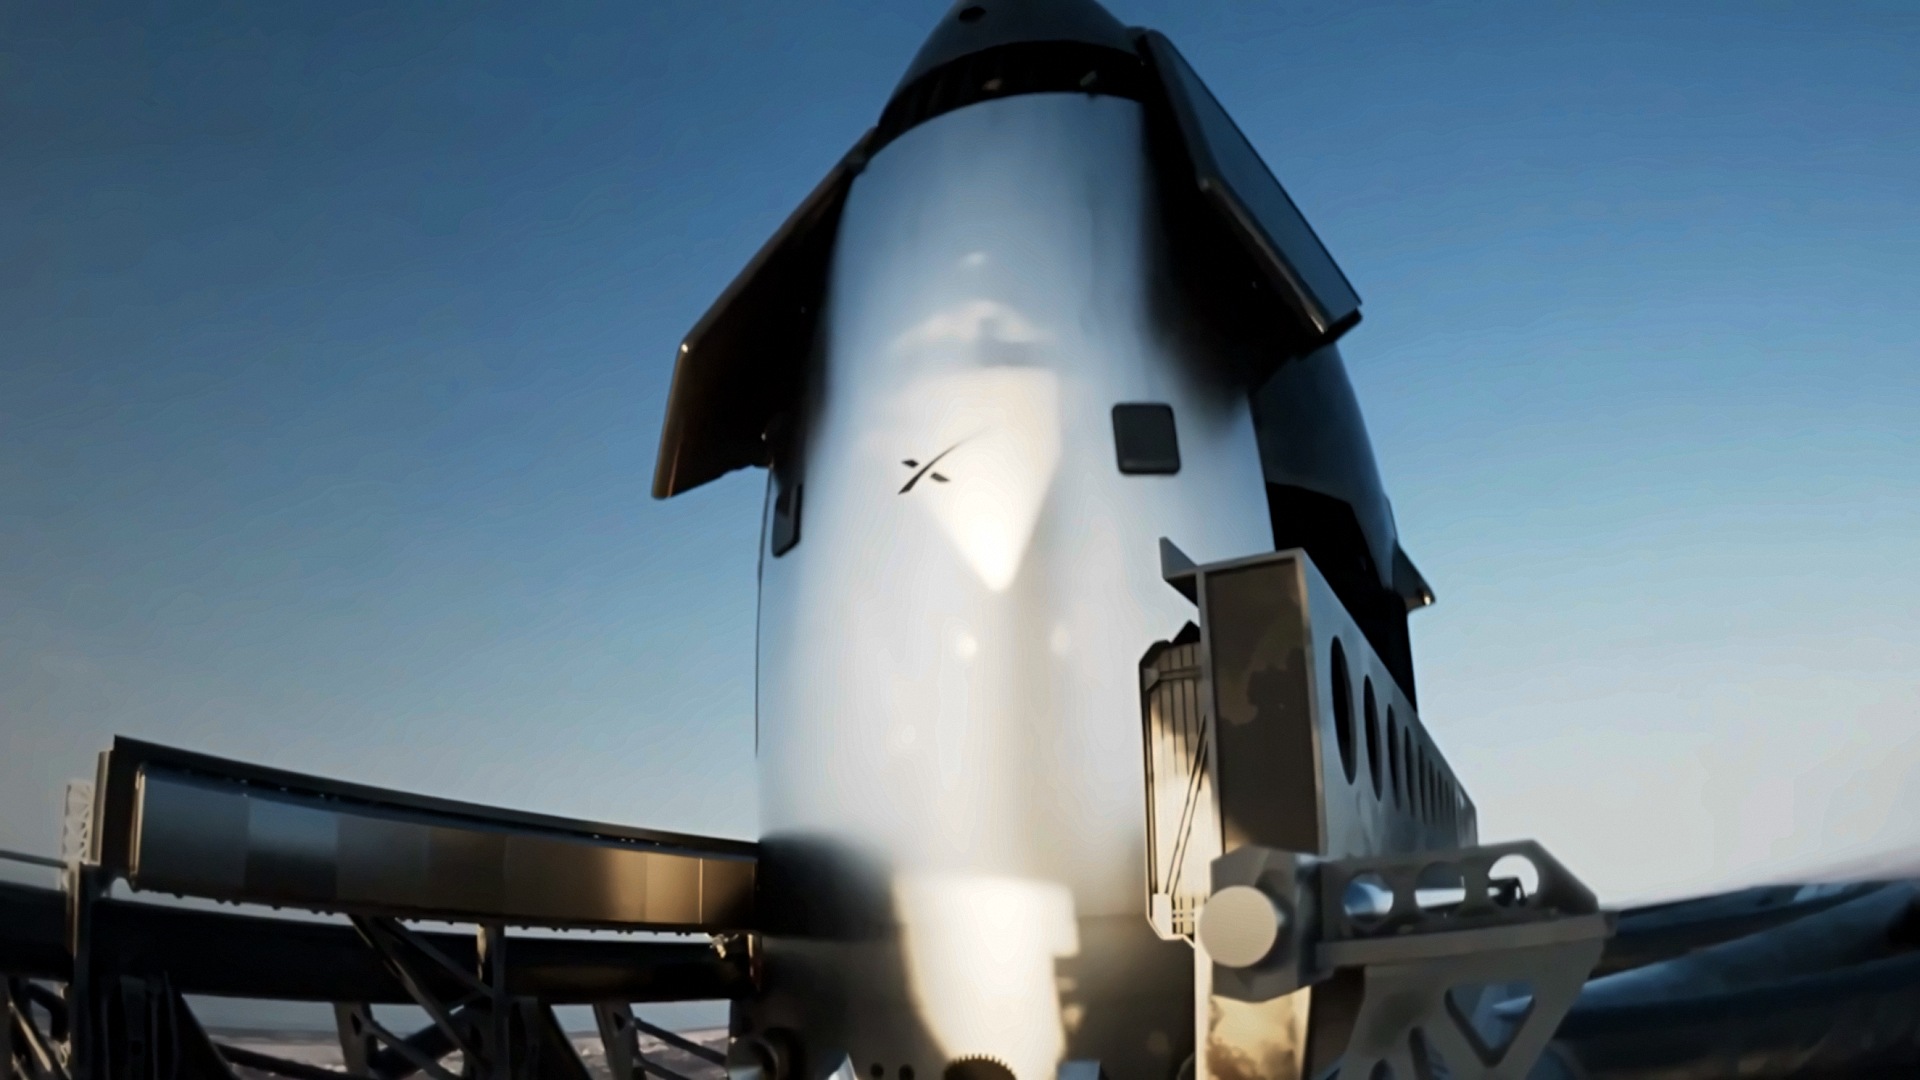
SpaceX gave its clearest look yet at how it plans to catch a Starship upper stage, playing a roughly 80 second animation of the maneuver during its third quarter earnings webcast on Tuesday. The clip ran under an “Up Next: Ship Catch” banner moments after Elon Musk confirmed that Flight 15, expected next month, will try to catch both the Super Heavy booster and the ship with the launch tower.
The animation opens at ground level, looking up through the launch mount at a tower with its chopstick arms spread wide. It then cuts to the ship gliding back through the atmosphere in its horizontal belly flop position, with its forward and aft flaps steering the descent. A wide shot from the Starbase shoreline follows, where the ship is a small dot in the sky before it swings vertical and drops toward the launch towers. The final shots show the ship sliding down past the top of the tower, a close view of the hardware along its side meeting the arms, and the vehicle hanging in the chopsticks.
SpaceX has released a new Starship tower catch animation for the upcoming Flight 15! https://t.co/kStn01Da8u — Truthful🛰️ (@Truthful_ast) October 20, 2026
Musk called the catch the step that closes Starship’s reuse loop. “If we succeed, it will be the first time that an orbital launch vehicle has been fully recovered,” he said. He put the odds of success on the first attempt at “more likely than not,” and said SpaceX has “a steady stream of Starship flight attempts through the end of this year” if Flight 15 falls short.
The sequence mirrors work SpaceX has already done with real hardware. In September, Ship 42, the vehicle assigned to Flight 15, was lifted by the Pad 2 chopsticks into a simulated catch position, where crews cycled the arms and connected the ship quick disconnect arm while it hung from the tower. NASASpaceflight has since reported that SpaceX removed Ship 42’s engines before its static fire and sent it back for another cryogenic test.
Gwynne Shotwell covered the regulatory side on the same call. After what she called “significant constructive engagement with the FAA,” SpaceX expects the Flight 15 license “to include return to launch site and tower catch for both stages.” Bringing the ship home means reentering toward land instead of the open ocean, which Musk said in February would only happen once the chance of the ship breaking up over land was very low, after two perfect soft landings at sea.
SpaceX has caught Super Heavy with the tower three times, on Flights 5, 7 and 8, but the ship returns from orbit at far higher speed and has never been caught. Flight 14 on September 28 was the first Starship to reach orbit, and it deployed 26 Starlink V3 satellites before splashing down, a mission SpaceX counted as its first revenue flight in the Q3 results it reported Tuesday.
The timing lines up with what Musk told the crowd at Giga Texas earlier this month, when he said Flight 15 would probably launch a little before Thanksgiving and that Flight 16 could refly both stages. On Tuesday’s call he went further, saying Starship should fly weekly at some point in the first half of 2027 and twice weekly or more by the end of next year as SpaceX works toward landing a rocket and launching it again with no refurbishment.
Elon Musk
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Tesla and SpaceX formed special committees to weigh a merger, and Elon Musk supports it.
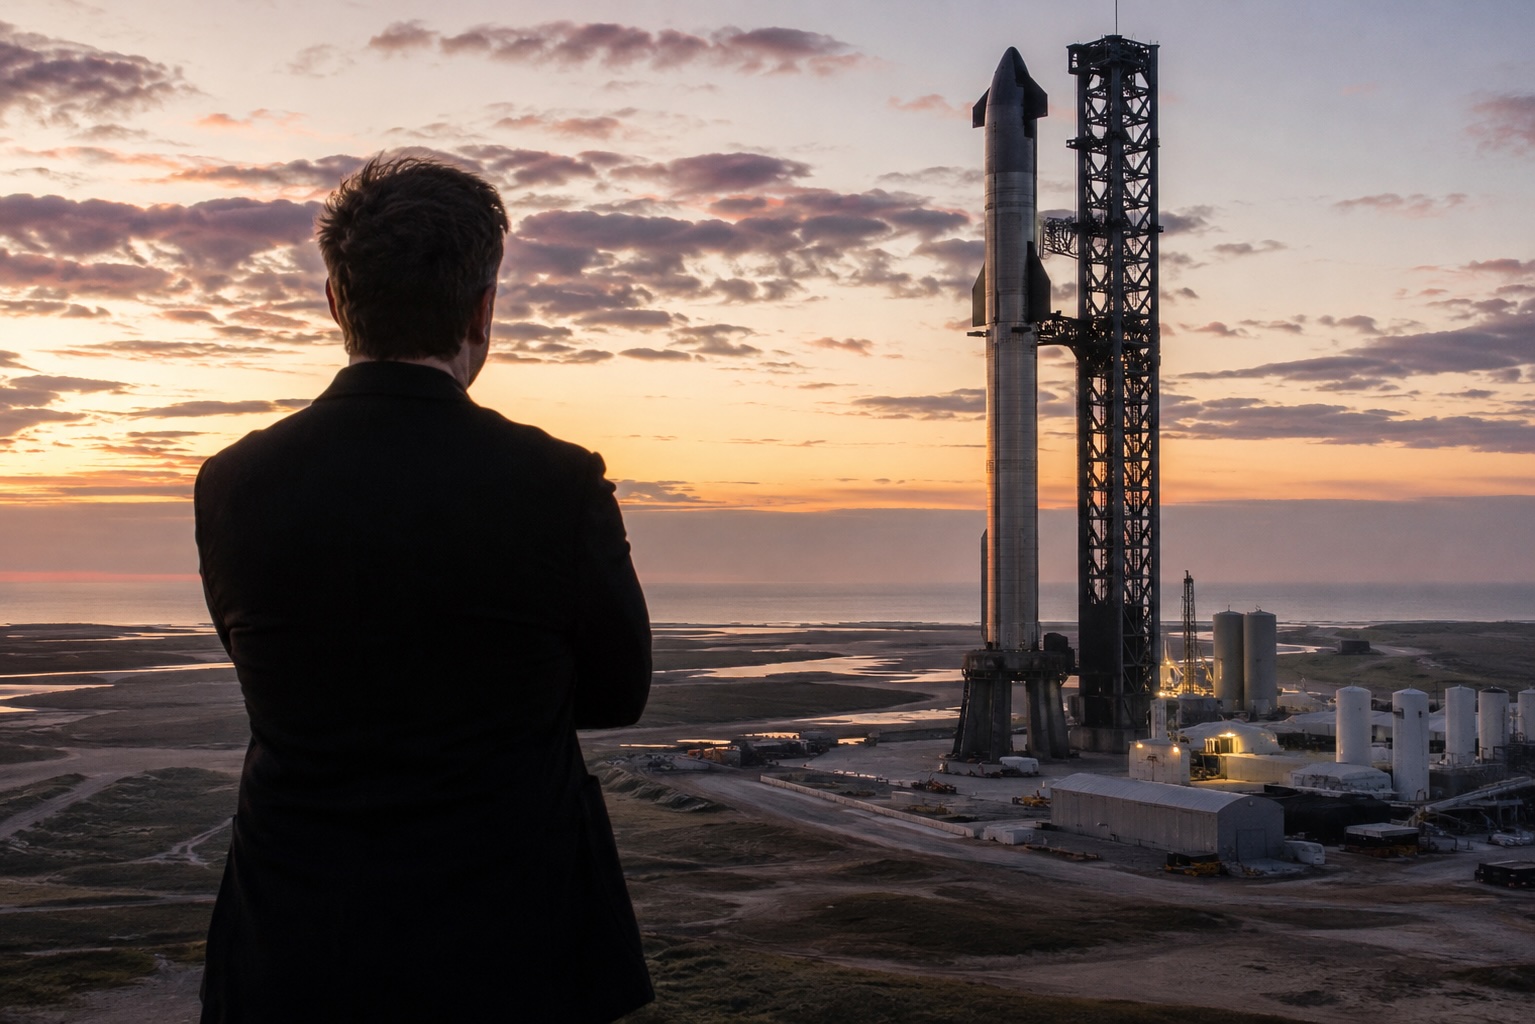
Elon Musk confirmed Tuesday that Tesla and SpaceX have each formed special committees of independent directors to study a possible merger, the first formal step toward combining the two companies after months of speculation.
Musk made the disclosure during SpaceX’s third quarter earnings call. “Both SpaceX and Tesla have formed special committees to discuss this idea at the request of shareholders,” he said. “Because I’m a conflicted party, I can’t actually be in the discussions of the special committees.” He described the setup as “an odd kabuki dance where two groups of people are talking and I can’t be in the conversation.”
Musk did not hide where he stands. “Do I think it would be a good idea? Yes,” he said, pointing to shared work on super intelligence software, chip design, the Terafab facility in Austin, robotics, mass to orbit and connectivity. “I do think there’s a lot of merit to combining the companies as we are pretty much in the super intelligence singularity.”
He also tried to cool expectations. The committees have not agreed on terms for any transaction, and Musk said assuming a merger is a certainty “would be overstating it.” Any deal would go to shareholders, and on the Tesla side it would need approval from 50 percent of all outstanding shares, not just the shares that are voted. Musk called that “quite a high hurdle.”
That bar has tripped Tesla up before. The company’s 2025 attempt to declassify its board won support from only 39.4 percent of outstanding shares and failed. Musk’s own voting stake sits near 20 percent after he exercised his 2018 options in June, so a deal would need broad backing from institutions and a retail base that often leaves votes uncast.
Timing is another open question. Tesla filed its proxy statement Monday for its December 3 annual meeting, and the ballot has only three items: director elections for Musk, Robyn Denholm and JB Straubel, a say on pay vote and auditor ratification. Barclays analyst Dan Levy had argued that an announcement would need to land by late October or early November to make the annual meeting, as Teslarati noted in its SpaceX earnings preview. With no terms agreed, any vote would likely require its own special meeting.
Elon Musk gives his most telling Tesla-SpaceX merger conversation yet
Musk has been edging toward this for weeks. At the All-In Summit in September, he asked “who can imagine what action one might take when there’s so much close collaboration,” Teslarati reported. Last week’s Roadster unveil, built around SpaceX derived cold gas thrusters, pushed the talk further. The two companies already share the Terafab chip project, and Tesla holds a small SpaceX stake that came from its earlier investment in xAI.
SpaceX brought strong numbers to the conversation. It reported Q3 revenue of $14.58 billion, up 161 percent year over year, with its Super Intelligence segment now its largest at $7.56 billion. A higher SpaceX valuation would shape any exchange ratio Tesla holders are offered.
Tesla reports its own third quarter results after the close on Wednesday, October 21. Investors had already ranked merger timing among the top retail questions for SpaceX’s call, and the committees will almost certainly come up again on Tesla’s.

SpaceX stock gets a slew of price target boosts after bullish earnings call

SpaceX showcases exactly how it plans to catch Starship next month

Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


