Investor's Corner
Tesla stock (TSLA) one week after Q2 2016 Report

Post Q2 Report Action
As we previously reported, the Q2 quarterly results were “mixed”:
- Revenue matched expectation, a positive for Wall Street;
- Earning losses were higher than anticipated, a negative, but for a company like Tesla, where the stock price is based on future expectations, the earning numbers are really not what counts;
- Slightly increasing gross margins, a positive;
- Practically zero ZEV credits for the quarter, a negative;
- Production and demand on track to support 50,000 deliveries in 2H 2016, a positive;
- Lower production numbers than previously anticipated, a negative.
When you have such a mix of positives and negatives, it is fairly normal for traders to have a “subdued” response, unlike the usually wild responses to results that are big misses or big beats on expectations.
Accordingly, this time around the technical response of the stock market to last week’s Tesla Q2 2016 report has been “muted.” The stock has been in “compression” (a horizontal back and forth) since the report, staying in the $225-$230 range, but overall 12-month Analyst Price Targets have actually decreased with the average dropping from $277 to $244.
Looking at more details of the reactions to the report, this is a small sample from Top Analysts, noting that none of them changed their position.
Alexander Potter of Piper Jaffray says “Teslas untouchable brand helps investors look past million-dollar losses.”
“It’s hard to recommend a cash-burning company with such an uncertain outlook,” said Potter, who reiterated a neutral rating and $223 price target on the stock. But consumers and investors still seem captivated by Tesla’s products, said Potter. And as long as the company “retains this aura,” its stock multiple will “probably stay buoyant,” he said.
Brad Erickson of Pacific Crest says “The risks still outweigh the rewards.”
“Brad rattled off a number of challenges Tesla still needs to tackle in a note to clients. But he reiterated a sector weight rating on the stock, said Tesla’s cash burn wasn’t as bad as expected during the quarter, and maintained the belief that the company’s longer-term vision is “second to none.”
Ben Kallo of Robert W. Baird says “Focus [is] on Tesla (TSLA) Production Ramp and Long Term Goals, Not Q2 Miss.”
Kallo commented, “Q2 revenue was in line with our estimate, but TSLA missed on EPS with higher-than-expected OPEX. Additionally, gross margin missed consensus estimates and was pressured during the quarter with the Model S refresh and X ramp, but automotive gross margin improved sequentially, which was better than we expected. Importantly, TSLA reaffirmed its 2H:16 delivery target of ~50k vehicles, expects margins to ramp in 2H:16 given higher manufacturing efficiency, and the Model 3 remains on track for 2H:17 production.”
Kallo also covers SolarCity (SCTY) and he commented that “Although SCTY has a 45-day go-shop period which could provide additional upside, we believe it is highly likely the TSLA and SCTY merger will go through, and we are moving to the sidelines.”
Colin Rusch of Oppenheimer “noted that Tesla appears to be taking on increasing responsibility when it comes to technology development.”
“Rusch wasn’t surprised by Tesla’s quarter, and the firm remains on the sidelines until Tesla can show some progress toward profitability. It also appears to have taken a hard line with suppliers on timelines, pricing and allocation of resources,” he explained. “While we see potential benefits, we note increasing risk on supplier pushback.”
Ryan Brinkman of J.P. Morgan noted that “JPMorgan cuts Tesla estimates on higher operating expenses.”
“To reflect lower revenue and higher operating expenses following the company’s Q2 results, Brinkman cut his 2016 earnings per share estimate for Tesla to (32c) from $1.60. The analyst notes his 2016 earnings estimate was $4.62 a year ago and $2.74 at the start of this year. This reflects the “degree of consistent ratcheting down of near-term earnings,” Brinkman tells investors in a post-earnings research note. The analyst keeps an Underweight rating on Tesla with a $180 price target.”
Shelby Seyrafi of FBN Securities “reiterated a Buy rating on Tesla Motors (NASDAQ: TSLA), with a price target of $275.”
Seyrafi is a 3-star analyst with an average return of 0.5% and a 51.5% success rate. Seyrafi covers the Technology sector, focusing on stocks such as Hewlett Packard Enterprise, Dot Hill Systems Corp., and Concur Technologies.
Colin Langan of UBS, says “Tesla, SolarCity synergies still cloudy.”
“Colin noted Tesla announced details of its agreement to acquire SolarCity (SCTY) and provided synergy targets with the deal. UBS said they remain cautious on the deal given the lack of compelling synergies and the fact the deal is an unneeded distraction for Tesla management, which already faces challenges with its Model 3 launch and production targets. UBS maintained its Sell rating and $160 price target on Tesla shares.”
The overall consensus of analysts covering Tesl Motors, reported at tipranks.com, is neutral (hold).
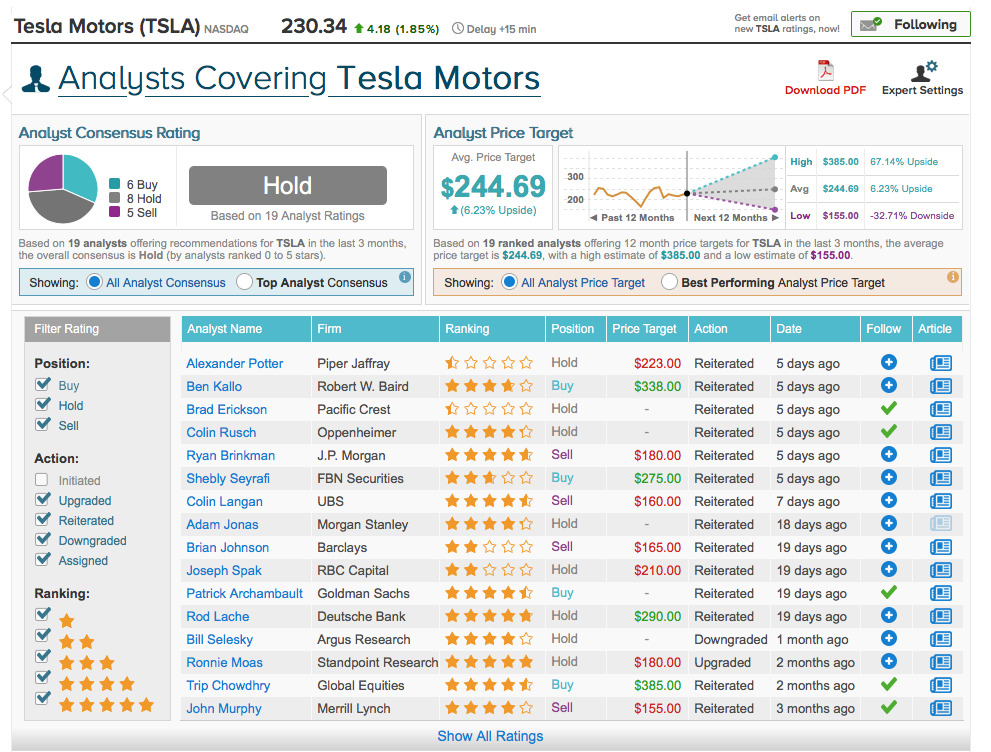
Source: TipRanks
Trade Analysis
Quarterly Reports are usually the catalyst that start or stop actions for swing traders. The Q2 report was no different. I called for a bullish swing trade when the MACD crossed to the bulls on July 1st. The trade closed on August 4th when the MACD crossed to the bears, the day after the Q2 report was released. This was a good trade that gained over $14 in about a month period to traders that went long on the stock (see the shaded band in the chart below). For option traders this was a “fabulous” trade.
A week after the report the market is undecided on what to do with TSLA in the short term. All indicators are “neutral”: the stock has gone sideways for a week; the MACD averages are flat and overlapping; the MACD itself is at zero; both the 50-day moving average (the red line in the chart below) and the 200-day moving average (the yellow line in the chart below) are flat. All of these indicators are showing the absence of a trend. Trading in these conditions is not advisable and fairly risky. I’m personally out of trading TSLA until a trend appears.
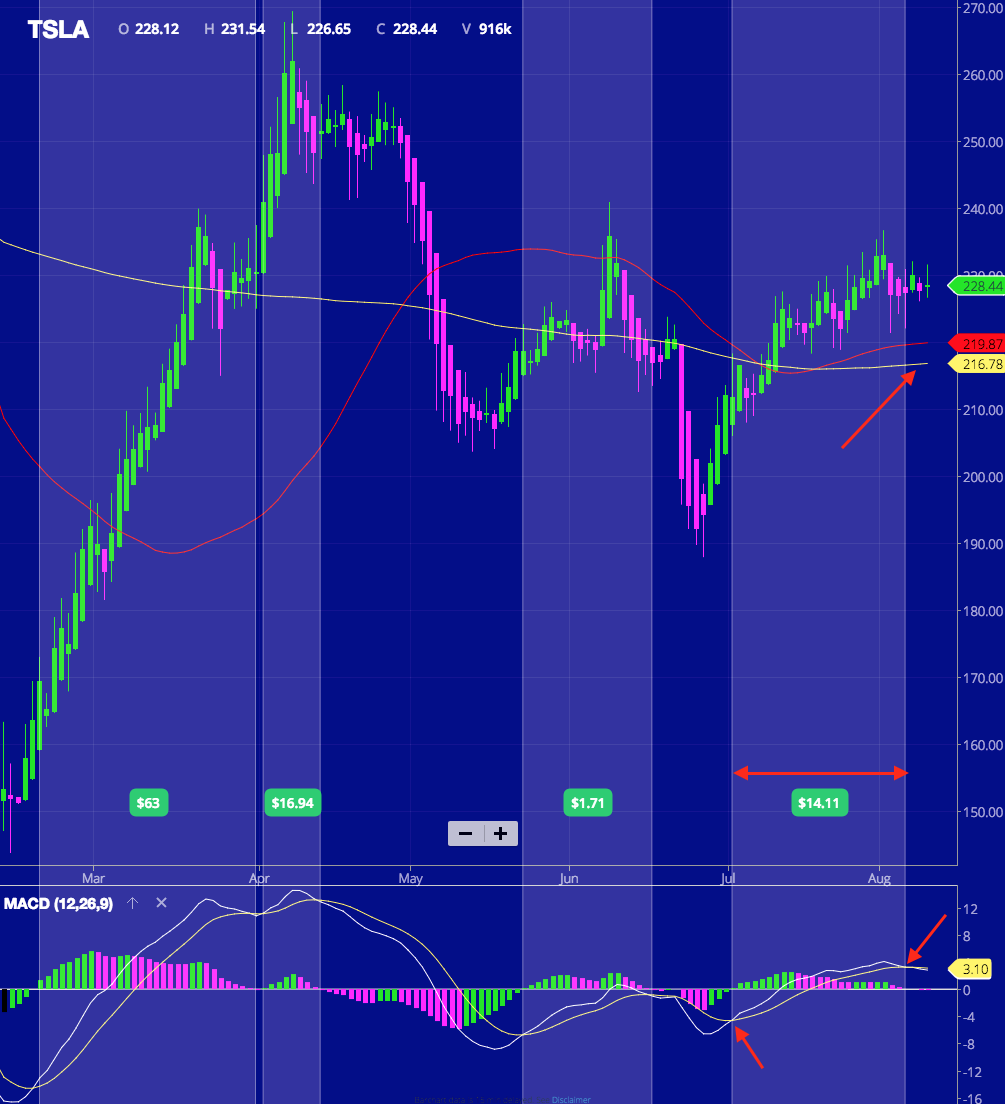
Source: Wall Street I/O

Elon Musk
X changed how everyone gets paid, and this lawsuit shows why
X sued a Bitcoin account network over fake payouts as its creator pay model shifts

Elon Musk’s X has taken a Bitcoin-focused engagement ring to court, and the case doubles as a receipt for how differently the platform pays creators today. The company filed suit in the High Court of England and Wales against Vivek Kumar Sen and Zamyang Sherpa, alleging the pair ran six accounts, including @Vivek4real_, @Bitcoin_Teddy and @TrendingBitcoin, as one coordinated operation to fake the kind of engagement that used to translate directly into money.
According to the filing, first reported by Gizmodo, the accounts posted near identical “BREAKING” crypto headlines seconds apart, in one case 11 seconds, then had three more handles like, reply to and repost the material to manufacture what X called “a false appearance of genuine, human communication and interaction.” X says the scheme pulled in at least £207,384, about $278,000, and pegs its own investigation and remediation costs at another £75,000. The accounts were suspended August 18. X general counsel James Burnham announced the case on X last weekend, writing that the company “will act forcefully to protect our platform and the earnings of genuine creators.” Musk’s own reaction, posted shortly after, was three words: “Don’t mess with 𝕏.”
Don’t mess with 𝕏 https://t.co/HSmd5hL6aQ
— Elon Musk (@elonmusk) September 21, 2026
The timing lines up with a a recent update to how X pays its creators. The program these accounts allegedly gamed, Creator Revenue Sharing, launched in mid 2023 and paid out based on how much a post got engaged with. Originality was never part of the formula, which is exactly how the platform ended up flooded with recycled clips, copy pasted “BREAKING” posts and replies engineered purely to farm reactions from paying subscribers.
X tried patching the model more than once, including an April cut to aggregator payouts and a March regional weighting change that Musk personally paused hours after it was announced. X retired Creator Revenue Sharing for good on September 7 and opened its replacement, Original Content Rewards, the next day.
Today, we’re launching Original Content Rewards.
The reality is that Revenue Sharing had reached a point where its incentives were misaligned. Creators should be focused on bringing net new content to the platform instead of maximizing payouts. We could have kept adding more… pic.twitter.com/VJIxqlPrjm
— Allegra Jacchia (@allegrajacchia) August 7, 2026
The new math is stricter. Payouts now come only from qualified impressions, meaning unique Home Timeline views from Premium subscribers where at least half the post is visible, and replies no longer count toward eligibility at all. Copied posts, reuploaded media and reposts without meaningful changes are explicitly excluded. Allegra Jacchia, senior product manager for Creators at SpaceXAI, which now runs X’s product and AI work following xAI’s acquisition of the platform, put it bluntly, saying the goal is to reward creators who bring original ideas and perspective, “not those who have become best at gaming the system.”
Read that way, the lawsuit isn’t really about six crypto accounts. It’s X putting a dollar figure on what the old incentive structure cost, then suing to collect it right as the new one goes live. For live updates on how the case and the new rewards program shake out, follow @Teslarati on X.
Elon Musk
Why automakers keep turning down Elon Musk’s Tesla Full Self-Driving offer
Elon Musk confirms no automaker has ever accepted Tesla’s offer to license Full Self-Driving software.
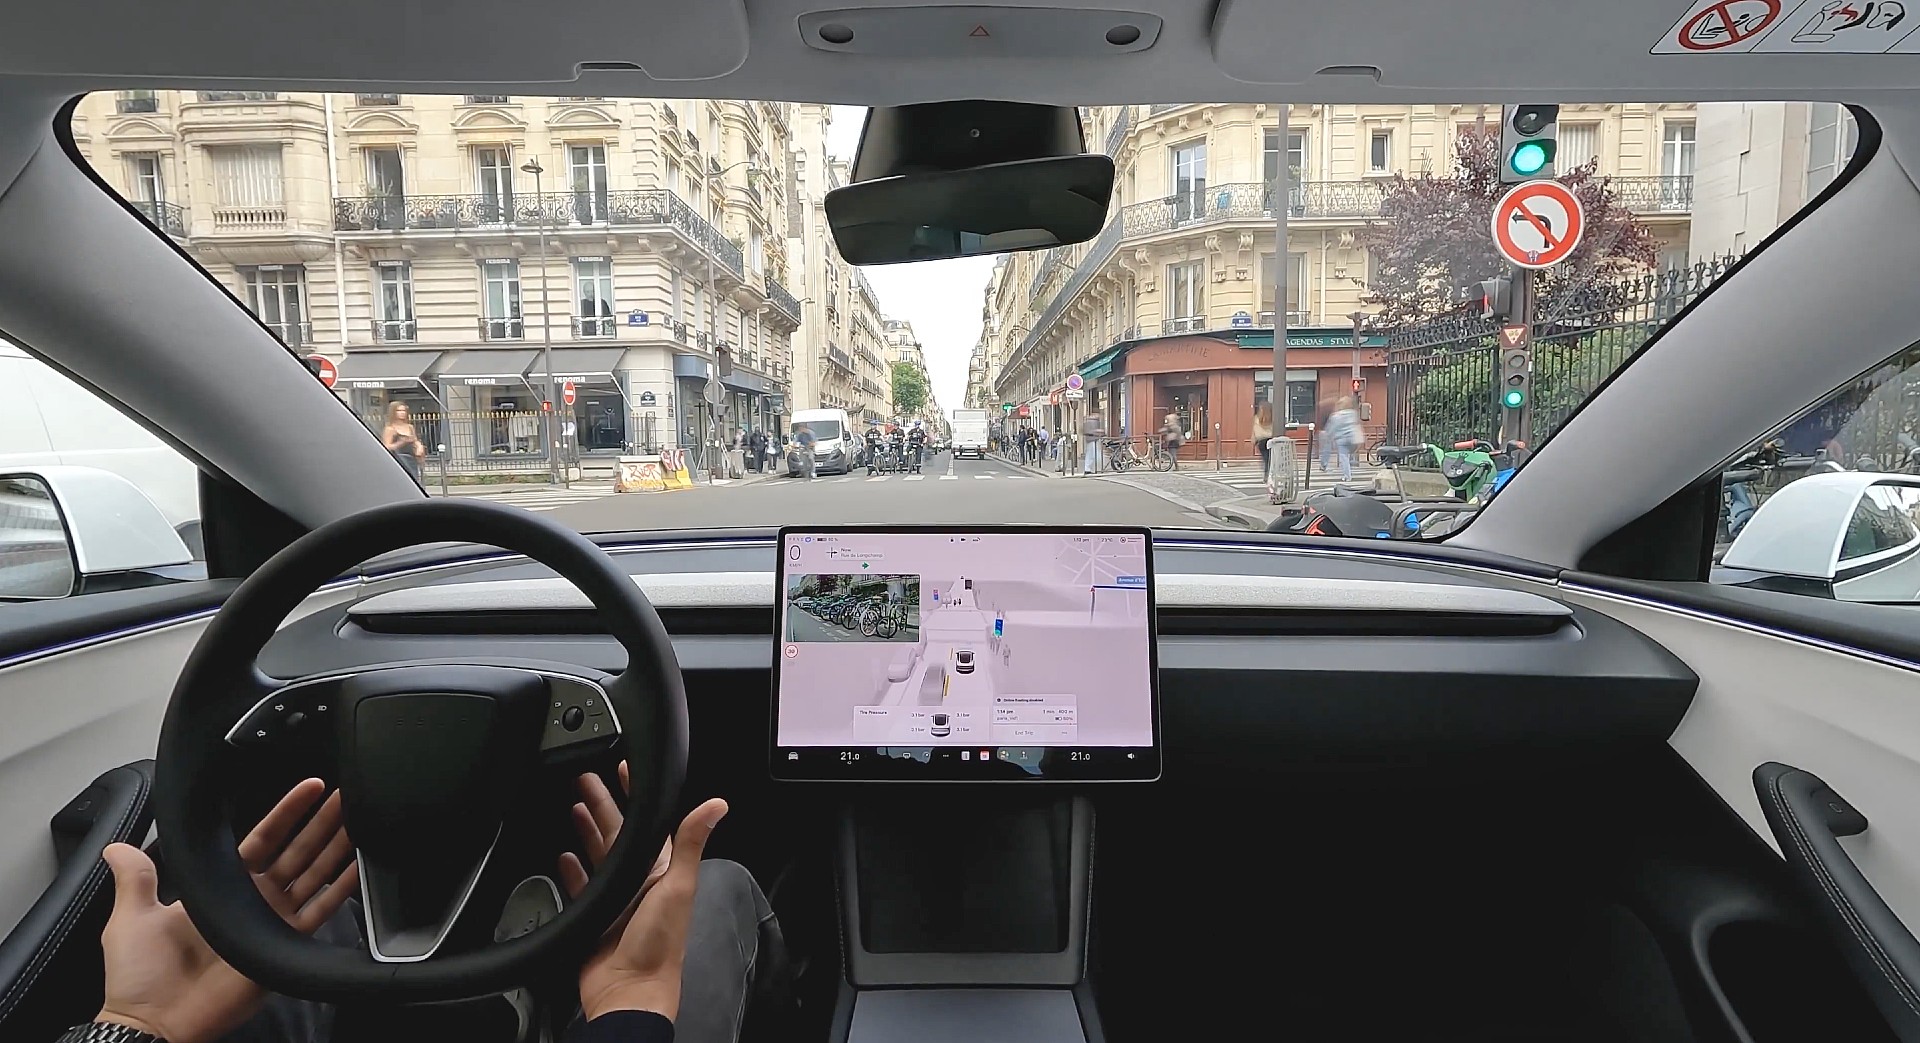
Elon Musk gave a brief answer on X Monday that confirmed that Tesla’s standing offer to license Full Self-Driving to other automakers still has zero takers. Sawyer Merritt wrote that “Tesla has for years openly invited other automakers to license FSD. None of them have accepted,” responding to a prediction from Boom Supersonic founder Blake Scholl that Tesla would eventually open FSD the way it opened its Supercharger network to rival brands. Musk’s reply to Merritt was one word: “Exactly.”
It is not the first time Musk has made this point. He said something similar in November, when he called legacy automakers reluctance to adopt FSD “crazy,” and Tesla has floated the offer publicly since at least 2021. Scholl’s prediction touches on something real. Once NACS became the de facto charging standard, adoption from Ford, GM, Rivian and others followed within about a year. FSD licensing was supposed to work the same way once Tesla built enough of a lead that switching made sense for everyone.
Tesla has for years openly invited other automakers to license FSD. None of them have accepted. https://t.co/kgz4idpoUM
— Sawyer Merritt (@SawyerMerritt) September 22, 2026
The case for licensing now is stronger than it was two years ago. Waymo and Zoox are logging hundreds of thousands of unsupervised autonomous miles, along with Tesla’s own Robotaxi fleet. Every automaker still selling driver assist systems that lag FSD has given the robotaxi conversation to Tesla, Waymo and Zoox by default. Licensing FSD would let a GM or a Ford compete on the same field without spending a decade and billions of dollars building a stack from scratch, the same argument Tesla made when it opened the Supercharger network to bring more EVs onto its chargers.
But FSD is not a connector standard. As one reply to Musk’s post pointed out, licensing FSD is not a software license the way NACS was a plug spec. It requires adopting Tesla’s eight camera layout and its onboard compute architecture, meaning a licensee’s cars would effectively become Tesla hardware wearing someone else’s badge. That is the visible obstacle. The less visible one is data. A licensed FSD stack would report back the same telemetry Tesla collects from its own fleet, giving Tesla a continuous read on how a competitor’s cars are actually driven, where they struggle, and how often drivers intervene. For an automaker trying to build its own autonomy program, or simply trying to keep its build quality and safety record private, handing Tesla that visibility could be a bigger cost than the hardware bill. It is the reason the Supercharger comparison only goes so far. Opening a charging plug cost Tesla very little. Opening FSD would cost a rival something it cannot get back.
Elon Musk
Tesla eyes supply partners for Optimus mass production
Tesla certified three Chinese suppliers for Optimus mass production, signaling its robot timeline is accelerating.
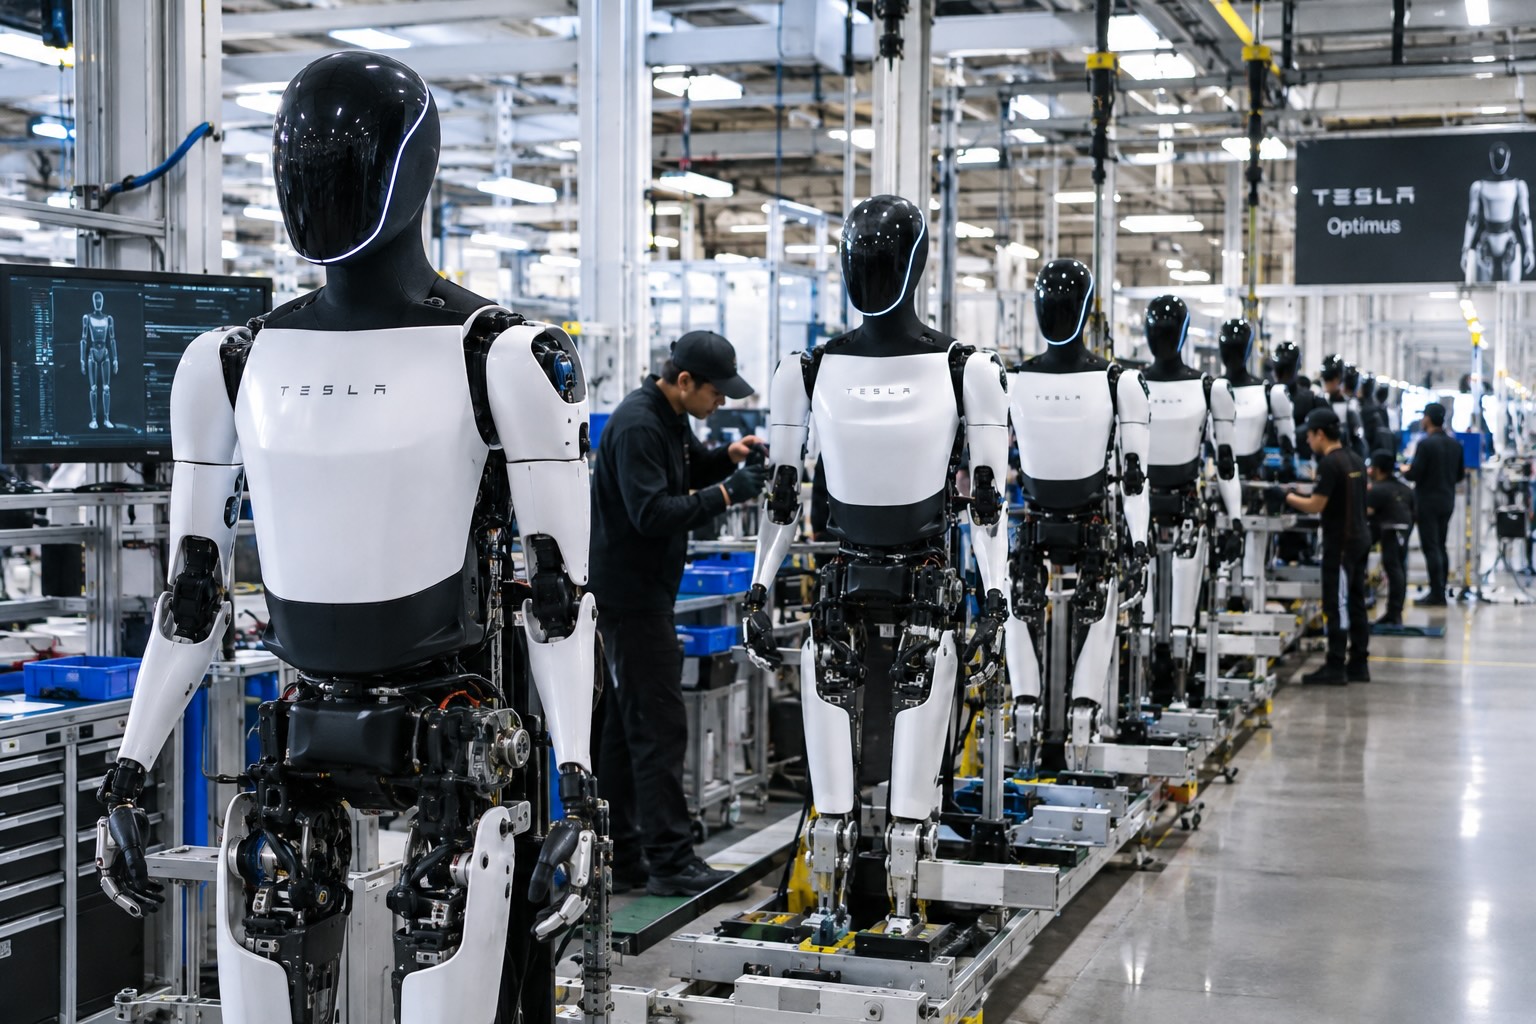
Tesla’s robotics team traveled to Ningbo, in China’s Zhejiang province, on September 16 and spent the following day auditing component suppliers for Optimus, according to a Bloomberg report cited by RobotAIGeek. The visit moved three manufacturers from provisional status to certified mass production partners: Tuopu Group, which handles actuators and chassis components, Ningbo Joyson Electronic, a sensor supplier, and Zhejiang Sanhua Intelligent Controls, which builds thermal management systems. All three already supply parts to Tesla’s electric vehicles, and the audit reportedly came with fresh orders that supply chain reports put at an initial batch of roughly 5,000 units.
Tuopu, Joyson, and Sanhua built their manufacturing base serving the automotive industry, where tolerances and volume requirements are already close to what a mass produced humanoid robot demands. Sanhua in particular has history here. Teslarati reported last October that the company had received a roughly $685 million order for linear actuators tied to Optimus, a volume industry watchers estimated could cover around 180,000 robots once production ramped.
Supply chain reports tied to this week’s audit put Tesla’s near term production goal at about 1,000 Optimus units a week by late September, rising to 2,000 to 2,500 units a week by the end of the year. That pace would put real weight behind the timeline Tesla has been building toward since May, when it wound down Model S and Model X production at Fremont to convert that floor space into a dedicated Optimus line targeting one million units annually. JPMorgan analysts who toured the factory in August confirmed the conversion took roughly four months, a pace Musk has called unprecedented for a facility that size.
New drone video shows Tesla’s Optimus Factory reaching a turning point
Fremont is only the first phase. A second, larger Optimus plant is rising at Gigafactory Texas, where drone footage shared by Joe Tegtmeyer last week showed the structural steel nearing completion on the north end of the building. Tesla has said that facility is meant to eventually support production of up to 10 million units a year, though volume output there is not expected before 2027.
Commercial sales of Optimus are still targeted for the second half of 2027, but production is expected to start well before then. JPMorgan analyst Rajat Gupta has said Tesla’s “Optimus Academy” program, which uses early units to collect real world training data inside Tesla’s own facilities, is expected to be running later this year. Bloomberg Intelligence analyst Ian Ma described the Ningbo audits as “a positive commercialization signal for China’s humanoid supply chain,” noting that sentiment could improve further if the visit leads to confirmed supplier nominations and larger orders. The Solactive China Humanoid Robotics Index rose about 1.4% on the news, though it remains down roughly 30% for the year.

Tesla Semi lands the biggest electric truck deal in U.S. history

Tesla integrates Grok Bot into its vehicles for the ultimate personal assistant


