
Tesla (NASDAQ:TSLA) took a steep dive on the heels of the company’s Q4 and FY 2023 earnings call, dropping over 9% as of writing. With the company stating that volume growth would be tempered this year due to its focus on the next-generation platform and executives being quite vague about its guidance for 2024, analysts, including some TSLA bulls, are not happy.
Tesla actually had a record 2023, with vehicle sales growing nearly 40% year-over-year in 2023 to over 1.8 million units worldwide. Wall Street currently expects Tesla to post about 2.1 to 2.2 million vehicle sales for 2024, which would translate to a growth of about 20%. This number seems conservative and attainable enough, but Tesla simply maintained that its volume growth would be substantially lower than 2023’s ~40%.
Wedbush analyst Dan Ives shared his sentiments about Tesla’s earnings call, in a post on X. Ives described the call, which provided some high-level long-term views on the company, as another “train wreck” conference call. Following the earnings call, Ives adjusted his price target for Tesla from $350 to $315 per share, though he also noted that Wedbush remains bullish on the company.
Great to join @bsurveillance discussing another train wreck conf call in our view from Tesla and Musk lacking margin outlook and firm guidance for 24. Remain bullish for long term EV/AI vision but near term headwinds @lisaabramowicz1 @FerroTV @annmarie @BloombergTV https://t.co/E40CMG2Mg0— Dan Ives (@DivesTech) January 25, 2024
“We were dead wrong expecting Musk and team to step up like adults in the room on the call and give a strategic and financial overview of the ongoing price cuts, margin structure, and fluctuating demand. Instead, we got a high-level Tesla long-term view with another train wreck conference call,” Ives noted.
RBC analyst Tom Narayan also maintained his “Buy” rating on Tesla, though he lowered his price target from $300 to $297 per share. “We leave our delivery estimates unchanged after the vague guide, but lower our car gross margin expectations on less robust cost down opportunity,” he noted in a report. Narayan also pointed out that Tesla’s next-generation vehicle platform is still “many quarters away” from impacting the company’s numbers.
New $TSLA report from Adam Jonas: 5 thoughts post earnings call
“We reiterate our OW $TSLA rating ($345 price target) which offers over 80% upside from current levels which we believe is compelling in proportion to the investment level within our US auto coverage.” pic.twitter.com/TdZ2cLavdc— Sawyer Merritt (@SawyerMerritt) January 25, 2024
Morgan Stanley’s Adam Jonas, for his part, pointed out that Tesla almost did not provide any guidance during the call. He also observed that there were no “AI rabbits” pulled out of Tesla’s hat during the call, which was highlighted by Musk’s conservative comments about Dojo. Despite this, Morgan Stanley opted to maintain its “Overweight” rating and $345 price target on Tesla, with a bear case PT of $100 and a bull case PT of $500 per share.
While the sentiments surrounding Tesla’s Q4 and FY 2023 earnings call seem generally negative, some analysts opted to take a more optimistic stance on the company. Canaccord lowered its price target for Tesla from $267 to $234 per share, though the firm also noted that it is time for investors to be patient about the company. The firm noted that it remains bullish about Tesla’s long-term prospects.
NEWS: Canaccord Genuity has lowered its $TSLA price target to $234 (from $267), maintains a BUY rating.
They put out a good note:
“It’s time to be patient. The next-generation vehicle, FSD upgrades, margin improvement, and Optimus will likely bring an acceleration in revenue…— Sawyer Merritt (@SawyerMerritt) January 25, 2024
“It’s time to be patient. The next-generation vehicle, FSD upgrades, margin improvement, and Optimus will likely bring an acceleration in revenue growth. But not this year — 2024 will be subdued; probably a trough, but still relatively slow (we model ~18% y\y revenue growth). Growth curves are seldom smooth, and Tesla is no different.
“We are still quite bullish on Tesla’s long-term growth prospects. We think EVs will replace ICE vehicles despite recent countervailing narratives. We see vehicle autonomy as one of the highest value-creating technologies to be deployed. Ever. And Tesla, with its razor/ razorblade approach, is a leader in this real-world AI. We think Tesla is Apple on steroids as it focuses on manufacturing and a higher level of vertical integration. Tesla is THE sustainability behemoth, in our opinion,” the firm noted.
The critical metric, auto gross margins ex credits, came in at 17%, compared to the Street at 17.3%. I was expecting 16.7%.
While this missed the Street, it marks the end of four consecutive quarters of margin decline, up from 16.3% in the Sep-23.
Over this is a positive.— Gene Munster (@munster_gene) January 24, 2024
Longtime Tesla bull Gene Munster of Deepwater Asset Management also pointed out that Tesla’s auto gross margins for the past quarter ended a streak of dropping margins. “The critical metric, auto gross margins ex credits, came in at 17%, compared to the Street at 17.3%. I was expecting 16.7%. While this missed the Street, it marks the end of four consecutive quarters of margin decline, up from 16.3% in the Sep-23. Over, this is a positive,” Munster wrote on X.
Don’t hesitate to contact us with news tips. Just send a message to simon@teslarati.com to give us a heads up.


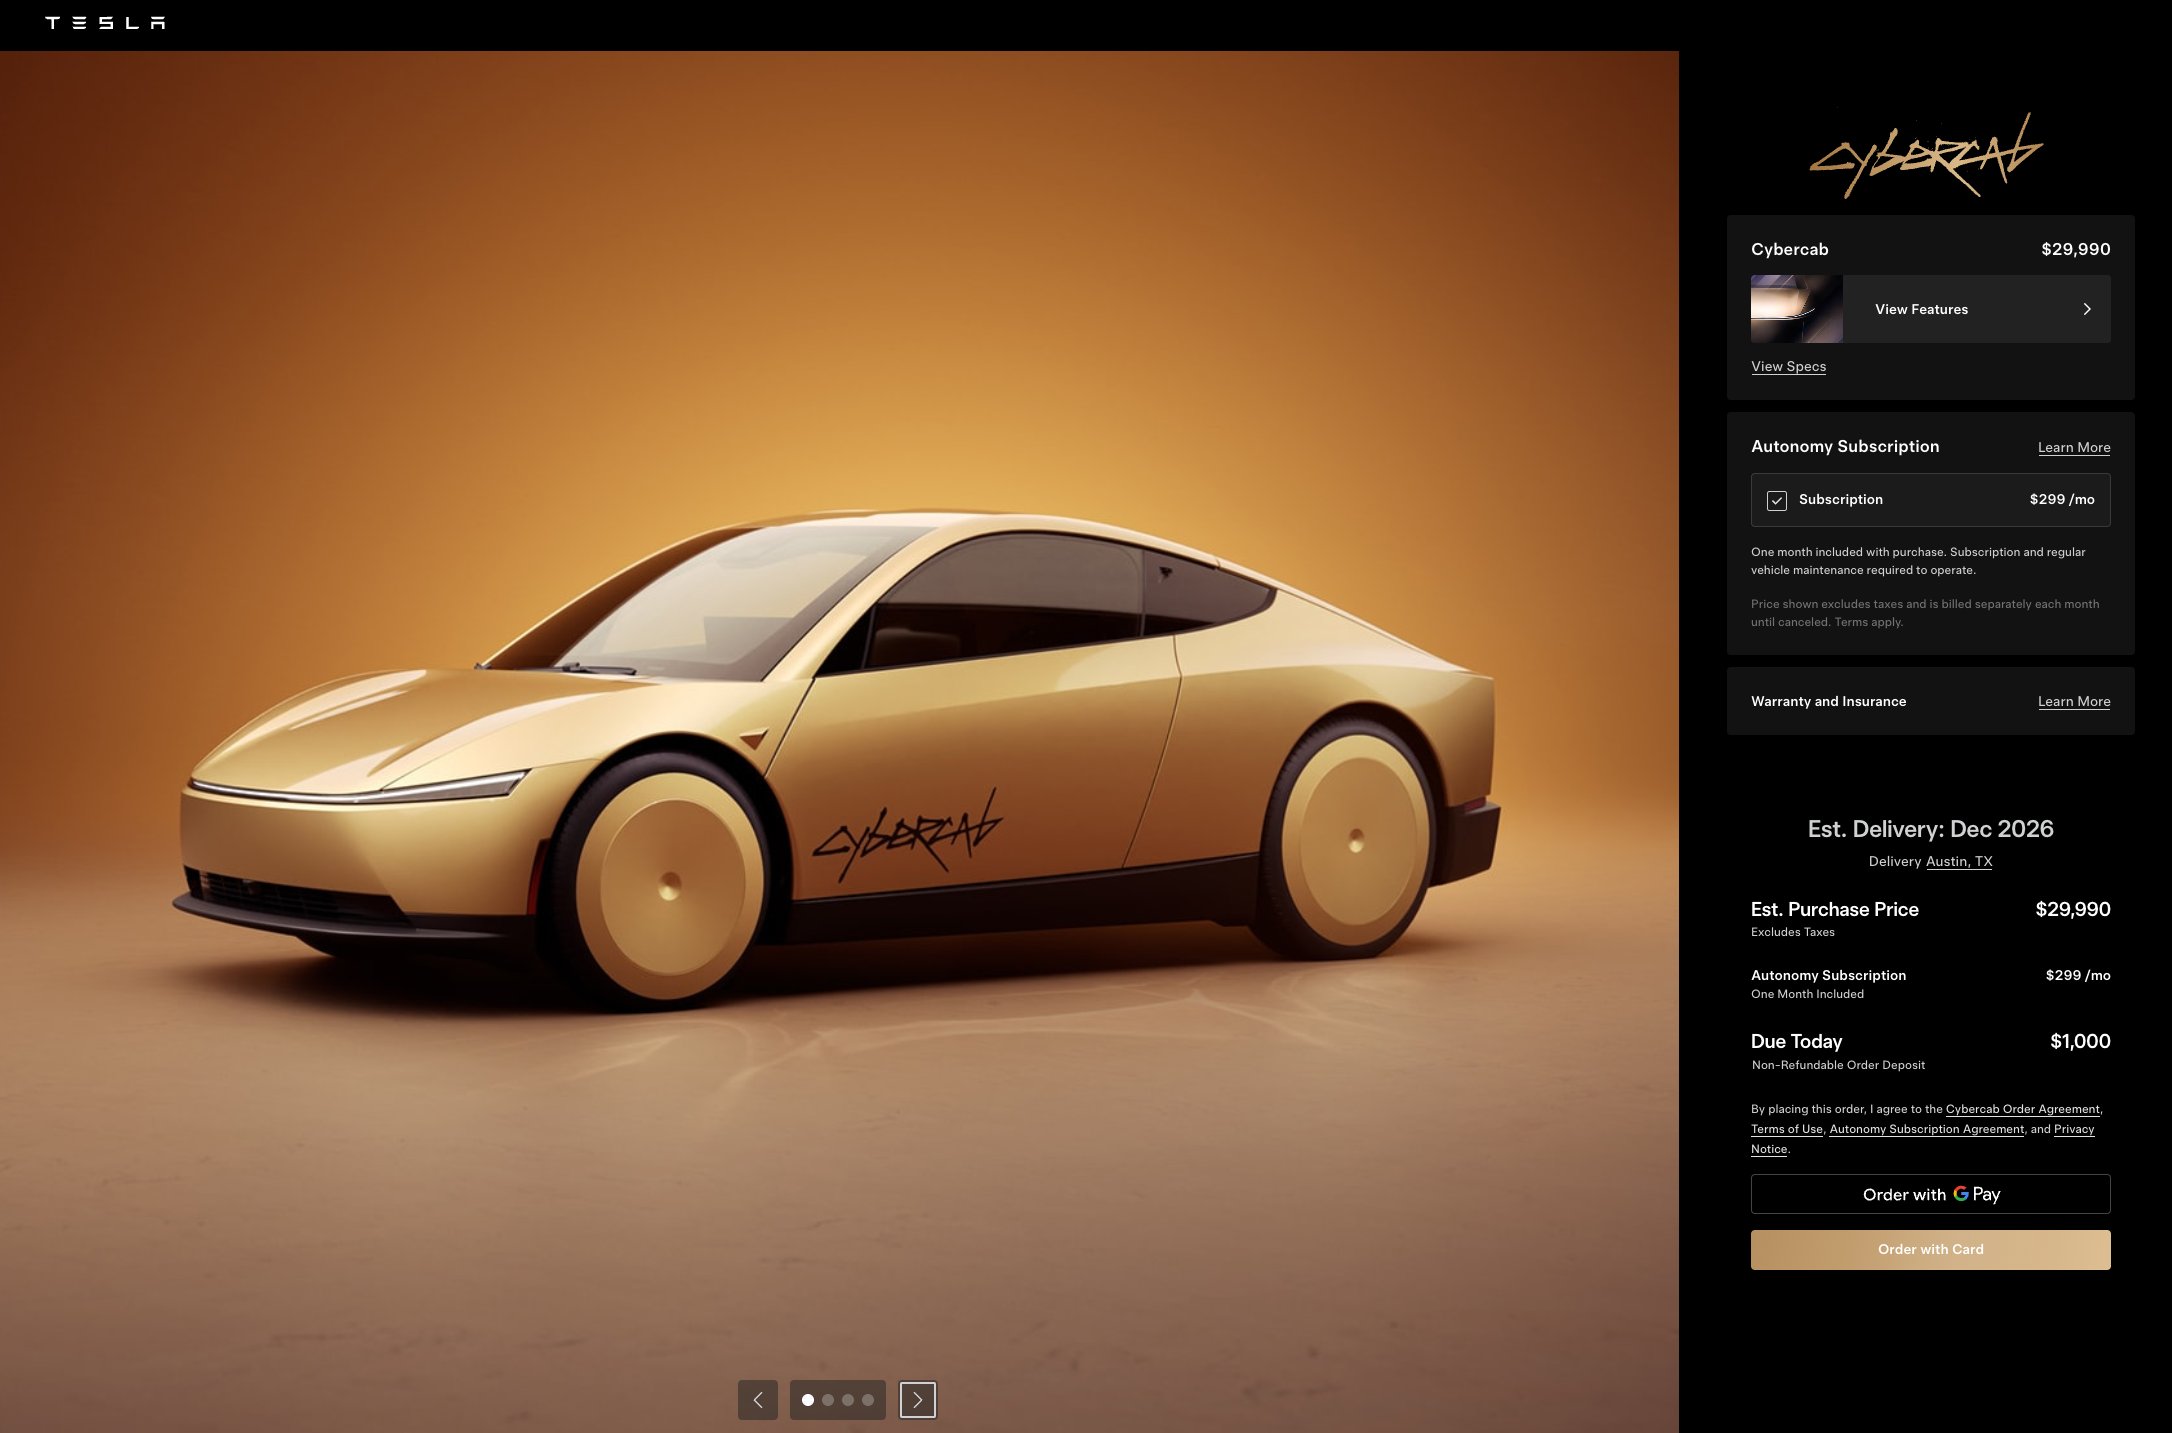
Tesla has officially put the Cybercab up for sale, revealing a bargain price and a $299 per month “Autonomy Subscription” that could hit customer hands as soon as December.
The offer requires a $299 monthly Autonomy Subscription, with the first month included in the purchase price, along with a $1,000 non-refundable order deposit. Tesla’s ordering interface shows deliveries targeted for Austin, Texas.
Tesla says that the Cybercab is making transportation more efficient, affordable and accessible than ever before, and that buyers can order their own Cybercab for personal use.
🚨🚨🚨 BREAKING: Tesla Cybercab is officially on sale for $29,990 with a $299/mo “Autonomy Subscription”
Delivery slotted for December! HUGE!
— TESLARATI (@Teslarati) November 13, 2026
The Cybercab is Tesla’s dedicated robotaxi, a gold-finished, two-passenger vehicle without a steering wheel or pedals, designed from the outset for unsupervised autonomous operation. It has been in limited Robotaxi service in Austin since September 2026, operating alongside Tesla’s larger fleet of Model Y vehicles.
Production takes place at Gigafactory Texas, which launched earlier this year. Tesla has stated for some time that it planned to put Cybercabs on sale by the end of the year, and it looks like they will come through on that promise if everything goes according to plan.
The Autonomy Subscription is mandatory for the vehicle to operate because it is void of a steering wheel and pedals. Tesla notes that the subscription and regular vehicle maintenance are required, indicating that personal owners will depend on the company’s software and service infrastructure rather than traditional ownership models.
One month of the subscription is included with purchase and subsequent months are billed separately until canceled.
This limited personal-sales opening marks a shift from Tesla’s earlier emphasis on fleet and transport-as-a-service operations. During the Q3 2026 Earnings Call, executives indicated that the vast majority of Cybercabs would remain Tesla-owned and used for rideshare service, while still aiming to place some vehicles with customers by year-end.
Elon Musk has previously targeted a price below $30,000, which was a huge point of emphasis for the Cybercab being the central point of Tesla’s “transportation-as-a-service” model.
Availability remains restricted to invited customers rather than a public order page, and the initial deliveries are expected only in the Austin area where unsupervised Robotaxi operations are already active. Buyers will need to accept the geographic and operational constraints of current autonomous deployment, as the vehicle cannot be driven manually outside supported zones.
The move gives a small number of early buyers the chance to own Tesla’s dedicated autonomous vehicle at the long-discussed sub-$30,000 price point, while the bulk of production continues to support the company’s expanding Robotaxi network.
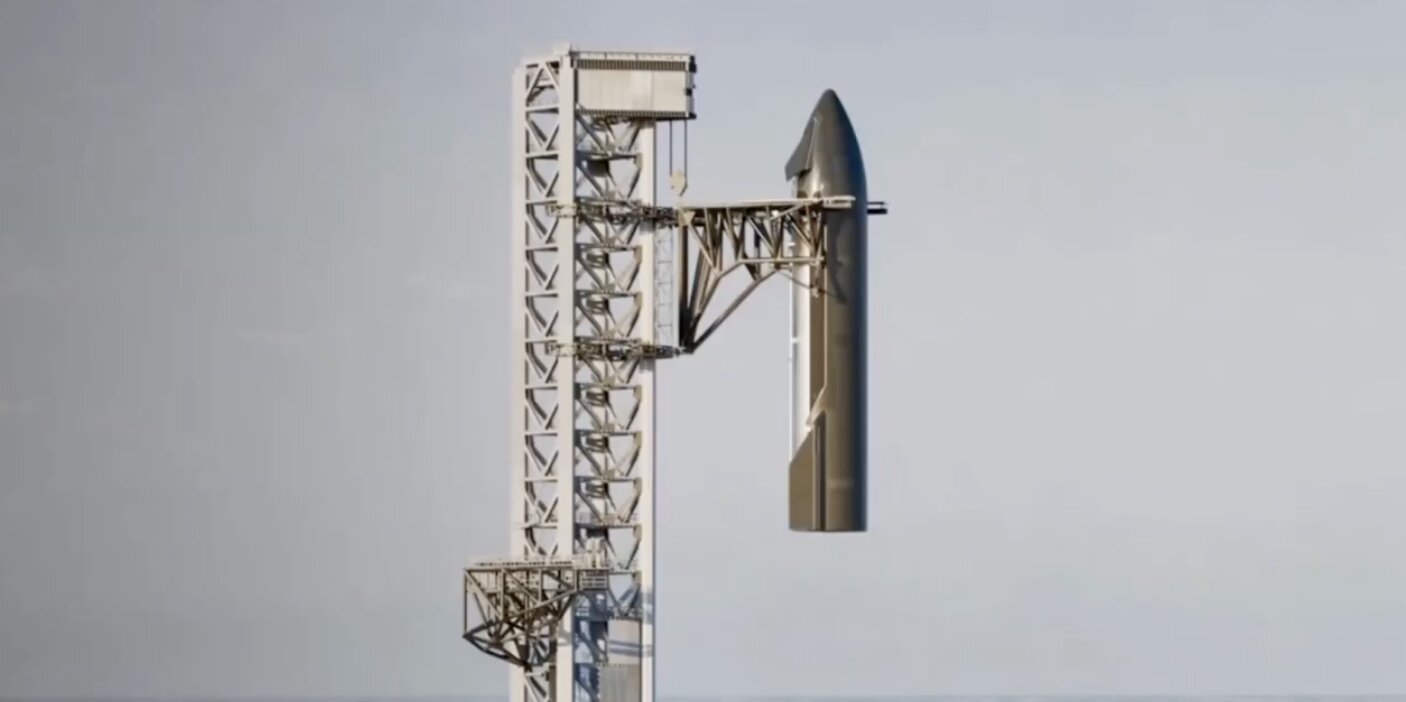
UPDATE: The FAA has granted the license for Starship Flight 15.
Starship Flight 15 License has been granted by the FAA!
Let’s go! https://t.co/DugsgjvYAe
— TESLARATI (@Teslarati) November 13, 2026
SpaceX is set to attempt its 15th test flight of Starship this evening from Starbase, Texas.
SpaceX is targeting Starship Flight 15 for a launch as soon as today, Friday, November 13, pending an FAA Flight License, during a 75-minute window that opens at 4:45 p.m. CT (5:45 p.m. ET) from Orbital Launch Pad 2 at Starbase, Texas. The flight remains pending final regulatory approval.
WATCH Starship Flight 15 here:
https://t.co/C6GnCHyF8p
— TESLARATI (@Teslarati) November 13, 2026
The mission, using Booster 22 and Ship 42, aims to achieve the first full recovery of an orbital launch system. Primary objectives include a tower catch of the Super Heavy booster roughly six and a half minutes after liftoff and the first-ever tower catch of a Starship upper stage after more than 22 hours in space.
SpaceX will perform Starship double catch attempt with Flight 15
Between those catches, Ship 42 is planned to enter a low Earth orbit of about 275 km, complete roughly 14 orbits, and deploy 26 next-generation Starlink V3 satellites (Starlink Group 31-2). Three of those satellites carry cameras to inspect the ship’s heat shield in orbit and help controllers decide whether the vehicle is healthy enough for a return to the tower.
Contingency ocean splashdown options exist if either stage is not cleared for catch.
To watch the attempt, check the link to the broadcast in both X posts in this article. The live webcast is scheduled to begin about 30 minutes before liftoff and is planned to continue through the ship catch the next day, with the possibility of extended onboard views during the orbital coast via Starlink.
Because the schedule is dynamic, check back here or on our social media channels for the latest updates on window timing and regulatory status. A successful dual catch would mark a major milestone toward making Starship a rapidly reusable rocket capable of frequent flights.
WATCH Starship Flight 15 here:
https://t.co/C6GnCHyF8p
— TESLARATI (@Teslarati) November 13, 2026
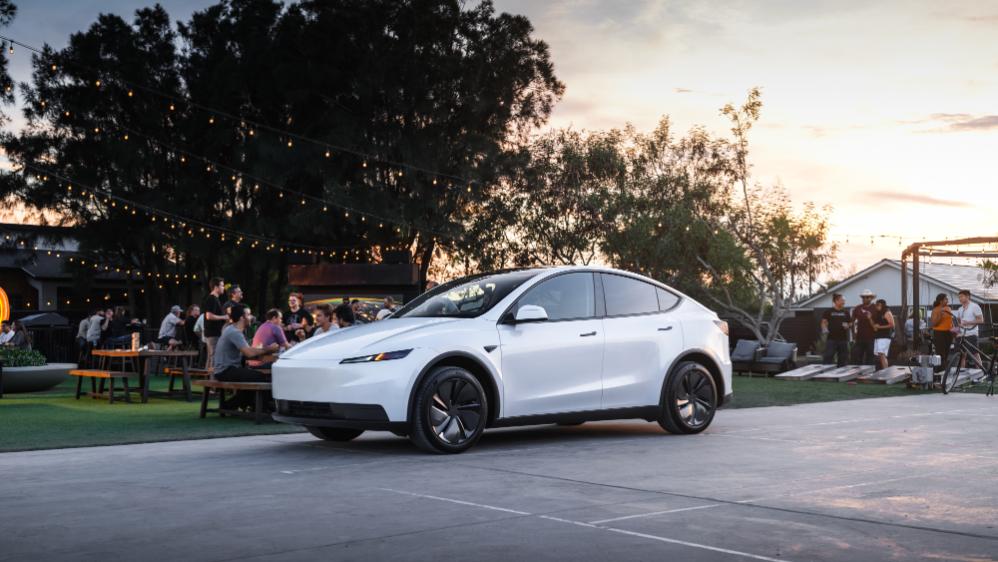
Tesla has trimmed its Model Y offerings as its Standard All-Wheel-Drive configuration has been removed from the online configurator after roughly nine months on sale. The move follows the removal of the Cybertruck, as its trims have also been minimized as that vehicle heads for total discontinuation at the end of Summer 2027.
Launched in February 2026 as a mid-tier dual-motor option between the Rear-Wheel-Drive model and the Premium trims, the Standard All-Wheel-Drive Model Y offered 294 miles of range and a 4.6-second 0-60 mph time in a stripped-down package.
🚨 Tesla has pulled the $41,990 Model Y AWD from its U.S. configurator after nine months on sale.
The cheapest AWD Model Y you can order is now the $49,990 Premium AWD, with Premium deliveries quoted for Jan–Mar 2027.
The $39,990 RWD stays, and AWD units remain in inventory. https://t.co/uROJp2lVpx
— TESLARATI (@Teslarati) November 13, 2026
With it gone, the cheapest new AWD Model Y buyers can configure is now the Premium AWD at $49,990, with estimated deliveries pushed into January–March 2027. The $39,990 rear-wheel-drive Model Y remains available for custom orders, and some AWD units are still listed in inventory.
The move arrives days after Tesla sharply narrowed its Cybertruck lineup. New orders for the Dual Motor AWD and Premium AWD versions have been disabled, leaving only the high-performance Cyberbeast—priced around $109,990 before fees—as the sole configurable option.
Elon Musk has stated that Cybertruck production at Gigafactory Texas will wind down around the middle to late summer of 2027 to free manufacturing space for greater Cybercab output. Tesla has raised prices on remaining trims and is prioritizing higher-margin builds while working through an existing order backlog that exceeds what the line can complete before conversion.
These parallel decisions reflect a broader effort to simplify Tesla’s retail customer lineup. Lower-volume or lower-margin variants are being phased out or deprioritized in favor of core, higher-spec models that generate stronger profitability and clearer production planning.
For the Model Y, this concentrates volume on the remaining RWD and Premium configurations while Premium deliveries already stretch into 2027. For the Cybertruck, it accelerates the transition away from a stainless-steel pickup that underperformed relative to initial volume expectations.
Tesla Model Y Standard Full Review: Is it worth the lower price?
The freed capacity and reduced complexity directly support Cybercab scaling. Tesla began pilot Cybercab production at Giga Texas in early 2026, launched paid autonomous rides in Austin in September, and is preparing for substantial volume growth.
By streamlining the existing vehicle portfolio, the company is reallocating factory space, engineering attention, and supply-chain resources toward its purpose-built Robotaxi, which lacks a steering wheel or pedals and is designed exclusively for unsupervised autonomy.
The result is a leaner retail lineup today and a clearer path to high-volume Cybercab deployment tomorrow.

Tesla Cybercab goes on sale for $29,990, slated for December deliveries

SpaceX Starship Flight 15: How to watch the double catch attempt


