Investor's Corner
Tesla is poised to survive 2020’s worst economic shocks; other automakers, not so much

Just before being proven wrong by Tesla’s first-quarter delivery and production numbers, TSLA bears were hard at work, spreading the now-aging narrative that the company’s electric cars will soon see a drop in demand. Hours before Tesla released its numbers, short-seller Jim Chanos even remarked that he remains “maximum short TSLA,” arguing that the company stands to lose money this year.
What the noted short-seller failed to mention was that this year would likely be downright brutal on the entire auto industry. 2020 only started, but the onset of the coronavirus pandemic has given the whole car market an economic shock that will resonate for a substantial period of time. Tesla will see adverse effects, most likely in the second quarter, but compared to the rest of the industry, the electric car maker may very well be poised to be a company that can not only survive, but thrive in these times of crisis. The same cannot be said for legacy carmakers, or the scheduled “Tesla Killers” that are set to be released in the near future.
Gene Munster of Loup Ventures noted that Tesla’s Q1 production and delivery results show that Tesla is winning despite the current headwinds simply because it has a product that is measurably better than both gas and electric competitors. The Wall Street veteran further added that while the next quarters will be challenging for Tesla and all other automakers like BMW and General Motors, he still expects Tesla to continue reporting 15-25% better delivery results compared to its peers.
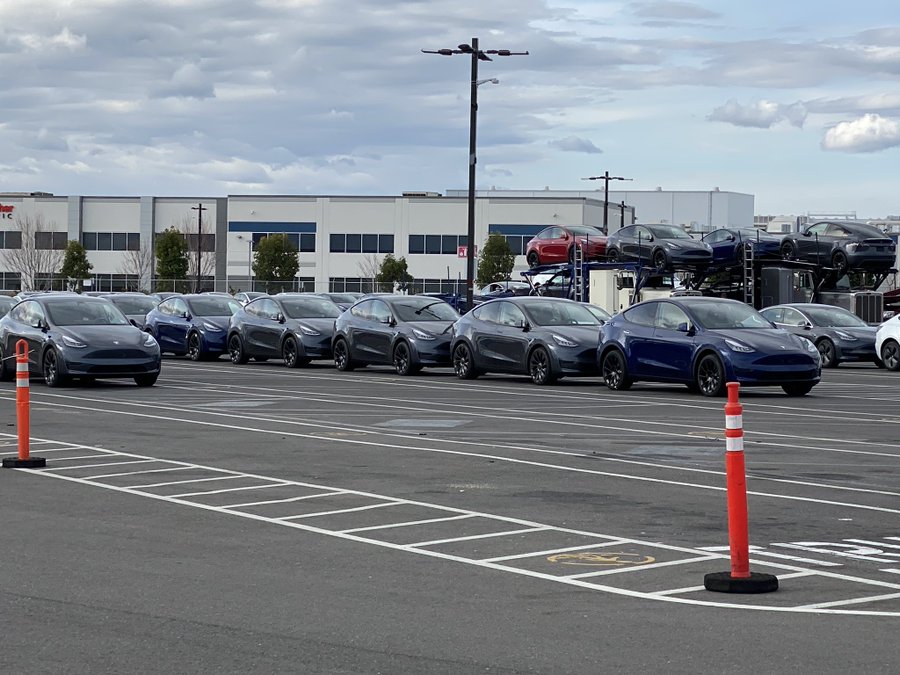
A lot of this is due to the company’s products, specifically the Model 3 sedan and the Model Y crossover. Both vehicles are high-volume EVs, and they are designed to disrupt their respective segments. The Model Y, in particular, is designed to be competitive in the crossover market, which happens to be one of the fastest-growing segments in the auto industry today. Munster argued that over time, the price and performance gap between Tesla and its competitors would likely get broader. This is because rivals, such as legacy automakers and their respective EVs, will either have to sell a vehicle that’s at parity with Tesla’s features and range but at a higher price, or a car whose cost is subsidized by the company, resulting in financial strain. For automakers, such is a notable dilemma.
Tesla investor @Incentives101, an economist with a background in macro research, stated in a message to Teslarati that the demand for the electric car maker’s vehicles will largely depend on how distinct they are from other EVs on the market. It’s quite difficult to analyze a product’s demand from a consumer preferences standpoint. In the case of apparel, for example, it is challenging to determine why some consumers prefer Adidas over Nike. The auto industry is quite the same. When one looks at the demand for vehicles, it is difficult to pinpoint why some consumers buy a BMW 3-Series over an Audi A4, or a Mercedes-Benz C-Class; or why some customers buy a Honda Accord instead of a Toyota Camry.
Explaining further, the economist noted that instances such as these usually mean that the products consumers are purchasing are almost perfect substitutes for each other. If one were to study the size, efficiency, performance, and price of any category of cars, one would see that the differences are usually so marginal between each option and segment that consumer decisions often fall on subjective variables such as looks or brand loyalty. This is something that veteran automakers such as Ford rely on, with the company being proud of F-150 owners sticking with the company for years, or at times, even generations.
In the auto sector, there are various tradeoffs that customers are likely to compromise with. For buyers of cars with an internal combustion engine, opting for a low price will likely sacrifice performance, as is the case with the Toyota Camry. Buyers of electric vehicles from traditional automakers, on the other hand, will probably sacrifice something vital such as range for performance, as is the case with the Porsche Taycan. Tesla’s electric vehicles have pretty much eliminated these tradeoffs over time, largely thanks to the company’s own experience in producing and designing electric vehicles and their unique vertical integration, which provides the company unprecedented control over their products and the way they function.
Amidst the coronavirus pandemic, the health and economic shock that the world is facing are unprecedented. These shocks affect everyone, and for automakers, it will all come down to whoever can recover the fastest. Veteran automakers are fighting at a disadvantage as Tesla extends its gap in performance and tech. Tesla, on the other hand, may very well be poised to hit the ground running and crush its competitors in the process. The Model 3 and Tesla’s first-quarter results highlighted how demand for the company’s vehicles would likely be steady. As for demand concerns about Tesla, the economist noted that such concerns remain overblown.
“Until today, demand concerns about Tesla vehicles are overblown and based on a poor understanding of economics. Demand is a function of consumer preferences, basically what consumers value. It is also a function of income, price of substitutes, and few other things. How much each of these variables affects demand is not static. It may be that consumer preferences don’t change but income does, so in a scenario of rapid economic downturn with relatively fast recovery demand for Tesla would behave the same,” the economist wrote.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.


Tesla and SpaceX shares fell on Wednesday after Democrats swept both chambers of Congress. The decline stood out as broader market securities recovered and turned positive, while both of Musk’s publicly traded companies lagged.
CEO Elon Musk already joked about the unsuccessful campaigning for the Republicans, but now the new party will make pretty drastic changes to how it handles Tesla and SpaceX, and those companies will adjust their outlook.
Let’s take a deeper look.
Tesla ($TSLA)
Tesla shares traded lower during the regular session after Democrats secured both the House and Senate. The stock was down 2.32 percent at around 1:45 p.m. on the East Coast, trading at around $389.30.
The pressure is tied to more than the raw scale of Musk’s political spending, estimated at $450–474 million this cycle with roughly $224 million directed at Texas. In that state, Tesla now faces a Democratic governor and a Democratic senator after Gina Hinojosa unseated Greg Abbott and James Talarico defeated Ken Paxton.
The Austin Gigafactory, Robotaxi pilot programs in multiple Texas cities, and any related AI compute expansion sit under a new state executive who campaigned against certain corporate subsidies and floated a moratorium on new data-center construction.
Federally, Democratic control of key committees opens the door to deeper examination of Tesla’s autonomous-driving safety record, federal energy-storage and manufacturing incentives, and the national-security implications of any combination with SpaceX.
Investors are also weighing whether the company’s historically close alignment with the prior Republican leadership will invite slower permitting, additional hearings, or tighter rules on Full Self-Driving deployment.
For Tesla, the political shift adds near-term friction around state permitting and federal regulatory approvals for autonomy and energy storage. A potential merger with SpaceX may face slower review even if it proceeds.
Core growth drivers such as vehicle deliveries, energy deployments, and robotaxi rollout remain intact, yet the stock now carries a higher political-risk premium that could weigh on valuation until the company demonstrates workable relationships with the new Texas leadership and congressional majorities.
SpaceX ($SPCX)
SpaceX shares also declined in live trading on November 4 following the Democratic midterm sweep. The stock traded at $134.97, down 4.49 percent. The drop occurred even as broader indexes stabilized, highlighting a company-specific reaction to the election outcome.
Musk’s large contributions, concentrated in Texas races that both companies lost, place SpaceX’s Starbase launch facility and headquarters under a new Democratic governor.
At the federal level, Democratic control of Congress enables greater scrutiny of NASA, the Department of Defense, and other contracts that support a meaningful share of revenue, along with reviews of Starlink national-security uses and any Tesla merger. Analysts have noted that empowered committees can hold hearings and request documents on these relationships.
For SpaceX, the results raise the risk of delayed contract awards, higher compliance costs, and tighter constraints on AI and satellite infrastructure expansion, particularly in Texas where a data-center moratorium has been discussed.
A merger with Tesla could encounter political friction that slows integration of launch, connectivity, and autonomy capabilities.
While Starlink growth and launch cadence continue as primary drivers, the company faces a more contested path for federal funding and state-level operations, requiring management to rebuild ties with the new congressional majorities and Texas leadership to limit the overhang.
Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.

Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.
Elon Musk
SpaceX President to gift Trump Accounts her SpaceX stock
Gwynne Shotwell’s 2 million SpaceX shares are headed to children’s Trump Accounts starting this December.
SpaceX President Gwynne Shotwell said Friday that more than 2 million SpaceX shares belonging to her and her husband, Robert, will be distributed to children’s Trump Accounts in December, turning a pledge she made over the summer into an actual transfer. “Robert and I are thrilled that our gift of over 2 million shares of SpaceX stock will be distributed to children’s Trump accounts in December!” Shotwell wrote on X, adding that the shares are “transferring to escrow as we speak.”
The first round goes to children aged 11 to 17 who live in ZIP codes where the median family income is $57,000 or less, along with kids in ZIP codes with too few residents for the Census to report that figure. Shotwell said those families should receive a notice by Monday, Reuters reported.
A second gift is expected to be finalized in the next few weeks. That round will cover eligible children in military families serving overseas, children in foster care, and more kids in Texas counties near the Shotwells’ home where median family income is $90,000 or less. Elon Musk replied to the announcement with “Cool” and a heart emoji.
Shotwell first announced the donation on July 6, less than a month after SpaceX priced its record IPO at $135 per share on the Nasdaq. IPO filings showed Shotwell owned about 12.6 million SpaceX shares, Quartz reported at the time, which makes the gift roughly one sixth of her stake. At the roughly $146 per share used to value Musk’s own pledge earlier this month, 2 million shares are worth about $290 million.
How the stock would actually reach the accounts had been an open question since July. Treasury guidance acknowledged that stock donations could flow into Trump Accounts, but it did not explain the mechanics for a program whose contributions default into an S&P 500 index fund. Shotwell thanked the Treasury, the IRS, the Dell Foundation, Greater Horizons, Invest America and the law firms Morgan Lewis and Gibson Dunn for “working over the past few months to make this happen.”
The transfer also works as a dry run for a far larger gift. On October 19, Musk said he would give one of his SpaceX shares to every kid in America next year and called it “the first of many.” With roughly 72 million children in the country, that pledge is worth about $10.5 billion. President Donald Trump thanked Musk the same day and said the shares would go through Trump Accounts, though neither SpaceX nor the Treasury has published how or when that distribution will happen.
Shotwell’s recipients also fill a gap in the program itself. Trump Accounts launched on July 4, and the $1,000 Treasury deposit only goes to babies born between 2025 and 2028. Teenagers aged 11 to 17 receive no government seed money, so for many of the families getting a notice on Monday, SpaceX stock will be the first asset in the account. The accounts convert into retirement accounts when the child turns 18.

Ferrari Luce sold out for 2027 after design controversy

Musk’s Tesla and SpaceX decline after Democratic Midterm sweep


