Investor's Corner
Tesla Q2 2018 earnings preview: Layoffs, auto revenue, cost of Model 3 ramp

All eyes will be on Tesla’s pace toward profitability on Wednesday, August 1 when the Silicon Valley company, led by CEO Elon Musk, releases its second quarter financial results after the closing bell. With the electric car maker meeting Musk’s self-imposed Model 3 weekly production target for the second quarter practically by the skin of its teeth, there is a good chance that Q2’s financial results will trigger even more volatility in Tesla’s stock (NASDAQ:TSLA). Here then, is a preview of what we can expect for Tesla’s Q2 2018 financial report and earnings call.
Automotive Deliveries and Revenue Impact
Tesla revealed Q2 deliveries totaling 40,740 vehicles, of which 18,440 were Model 3, 10,930 were Model S, and 11,370 were Model X when it released its production and delivery report earlier this month. Based on the company’s figures, the second quarter results are set to highlight the record deliveries for the Model 3, 10,000 more units compared to Q1. Charts displaying these could be viewed below, courtesy of Galileo Russell of YouTube’s HyperChange TV.
-
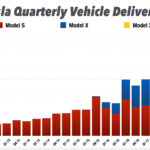
- Tesla’s vehicle deliveries. [Credit: Galileo Russell]
-
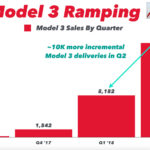
- Tesla’s Model 3 deliveries. [Credit: Galileo Russell]
Tesla posted revenue of $2.56B in Q1 for vehicle sales, including 8,182 Model 3s that were delivered to customers during the three-month period. Assuming that the additional 10,000 Model 3 delivered in Q2 averaged $55,000 per unit, Tesla could post an additional ~$550 million in earnings from the electric car. Revenue from Tesla’s vehicle leasing business likely remained flat considering that the lending option is not available yet for the Model 3. Service revenue could see a spike in Q2, however, as a result of more Model 3 vehicles being on the road.
The Price of the Model 3 Ramp
Tesla focused largely on the Model 3 ramp during Q2 2018, with the company pulling out all stops to hit its milestone of producing 5,000 Model 3 per week by the end of June. In order to achieve its target production rate, Tesla adopted unorthodox measures such as air-freighting robots and equipment from Europe and setting up an entirely new Model 3 assembly line on the grounds of the Fremont factory. These strategies likely resulted in additional expenses for the company in the second quarter. With the Model 3 ramp as a priority, Tesla’s other sources of income, such as its battery storage and solar business likely remained flat compared to Q1 as a result.
The company’s operational expenditure would likely see a slight bump in the second quarter due to the 9% layoffs that Tesla implemented to organize its workforce, considering that the restructuring included severance pay packages to employees who were terminated. In a video outlining his expectations for Tesla’s Q2 2018 results, the HyperChange TV host noted that he believes Tesla would post an estimated $4B in revenue with losses in the ~$500 million range. That’s a 43% increase in revenue compared to Q2 2017, when Tesla posted earnings of $2.8B, but also double the losses of the company’s losses in 2017’s second quarter.
Looking Past Q2’s Aftermath
Overall, Tesla’s Q2 2018 quarter financial results would likely feature similarities with Q1, in the way that the company would show strong growth but post substantial losses and negative cash flow. Nevertheless, it is pertinent to note that while Q2 2018’s numbers could be discouraging, the quarter could be seen as a turning point for Tesla, especially with regards to its Model 3 ramp. The past quarters, Q2 2018 included, have been focused on bringing the vehicle’s manufacturing up to 5,000 per week, resulting in the company investing heavily in resources to help scale the vehicle’s production.
With the 5,000/week milestone attained and with Tesla now more focused on sustaining its Model 3 production rate, Q3 2018 would most likely feature a pathway to profitability in the form of more encouraging financials than the second quarter. Provided that Tesla adopts a deliberate, realistic plan for the further ramp of the Model 3, the next few quarters could very well prove to be profitable.
Watch Galileo Russell’s take on Tesla’s Q2 2018 financial results in the video below.

Investor's Corner
New drone video shows Tesla’s Optimus Factory reaching a turning point
New drone footage shows Tesla’s dedicated Optimus factory steel frame nearing completion at Giga Texas.

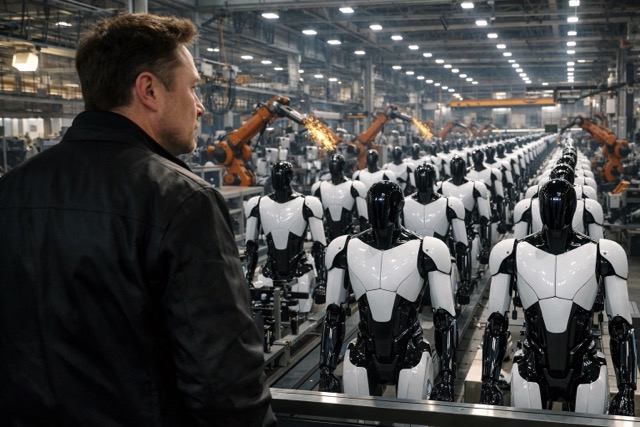
Tesla’s dedicated Optimus factory at Gigafactory Texas is closing in on a finished steel frame, according to drone footage posted Thursday afternoon by longtime site observer Joe Tegtmeyer. In the video, Tegtmeyer said structural steel assembly is now about five column grids away from reaching the building’s north perimeter beam, putting the primary skeleton in its final stretch roughly six months after Tesla broke ground on the North Campus site in late March.
The Giga Texas Optimus Factory latest update … construction keeps moving fast!
Steel assembly is now only about 5 column grids from the north perimeter beam. Concrete is going in on the three upper floors, rebar is still being laid for more pours, and footing / grade-beam work… pic.twitter.com/qvFPvwnYzW
— Joe Tegtmeyer 🚀 🤠🛸😎 (@JoeTegtmeyer) September 17, 2026
Tegtmeyer’s footage shows concrete already going in on three upper floors while crews continue laying rebar and pouring grade beam footings at ground level. That kind of parallel work, steel rising at one end of the site while concrete sets at the other, is a scheduling approach Tesla used at the original Giga Texas building and appears to be repeating here to save time before the plant’s targeted 2027 production start.
Teslarati has tracked the building’s progress since Tesla confirmed construction was officially underway in May, when the first steel structure went up on what was then bare, reclaimed land. The facility is part of a more than 5.2 million square foot expansion of Giga Texas’s North Campus that Tesla has said will eventually run nearly the length of the existing vehicle factory, over 4,000 feet, while sitting somewhat narrower. Musk has pegged the long term output target at 10 million Optimus units a year once the line is running at full capacity, a volume that would dwarf the one million unit pilot line Tesla is standing up separately at its Fremont, California factory.
Tesla Giga Texas to feature massive Optimus V4 production line
The Texas facility sits alongside another major buildout on the same campus. Terafab, the joint Tesla and SpaceX chip fabrication plant that will eventually supply the silicon running Optimus units in the field. Housing robot assembly and chip production on the same grounds is a deliberate supply chain decision, cutting down on the shipping and lead time that would otherwise sit between the two.
Tesla has not given an updated timeline beyond its previously stated goal of bringing high volume Optimus production online at the site in the summer of 2027. Fremont’s smaller pilot line began mass producing the current Gen 3 robot in January, with that plant expected to build tens of thousands of units this year primarily to generate the real world data Tesla needs to refine the robot’s software before Giga Texas ramps up. Six months of visible construction progress, tracked almost entirely through Tegtmeyer’s recurring drone flights, gives the clearest outside look yet at how seriously Tesla is treating that 2027 deadline.
Investor's Corner
Tesla and SpaceX take “Terafab” Trademark fight to Federal Court
Tesla and SpaceX sue a small Illinois firm after cease and desist letters over Terafab.

Tesla and SpaceX are asking a federal judge to rule that their planned Terafab chip factory does not infringe a small Illinois company’s trademark, a request that arrives only after months of quiet negotiation broke down this summer.
The dispute traces to May 18, when Tesla filed three U.S. trademark applications for “Terafab” and “Tesla Terafab,” covering semiconductor chips and related chip making services. TERA-print LLC, a nanotechnology company that has held a federal trademark for “Tera-Fab” since 2021, responded five days later with a cease and desist letter. According to the lawsuit, first reported by Reuters, TERA-print argued that Tesla and SpaceX’s use of “Terafab” would confuse consumers familiar with its own trademark, which covers a desktop photolithography printer sold to researchers for sensor and bioengineering work.
What stands out in the filing is the timing of TERA-print’s own paperwork. One day before sending that cease and desist letter, on May 22, TERA-print applied to expand its existing registration to cover semiconductor materials, silicon chips, nanoelectronic devices and AI design services, categories it had not previously claimed. Tesla and SpaceX call that filing opportunistic in their complaint, noting it arrived two months after Tesla’s public Terafab announcement and just days after Tesla’s own trademark applications went in.
Elon Musk launches TERAFAB: The $25B Tesla-SpaceXAI chip factory that will rewire the AI industry
By June 10, TERA-print was threatening to sue for federal trademark infringement, false designation of origin and unfair competition, the complaint states. Rather than wait to be sued, Tesla, SpaceX and SpaceXAI met with TERA-print six separate times between June and August trying to resolve the dispute directly. Those talks collapsed, and the companies filed for declaratory judgment this week in the U.S. District Court for the Western District of Texas, asking a judge to find that “Terafab” does not infringe TERA-print’s mark before TERA-print can file a claim of its own.
TERA-print isn’t backing down. The company told PCMag it discussed a settlement with Tesla as recently as September 2 and feels misled by what it called Tesla’s professed interest in settling. Its CTO, Andrey Ivankin, said TERA-print holds a Defense Department contract to fabricate semiconductors and partially owns Mattiq Inc., an AI company built on TERA-print’s products, and that the company will vigorously defend its rights.
Tesla and SpaceX argue the overlap is superficial. Terafab is planned as a $16.8 billion complex spanning roughly 100 million square feet at the Grimes County site SpaceX confirmed last month, built to produce chips for Optimus robots, Tesla’s AI computing needs and SpaceX’s orbital data center ambitions, a scale and purpose the companies say no reasonable consumer would confuse with a tabletop lab printer. TERA-print’s product line has stayed focused on lithography tools for biological and sensor research since it registered its mark in 2021.
The trademark fight is the second legal dispute tied to the Terafab project in the past week, following a separate SpaceX suit aimed at keeping company records about the facility out of public view, as KBTX reported. Whether construction proceeds under the Terafab name now depends on a federal judge in Austin.

In a new interview on Wednesday, Tesla uber bull Ron Baron said that anyone looking to buy the company’s stock should do so as soon as they can.
Baron, founder and CEO of Baron Capital and one of Tesla’s most persistent institutional bulls, used a CNBC Squawk Box appearance on Wednesday to deliver a familiar message with fresh urgency: In his opinion, Tesla stock is a buy:
“The time to buy the stock is now. FSD is catching on, and it’s going to be bigger and bigger. 55% of new buyers are buying it (Teslas) with FSD. It’s going to be everywhere. It’s safer.”
The Baron Capital frontman’s case is built around Full Self-Driving. Tesla reported 1.48 million active FSD subscriptions in the second quarter, up 56 percent year over year, and company officials have said roughly 55 percent of new North American deliveries left with a subscription enabled.
Baron framed that attach rate as proof the product is moving from enthusiast extra to default expectation, and as a reason software, not just vehicle volume, should drive the next phase of value.
His conviction on Tesla shares is not theoretical, as Baron Capital made its first Tesla investment in 2014, after years of meetings that began around the 2010 IPO roadshow. The firm later built a large SpaceX position starting in 2017.
Ron Baron today in new interview on Tesla:
“The time to buy the stock is now. FSD is catching on, and it’s going to be bigger and bigger. 55% of new buyers are buying it (Teslas) with FSD. It’s going to be everywhere. It’s safer.” pic.twitter.com/Rv5PB0bVZ2
— Sawyer Merritt (@SawyerMerritt) September 16, 2026
Baron said those Musk-led bets have generated about $30 billion of the $71 billion in profits Baron Capital has produced for clients. He put the firm’s current exposure at roughly $25 billion in SpaceX and $5 billion in Tesla. Personally, he described SpaceX as his largest holding, at about $5 billion, with about $1.5 billion in Tesla and additional Tesla exposure through the firm’s funds.
That concentration is also a statement of loyalty. Asked about talk of a SpaceX-Tesla combination, Baron said he had already walked Elon Musk through arguments for and against a deal, then declined to repeat them on air. His public position was simpler: “Whatever you decide is better is what I’m going to support,” he said to Musk.
Baron also said that he picked up the farewell edition of the Model S after Tesla decided to sunset the vehicle earlier this year, calling it his favorite car he’s ever driven.

New drone video shows Tesla’s Optimus Factory reaching a turning point

Tesla and SpaceX take “Terafab” Trademark fight to Federal Court


