News
SpaceX to launch Varda Space’s first Rocket Lab-derived ‘space factory’ satellite

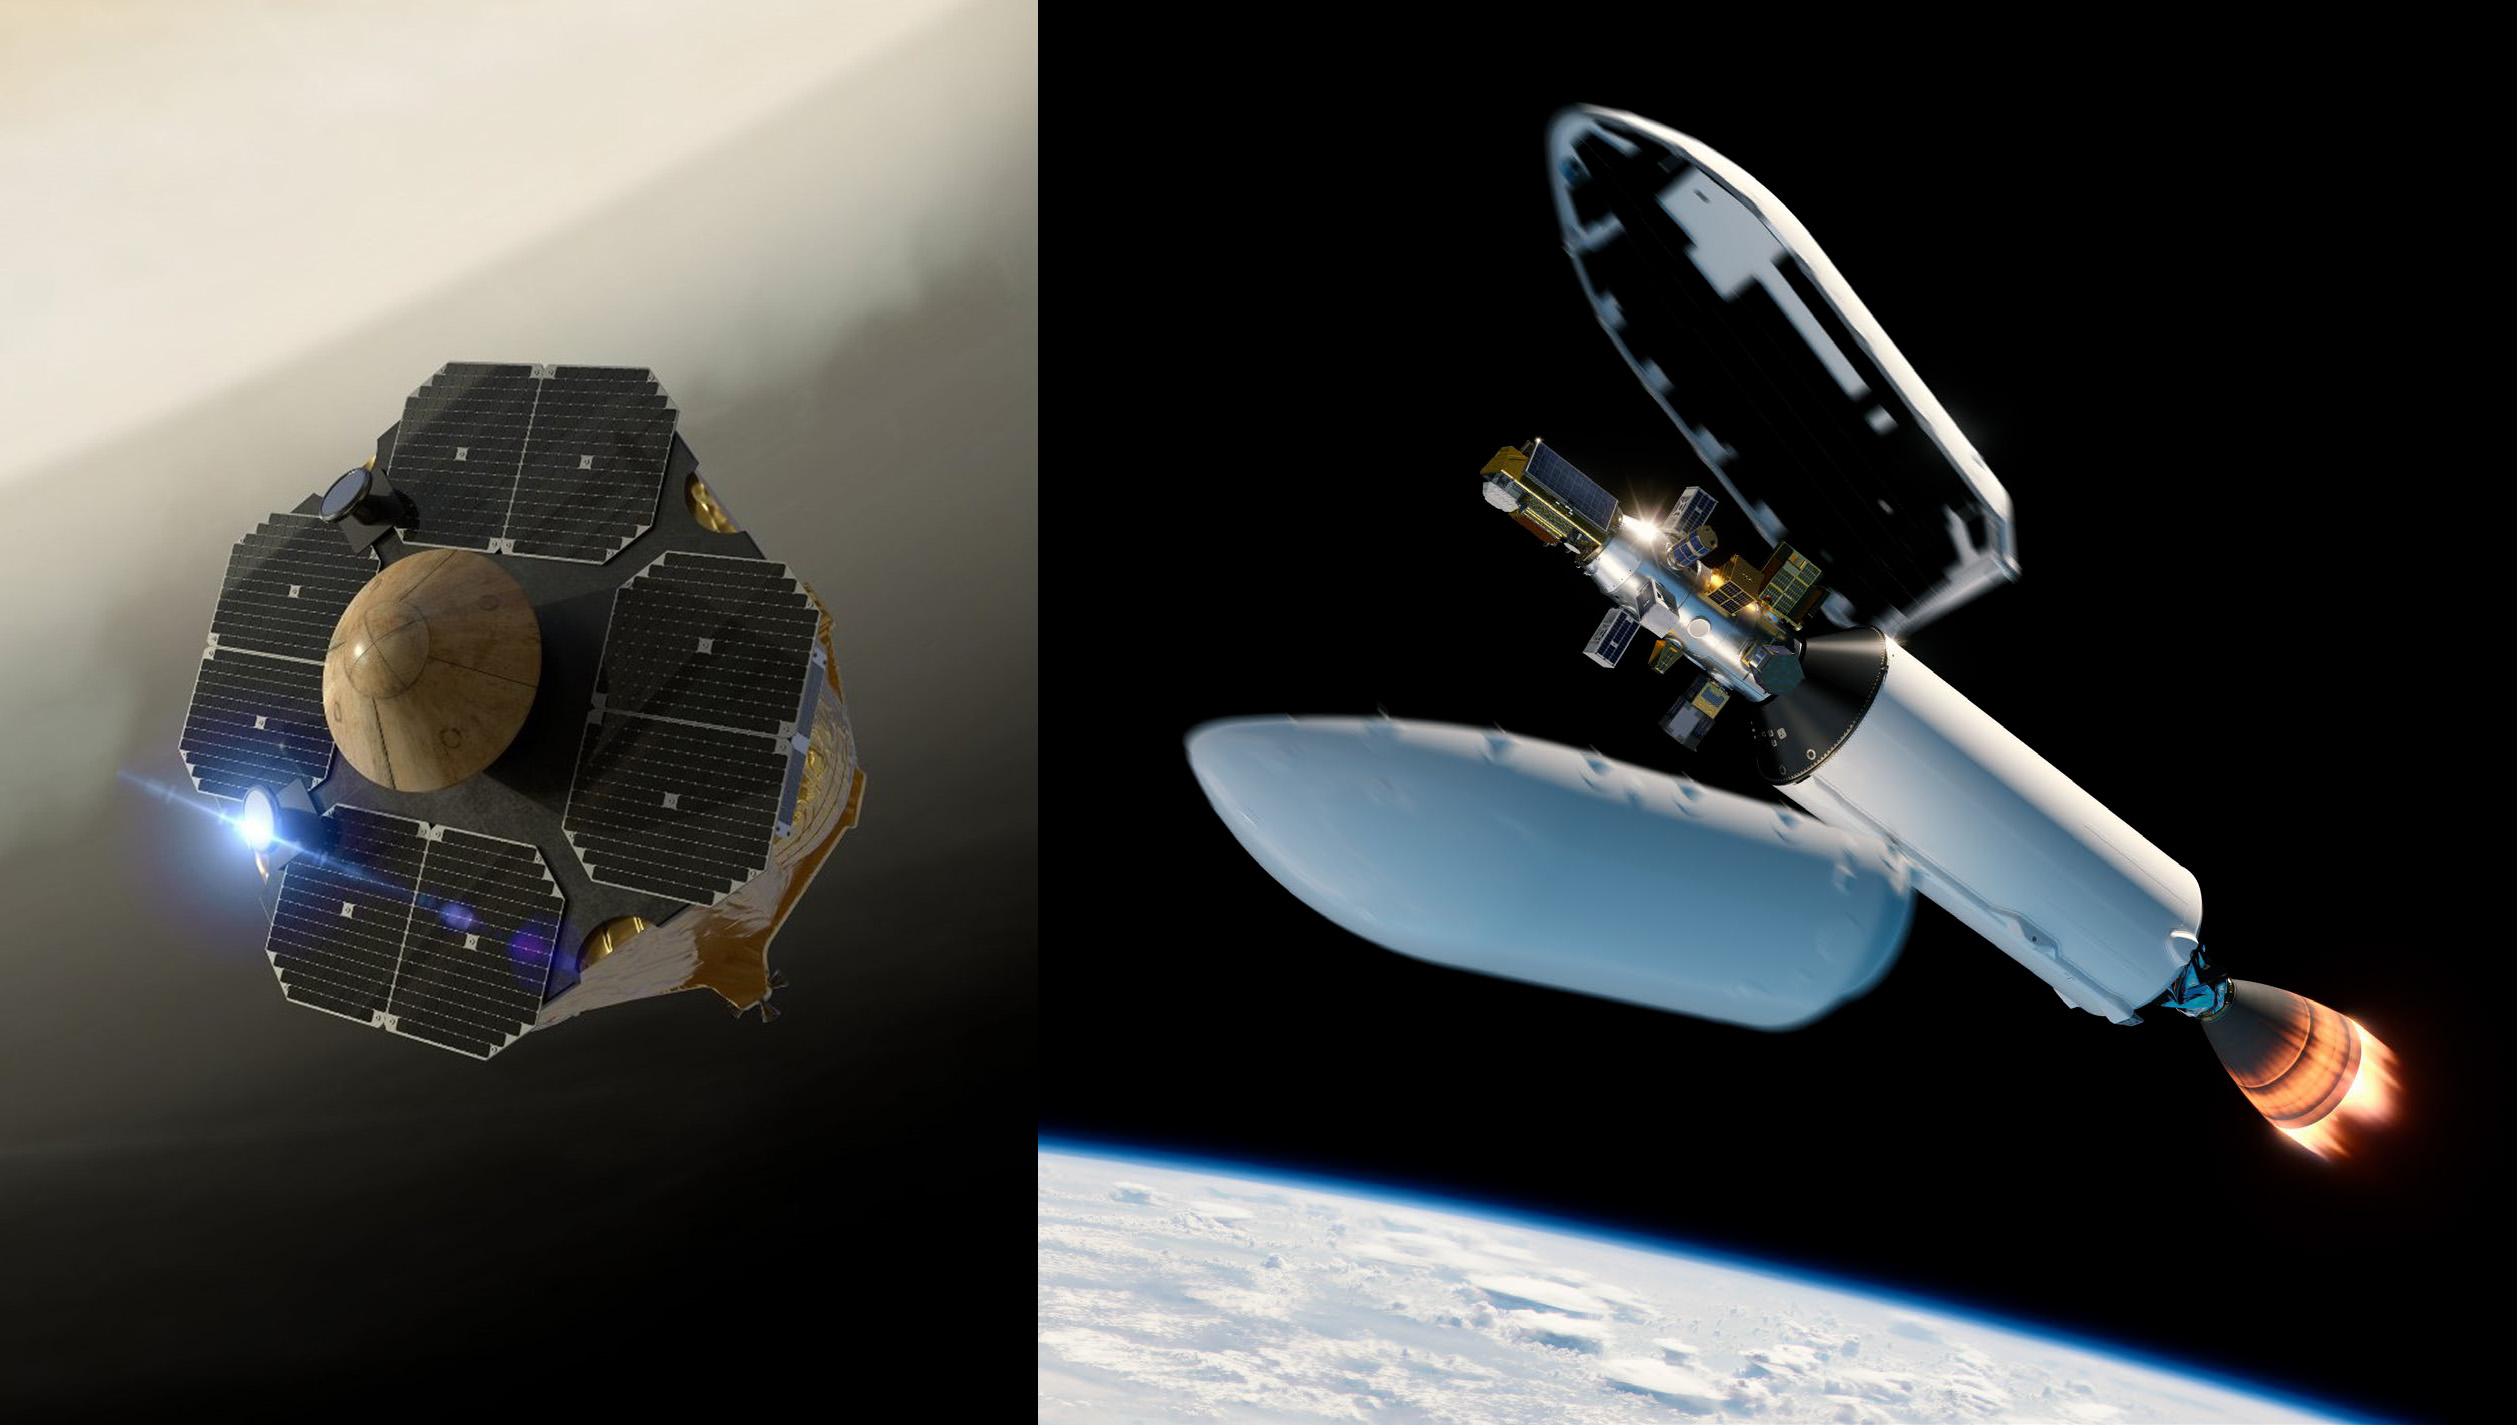
Startup Varda Space says it has contracted with SpaceX to launch its first satellite – based on a Rocket Lab bus called Photon – on a Falcon 9 rideshare mission in early 2023.
Founded in late 2020, Varda Space says its mission “is to build the first space factory” – or, to be more precise, the first all-in-one space factory. While far from the commercial orbital laboratory many at NASA would like to paint it as, the joint NASA-Russia International Space Station (ISS) routinely hosts payloads from paying customers, some of which are focused on manufacturing (albeit at an absurdly low volume) materials that can only be made in microgravity (i.e. ‘zero-G’). The products those experiments or miniature factories produce are then returned to Earth on one of SpaceX’s Dragons – still the only spacecraft in existence capable of delivering large amounts of cargo from space to Earth more than a decade after its debut.
This is to say that orbital manufacturing is not exactly a new practice and has been ongoing – at a very, very small scale – for years through companies like Made In Space. What Varda Space wants to do, then, is repeat – and, nominally, expand that ISS-proven model. Rather than launching small experiments or mini-factories to the ISS, where a captive ISS crew is often available to troubleshoot or help maintain them, Varda wants to build its own small satellites with tiny reentry capsules capable of returning up to 100 kg (~220 lb) to Earth.
Two months after the company announced it had raised more than $53 million in funding, Varda Space now says that it will launch the first of its custom-built “space factories” on a Falcon 9 rideshare mission in Q1 2023. In August, Varda revealed that it had contracted with small launch company Rocket Lab to purchase three of its Photon satellite buses – each to serve as a sort of mothership for each Varda-built reentry capsule. Based on Rocket Lab’s successful Electron rocket kick stage, Photon adds solar panels, batteries, avionics, more propellant, and optional propulsion upgrades to create an off-the-shelf satellite bus capable of supporting and powering onboard payloads.
Instead of having to build and qualify their own satellites, Photon thus gives certain customers the opportunity to focus their time and resources on developing the payloads they want to deploy and services they want to operate. No need to reinvent the wheel, in other words. Varda Space appears to be the first company intent on fully taking advantage of that opportunity – and to great effect given that the startup has raised more than $50M less than a year after it was founded.
Additionally, with its SpaceX launch contract, Varda Space has also effectively revealed that Rocket Lab has no clause preventing Photon customers from launching their procured satellite buses on rockets not built by Rocket Lab. While dedicated small satellite launchers like Rocket Lab’s Electron offer some benefits, they do so at a huge premium. While an Electron launch carrying 200 kg (440 lb) to a sun-synchronous orbit (SSO) is believed to cost around $7.5M, a slot on a SpaceX rideshare to a similar (but not as perfectly tailored) orbit would cost the same customer about $1M – practically a magnitude cheaper.
Rocket Lab’s Photon likely costs just a few million dollars and comes by default with a propulsion system capable of refining the spacecraft’s orbit after a one-size-fits-all rideshare launch. That means that manifest a Photon-based satellite on a SpaceX rideshare could likely cut the cost of buying and launching a new satellite in half – and maybe further. The question, then, is whether Varda can take those potentially substantial cost savings and design and manufacture a tiny orbital reentry capsule that’s cheap enough to make its free-flying space factories competitive with the International Space Station (ISS).



Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
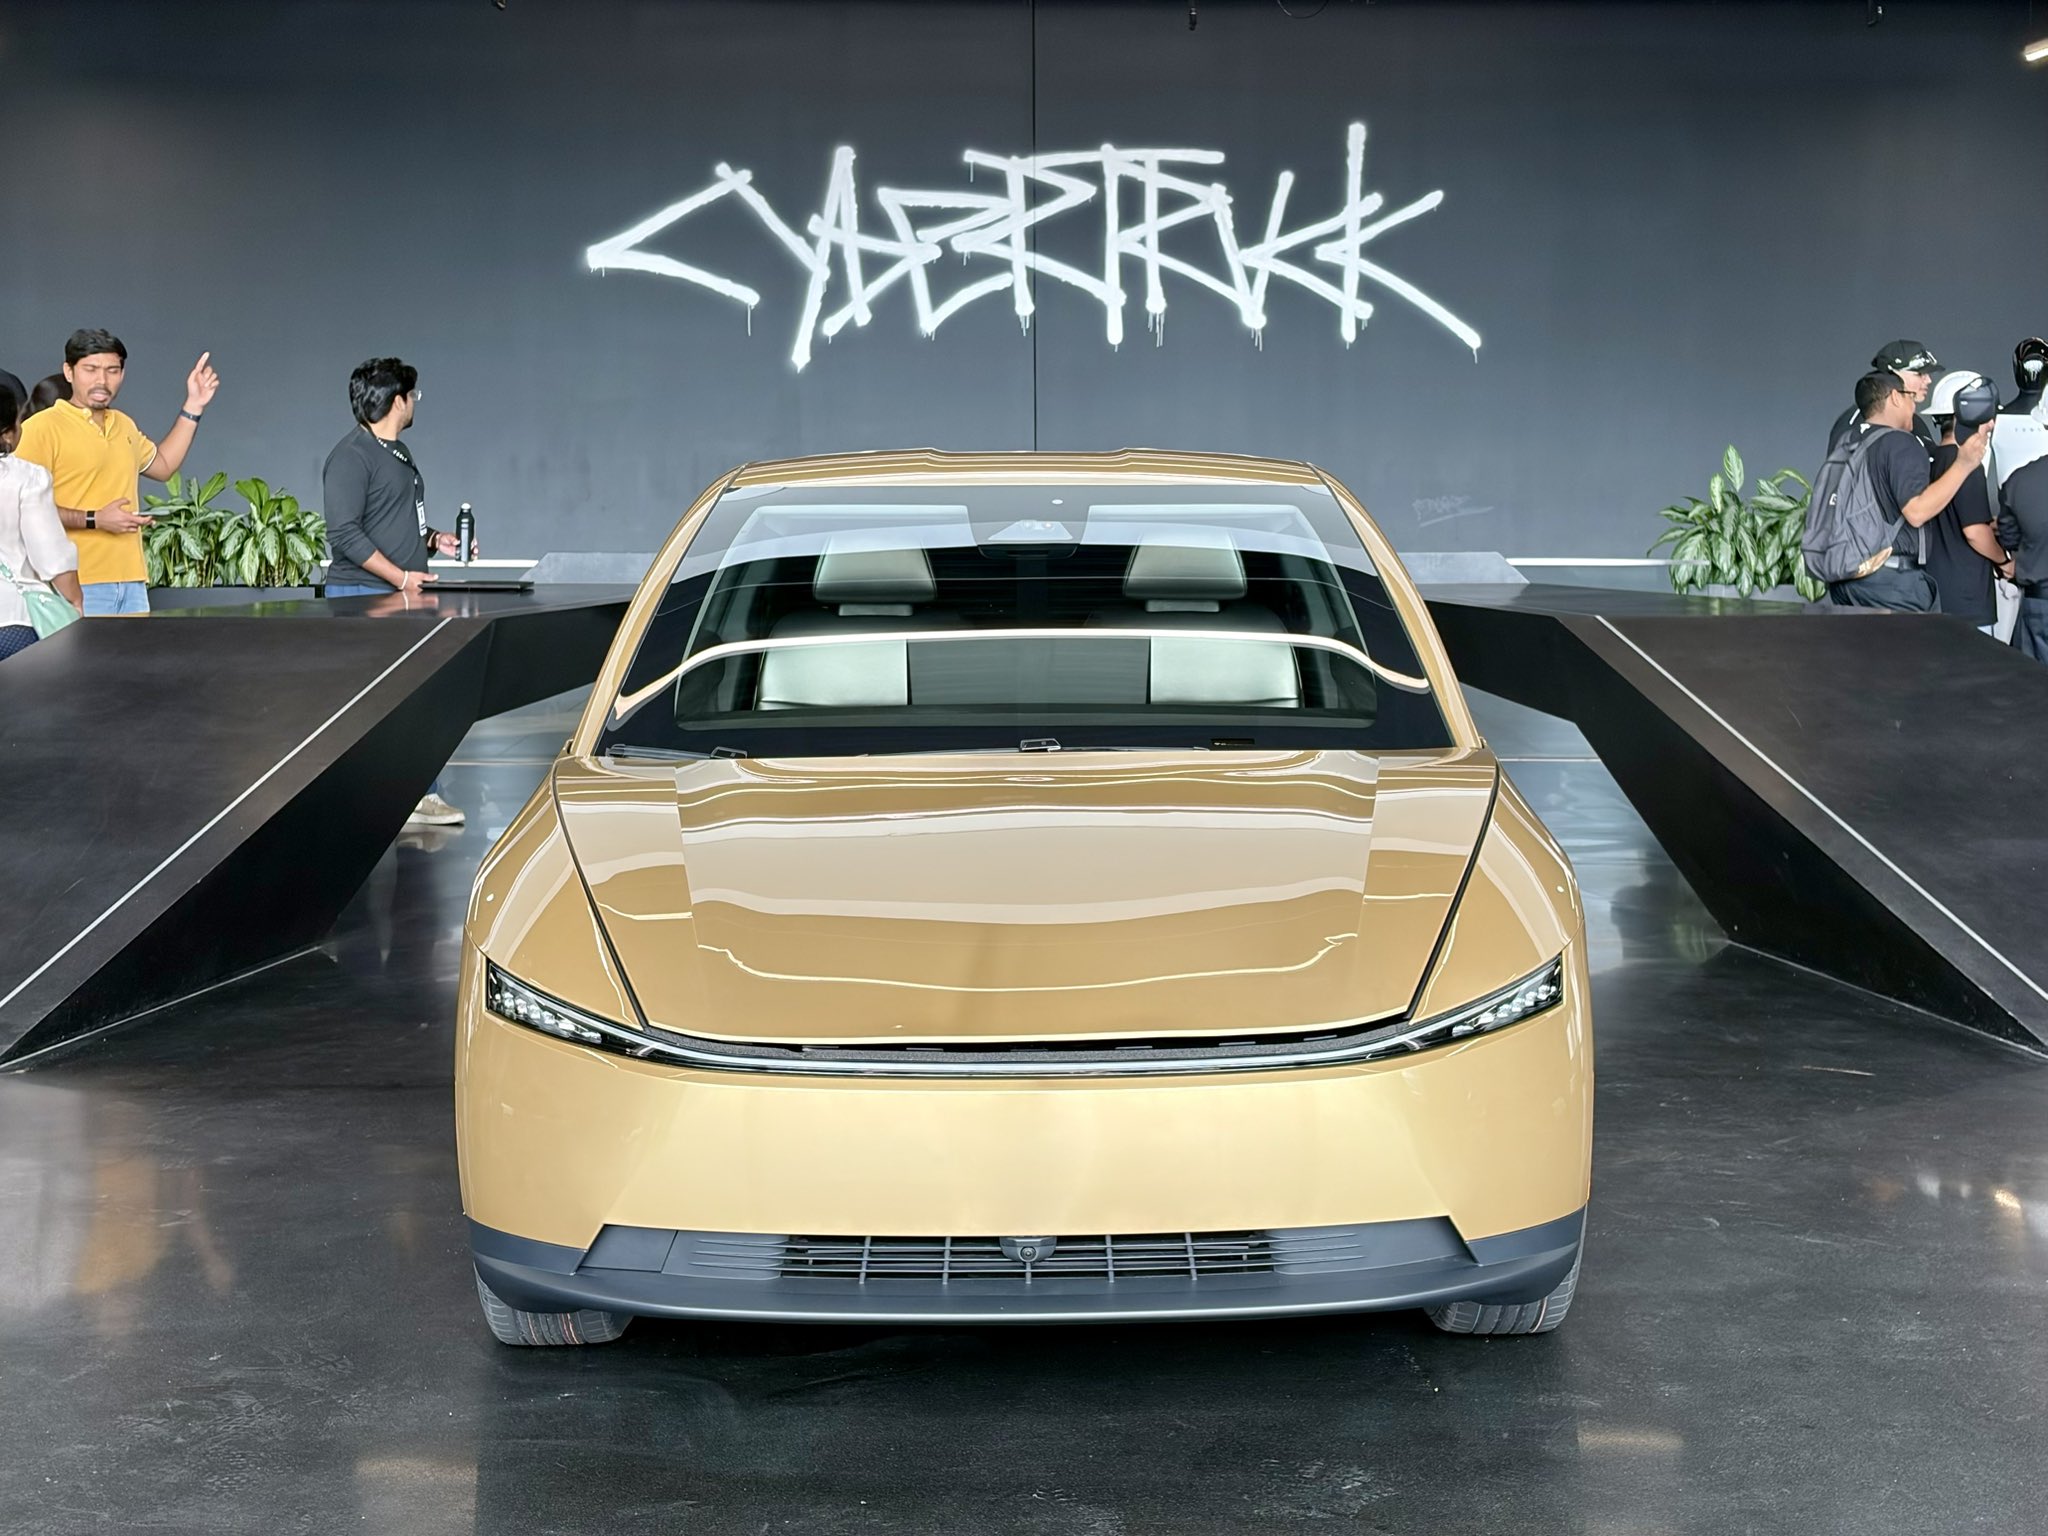
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.
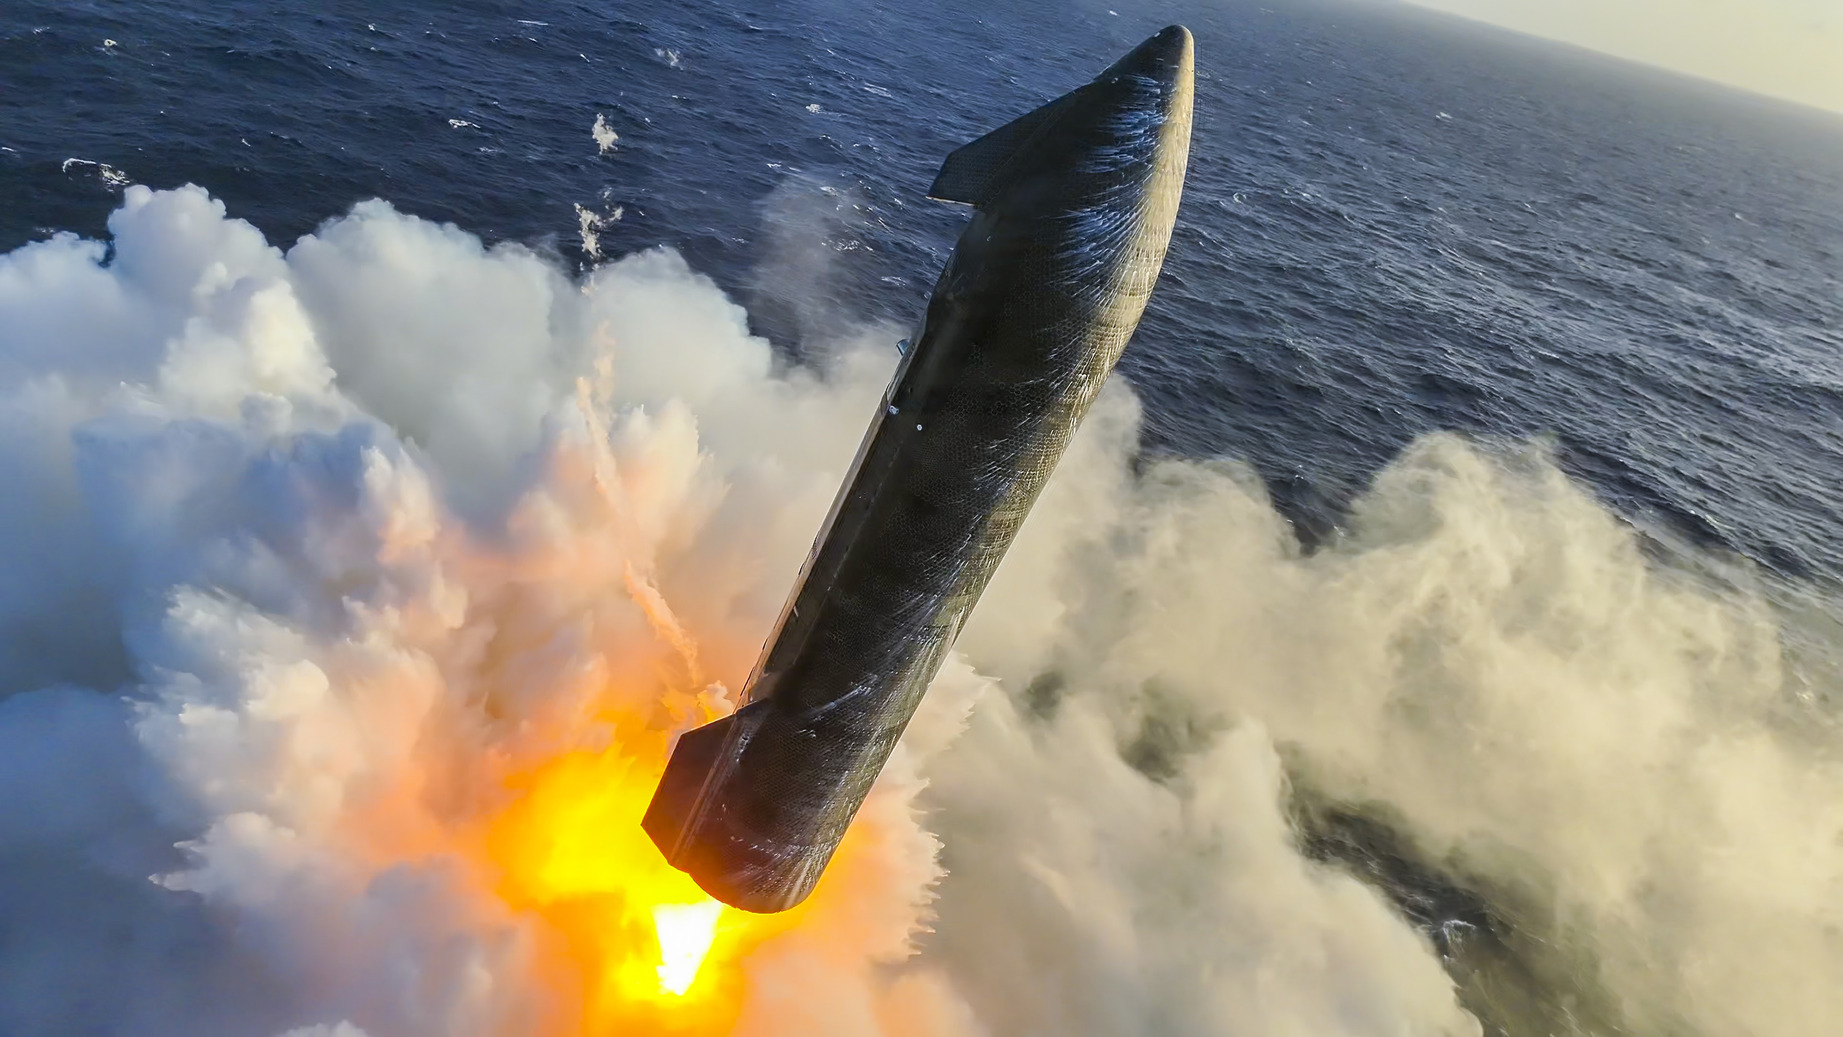
SpaceX confirmed the date of Starship’s 15th launch window with some massive ambitions for the mission, as it will attempt to catch Ship for the first time.
CEO Elon Musk confirmed during SpaceX’s Earnings Call last night on October 20 that it would launch Starship for its 15th test flight in November, and there are some incredible things the company wants to try, making it perhaps the most groundbreaking launch in the program’s history.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
The most major development of the call was SpaceX’s intention to catch Ship alongside catching the Super Heavy Booster, something that has happened in the past. SpaceX showed an animation of the Ship catch, which will be done on the launch tower’s chopsticks:
SpaceX has released a new Starship tower catch animation for the upcoming Flight 15! https://t.co/kStn01Da8u
— Truthful🛰️ (@Truthful_ast) October 20, 2026
This monumental goal is to catch both the Ship and Booster in a dual-catch scenario, an incredible feat since SpaceX has never been able to reuse a Ship after launch. Musk said it would be “the first time that an orbital launch vehicle has been fully recovered,” and said it would be a “profound technology milestone.”
Musk said the odds of success on this first Ship catch attempt are “more likely than not,” but SpaceX is ultimately prepared for more tries moving forward. The SpaceX frontman said that, starting next year, Starship would have a “steady stream” of flights through the end of the year.
The cadence will accelerate in 2027, with Musk stating the company plans to target weekly flights in the first half of 2027 and twice-weekly by year-end.
The Flight 15 attempt follows that of Flight 14, which took off in late September and was Starship’s first orbital mission. It deployed 26 Starlink V3 satellites, accomplished a controlled ocean splashdown of both stages, and shed more light on potential challenges for the program moving forward.
As of now, the Starship program is firing on all cylinders.
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Wall Street analysts rapidly raised price targets on SpaceX (NASDAQ: SPCX) after the company reported a bullish third quarter for 2026 following the market close on October 20. Shares were sent sharply higher in after-hours and premarket trading.
SpaceX posted revenue of $14.6 billion, a 161 percent year-over-year increase that comfortably topped consensus estimates, which fell near $12.7 billion. The company also posted a net profit of $4.4 billion from a prior-year loss, with adjusted EBITDA reaching $8.8 billion.
More price target movement:
🚀 Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
🚀 Barclays raised its target to $300 from $254 (Overweight).
🚀 Citi increased its target to $240 from $200 (Buy),
🚀 UBS moved to $230 from $210 (Buy)
🚀TD Cowen raised its target to $224 from $200 (Buy).
🚀Morgan Stanley held an Overweight rating with a $300 target.
🚀Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.— TESLARATI (@Teslarati) October 21, 2026
Its Super Intelligence (AI) division generated roughly $7.6 billion and became the largest revenue contributor, growing nearly 830 percent year-over-year, while the Connectivity segment delivered $5.2 billion on strong subscriber additions that lifted the consumer base to 13.6 million for Starlink.
The Earnings Call proved especially catalytic, as CEO Elon Musk and CFO Bret Johnsen outlined Q1 2027 revenue guidance of $33 billion to $37 billion, which was far above the roughly $22 billion analysts had modeled, alongside fourth-quarter capital-expenditure plans of $35 billion to $40 billion focused on AI compute infrastructure at sites including Memphis and Southaven.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
Management targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end and discussed pathways to 13 gigawatts or more by the end of 2027. Musk described relentless demand from hyperscalers and other customers, with compute pricing supporting payback periods of less than a year and potentially as short as six months.
Additional highlights included Starship’s recent orbital success and V3 satellite deployment, Starlink pricing and enterprise momentum, rapid Grok Bot adoption, spectrum expansion plans, and the formation of special committees to explore a possible combination with Tesla.
These elements prompted a wave of price-target increases:
- JPMorgan more than doubled its target to $500 from $240 while maintaining an Overweight rating.
- Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
- Barclays raised its target to $300 from $254 (Overweight).
- Citi increased its target to $240 from $200 (Buy),
- UBS moved to $230 from $210 (Buy), and
- TD Cowen raised its target to $224 from $200 (Buy).
- Morgan Stanley held an Overweight rating with a $300 target.
- Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Shares, which closed at $147.79 on October 20, jumped roughly 8 percent in early premarket trading on October 21 as investors digested the results and the newly elevated Street targets.
The average analyst price target has moved higher, which reflects greater conviction in SpaceX’s trajectory across launch, connectivity, and the Super Intelligence business, even as elevated spending remains a point of focus.

Tesla reports Q3 Earnings today: here’s what to expect

SpaceX confirms Starship 15 launch window with massive ambitions

SpaceX stock gets a slew of price target boosts after bullish earnings call

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


