News
History Lesson: The evolution of the electric car [Infographic]

The Institute for Local Self-Reliance (ILSR) recently released an in-depth report on electric vehicles. The ILSR’s report, Choosing the Electric Avenue – Unlocking Savings, Emissions Reductions, and Community Benefits of Electric Vehicles, authored by John Farrell, is a treasure trove for those looking to learn more about electric vehicles. One particular section of ILSR’s report provides a helpful history lesson to better understand the evolution of the electric car.
Farrell writes, “Electric cars aren’t new. At the dawn of the U.S. auto industry in the late 1800s, electric vehicles outsold all other types of cars. By 1900, electric autos accounted for one-third of all vehicles on U.S. roadways. Of the 4,192 vehicles produced in the U.S. and tallied in the 1900 census, 1,575 were electric.”
Some well-recognized names were heavily involved with electric cars early on. “Electric vehicles sales remained strong in the following decade and provided a launchpad for fledgling automakers, including Oldsmobile and Porsche, that would go on to become industry titans. Even Henry Ford partnered with Thomas Edison to explore electric vehicle technology. Battery-powered models, considered fast and reliable, sparked a major transportation renaissance.”
 |
Above: Porsche’s first car in 1898, the P1, was electric (Source: Upworthy via Porsche)
That said, electric cars fizzled out as gas-powered cars gained prominence: “the momentum shifted over the first few decades of the 20th century, as the electric starter supplanted hand-cranking to start gas engines. The prices of those models dropped. A network of inter-city roadways enabled drivers to travel farther — more easily done in those days in gas-powered vehicles — and the discovery of domestic crude oil made gasoline cheaper. The internal combustion engine gained a superiority that would persist for decades.”
Fast forward: “Nearly 100 years later, a second wave of electric vehicles arrived, driven by California’s zero-emissions vehicle policy in the late 1990s. Unfortunately, it faltered. The enthusiasm of electric vehicle owners couldn’t overcome the reluctance of cash-flush automakers to invest in alternatives to gas-powered vehicles. Automakers also mounted successful lobbying efforts to weaken the zero-emissions vehicle policy.”
Above: Top 8 electric cars ahead of their time (Youtube: FIA Formula E Championship)
This short-lived second wind for electric cars came to an abrupt end when, “In 1999, General Motors ended production of its own promising electric vehicle, the EV1, after just three years. The automaker removed all 1,100 models from the roads, despite outcry from their drivers. It blamed its pivot away from electric vehicle technology on the EV1’s 100-mile range and the high cost of development compared to sales. Oil giants, still powerful political lobbies, also opposed electric vehicle innovation.”
However, it finally appears that the electric car is here to stay (and thrive) at last. “Nearly two decades later and 120 years after its introduction, the electric car is making an unmistakable comeback. This time, it’s aided by better technology as well as environmentally sensitive consumers and policymakers looking to supplant fossil fuel use with renewable electricity.”
The ILSR’s report concludes that much of the electric vehicle’s recent turnaround is due to the efforts of Elon Musk and Tesla. But, it’s not just Tesla, the past few years have been encouraging industry-wide: “Sales of electric cars are growing… In just the first quarter of 2011, for example, more electric cars were sold than General Motors leased throughout the entire 1990s. In 2016, U.S. auto dealers recorded 158,000 plug-in vehicle sales — up more than 30 percent from 2015. The trend shows no signs of stopping.”
For a timeline of EV milestones dating all the way back to 1832, be sure to check out this handy infographic…
Infographic
 |
===
Note: Article originally published on evannex.com, by Matt Pressman
Source: Institute for Local Self-Reliance / Infographic: Nikkei Asian Review



SpaceX reported its third-quarter 2026 financial results on October 20, posting the company’s first solidly profitable quarter since going public earlier in the year under the ticker $SPCX.
Revenue reached $14.58 billion, up 161 percent year-over-year from $5.6 billion, and well ahead of consensus estimates in the $12.7 to $12.9 billion range. The results highlight a rapid shift in SpaceX’s center of gravity toward artificial intelligence/super intelligence, while Starlink and traditional space operations continue to show robust progress.
Here are the key financial results for the quarter:
- Revenue of $14.58 billion (+161% YoY)
- Adjusted EBITDA of $8.8 billion (+306% YoY)
- GAAP net income of $4.4 billion (versus a $1.1 billion net loss in the prior-year quarter)
- Adjusted EPS of approximately $0.35 (versus roughly $0.13–0.16 expected)
- Income from operations of $2.8 billion
The AI/SI segment generated $7.56 billion in revenue, an 830 percent year-over-year increase, making it the company’s largest segment for the first time. Growth was primarily driven by the activation of major cloud services agreements, the integration of Cursor (acquired earlier in 2026), and rising usage of Grok models and the newly introduced Grok Bot personal agent.
🚨 SpaceX just reported earnings! Here are some highlights:
Financial:
Revenue $14.58B (+161% YoY) vs. consensus ~$12.7–12.9B
Adjusted EBITDA $8.8B (+306% YoY)
GAAP net income $4.4B (vs. prior-year loss; first solidly profitable quarter post-IPO)
Adjusted EPS ~$0.35 vs. ~$0.13–0.16 expectedSegments:
Super Intelligence (SI, formerly AI): $7.56B (+830% YoY) — now the largest segment, driven by cloud contracts, Cursor, and Grok.
Connectivity (Starlink): $5.25B (+69% YoY).
Space: $1.77B.Other highlights:
Starlink subscribers: 13.6M (+89% YoY).
Nameplate compute: 1.7 GW.
Capex: $19.6B (majority AI infrastructure).
Cash & marketable securities: ~$90B.
First revenue-generating Starship mission (26 V3 Starlink satellites, ~10× Falcon 9 downlink capacity per launch).— TESLARATI (@Teslarati) October 20, 2026
SI adjusted EBITDA reached $5 billion, and nameplate compute capacity stood at 1.7 GW at quarter-end, up from 1.4 GW in June and 0.6 GW a year earlier. Capital expenditures totaled $19.6 billion, with the majority allocated to AI infrastructure, including continued expansion of the Colossus facilities.
The Connectivity segment, which primarily surrounds Starlink, produced $5.25 billion in revenue, a 69 percent year-over-year and 22 percent sequentially. These are pleasant results to see and expected, considering how many airlines have adopted Starlink over the past year.
Starlink consumer subscribers reached 13.6 million, an 89 percent increase from the prior year, and a sequential gain of 1.6 million. Consumer average revenue per user improved to $69. Meanwhile, Enterprise and Government revenue also grew strongly, and Starlink is now installed on more than 3,800 aircraft, making internet more accessible and better performing than previous options.
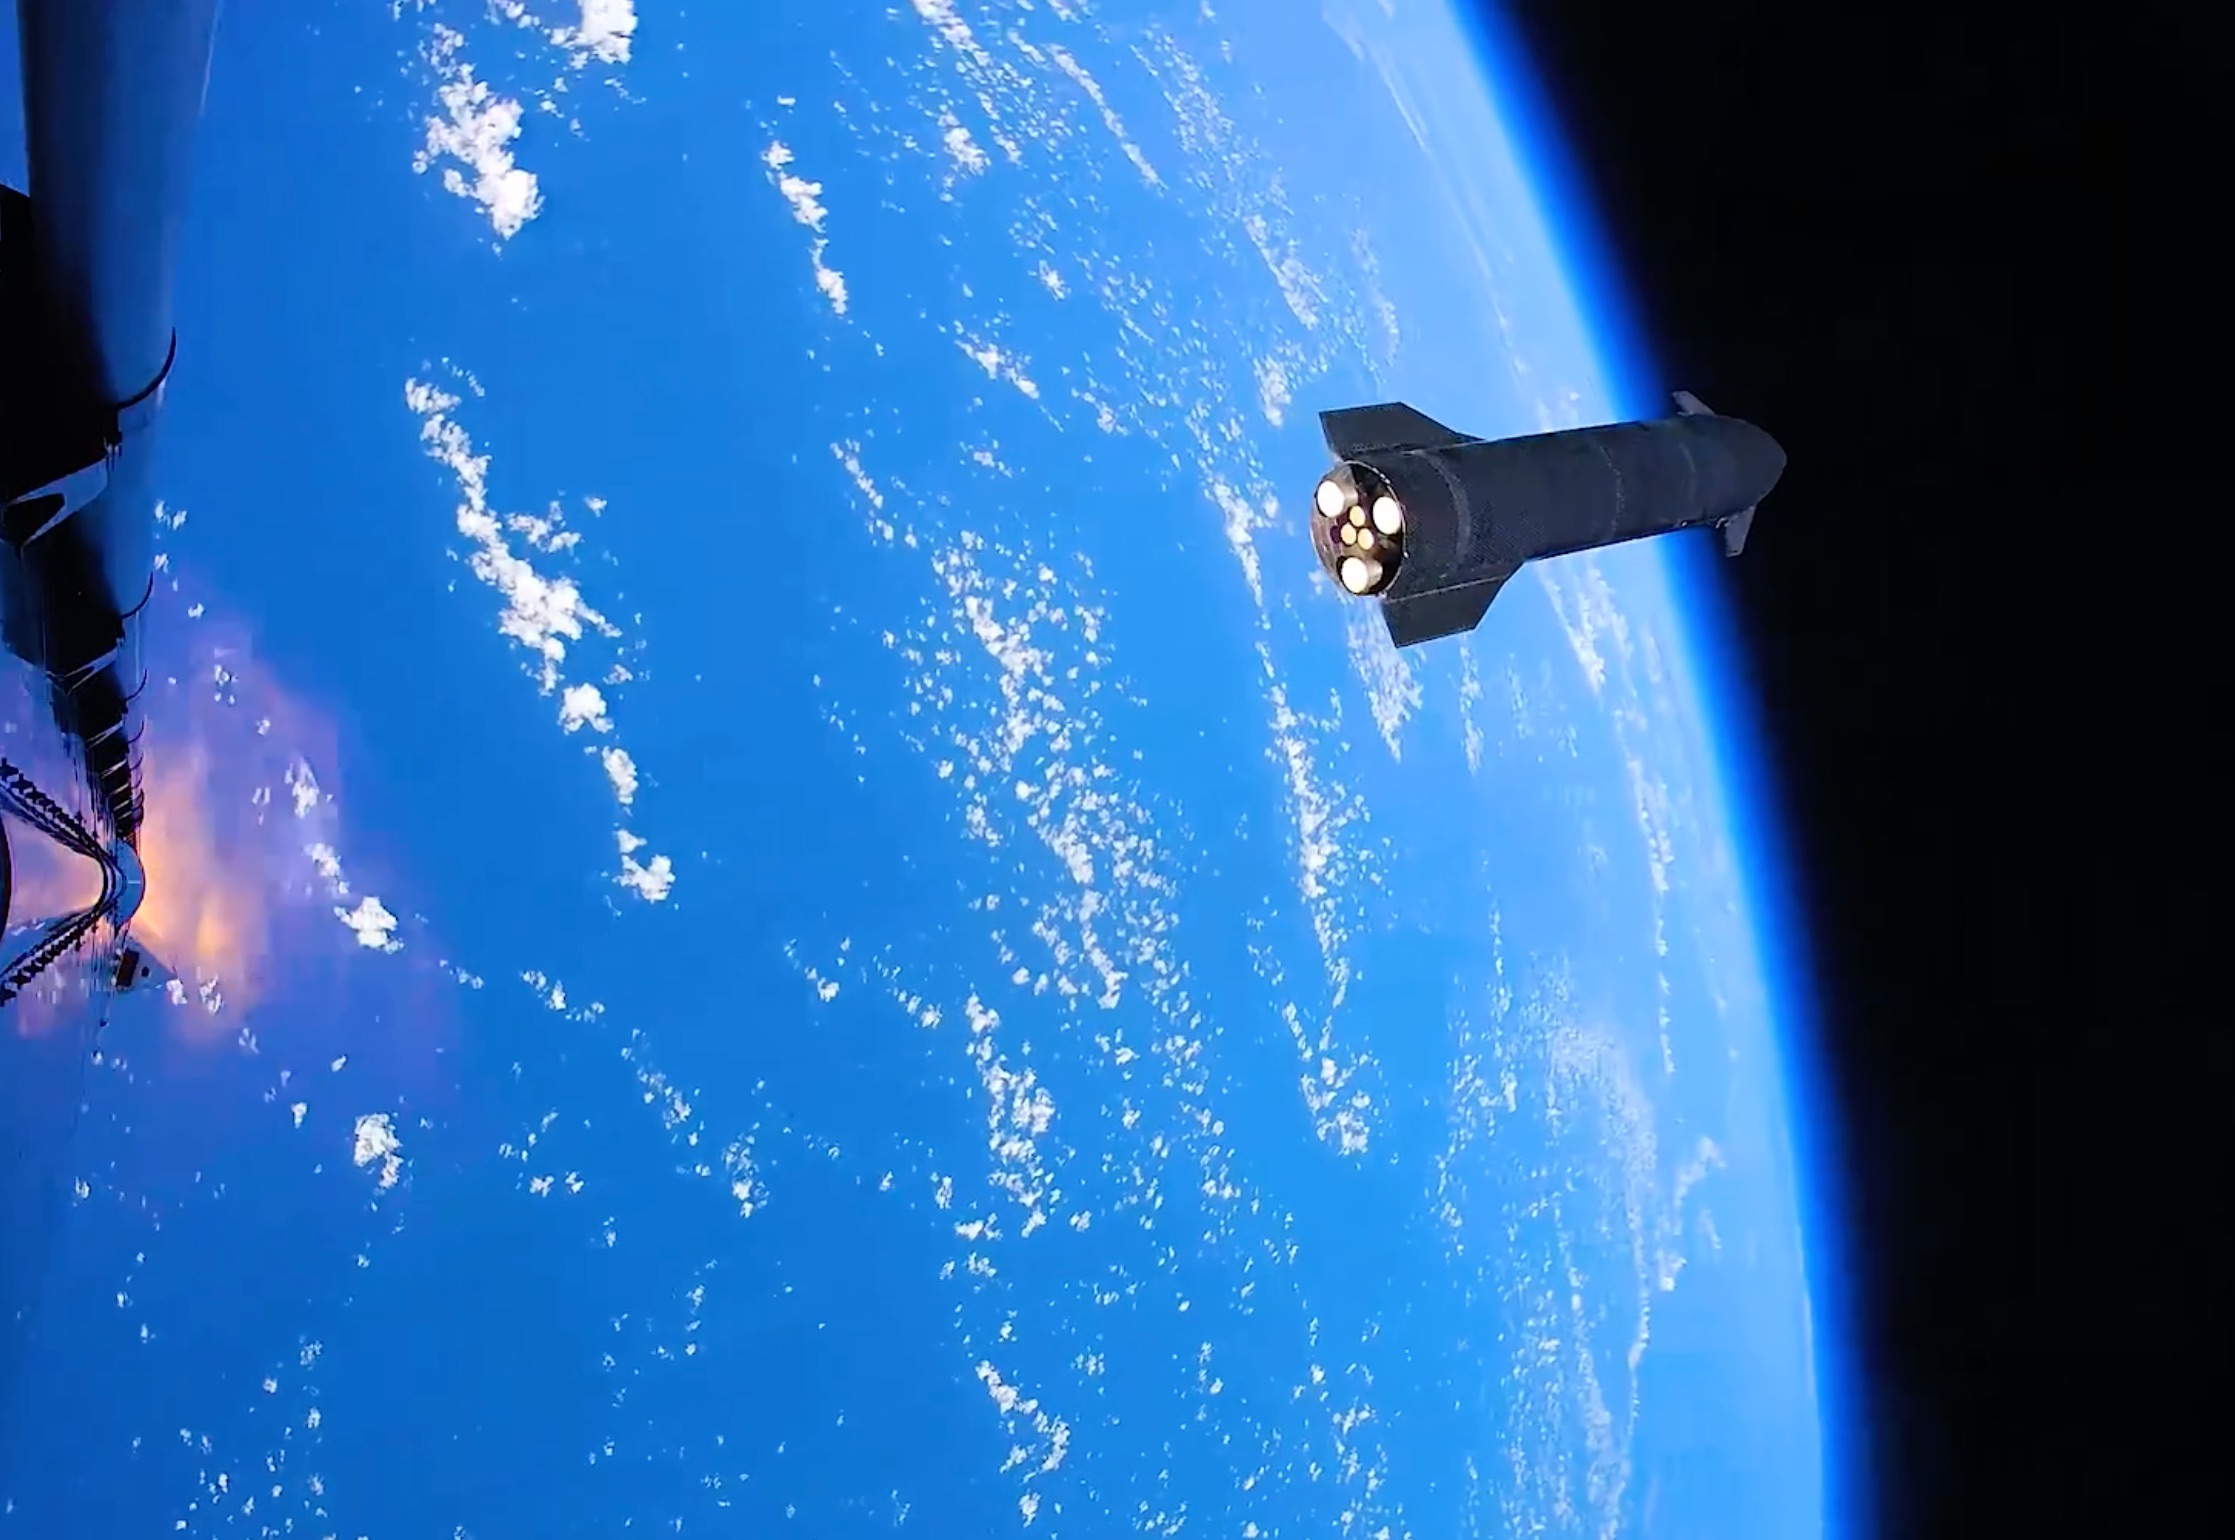
The Space segment also performed well and contributed $1.77 billion in revenue, up 6 percent year-over-year and 84 percent sequentially. A major milestone was the successful first revenue-generating Starship mission (Flight 14), which deployed 26 V3 Starlink satellites. Those satellites added roughly 10 times the downlink capacity of a typical Falcon 9 Starlink launch.
SpaceX completed 12 customer launches during the quarter, including NASA’s Nancy Grace Roman Space Telescope mission, and continued to grow its backlog of crewed, national security, and commercial flights.
CFO commentary noted that the combination of launch leadership, recurring Starlink revenue, and rapid SI expansion is producing meaningful operating leverage.
The company ended the quarter with roughly $90 billion in cash and marketable securities, providing substantial resources for ongoing investment while targeting an investment-grade balance sheet. Sequential revenue nearly doubled from the $7.81 billion reported in the second quarter, illustrating the pace of the AI-driven acceleration. Things are looking strong for SpaceX.
What’s incredibly striking is the fact that SI has grown to be larger than the rest of the company in such a short amount of time. CEO Elon Musk said on the earnings call that Grok Bot is the “fastest-growing product I’ve ever seen,” so it seems that it could be a true keystone of SpaceXSI over the next few years.
SpaceX (NASDAQ: SPCX) will report its second public earnings call today since its IPO earlier this year, and there are a few things we expect to hear about, as well as Wall Street analysts, who have already outlined their expectations for the call.
Wall Street analysts have a consensus of $12.72 billion in revenue and an earnings per share (EPS) of $0.13. These are broken down into three sectors: Space, Connectivity, and AI/SI, which are perceived in this way:
- Space: $1.41 billion
- Connectivity: $4.84 billion
- AI/SI: $6.47 billion
Other outlets cluster near $12.8 or $12.9 billion in revenue and $0.14 – $0.15 EPS. This implies a roughly 65 percent sequential growth from Q2’s $7.81 billion, driven mostly by AI/SI, with the first post-IPO positive EPS expected.
Here are the three things to watch for on the call:
AI Revenue Ramp and the $100B+ ARR target
AI is truly the swing factor for SpaceX, and analysts expect it to roughly double from Q2’s $2.56 billion and become about half of total revenue. Management previously guided to a $100 billion+ annualized run rate by December, including the Cursor acquisition, which was $60 billion, to close the quarter.
Listen for updates on SpaceX’s compute capacity, especially pertaining to its contracts with Google, Anthropic, and others, revenue per watt, any new deals, and Cursor’s early contribution.
Starlink/Connectivity Metrics and Mobile Expansion
Connectivity remains a main profit engine for SpaceX. Subscriber additions will be something to pay attention to, as Q2 ended at 12 million and previews are looking at 14 million for this quarter. Additionally, ARPU trends, enterprise and government growth, and any commentary on Starlink Mobile will be something to pay attention to, especially following the recent low-band spectrum deal and FCC-related constellation approvals.
Capex Trajectory, Cash Burn/FCF, and Starship/Operational Updates
Q2 capex of roughly $18.4 billion weighed on the stock. Investors will look to scrutinize Q3 spending levels, any guidance on the pace into Q4/2027, free cash flow, backlog, and liquidity. Operational color on Starship (Flight 14 milestones and Flight 15 timing/reusability progress), Falcon cadence, and government/NASA contracts are also in focus.
Of course, there will also be some speculation on the potential Tesla-SpaceX merger, but there was nothing mentioned in the company’s proxy it sent earlier this week.
SpaceX will report earnings after market close today and will stream the call on X.
Watch live as SpaceX discusses our Q3 2026 earnings at 3:30pm CT today → https://t.co/Qrb0qeVG15
— SpaceX (@SpaceX) October 20, 2026
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here
News
SpaceX just launched its secret Starfall saucer again
SpaceX launched its Starfall capsule again on Bandwagon-5, this time listed openly beside rideshare customers.

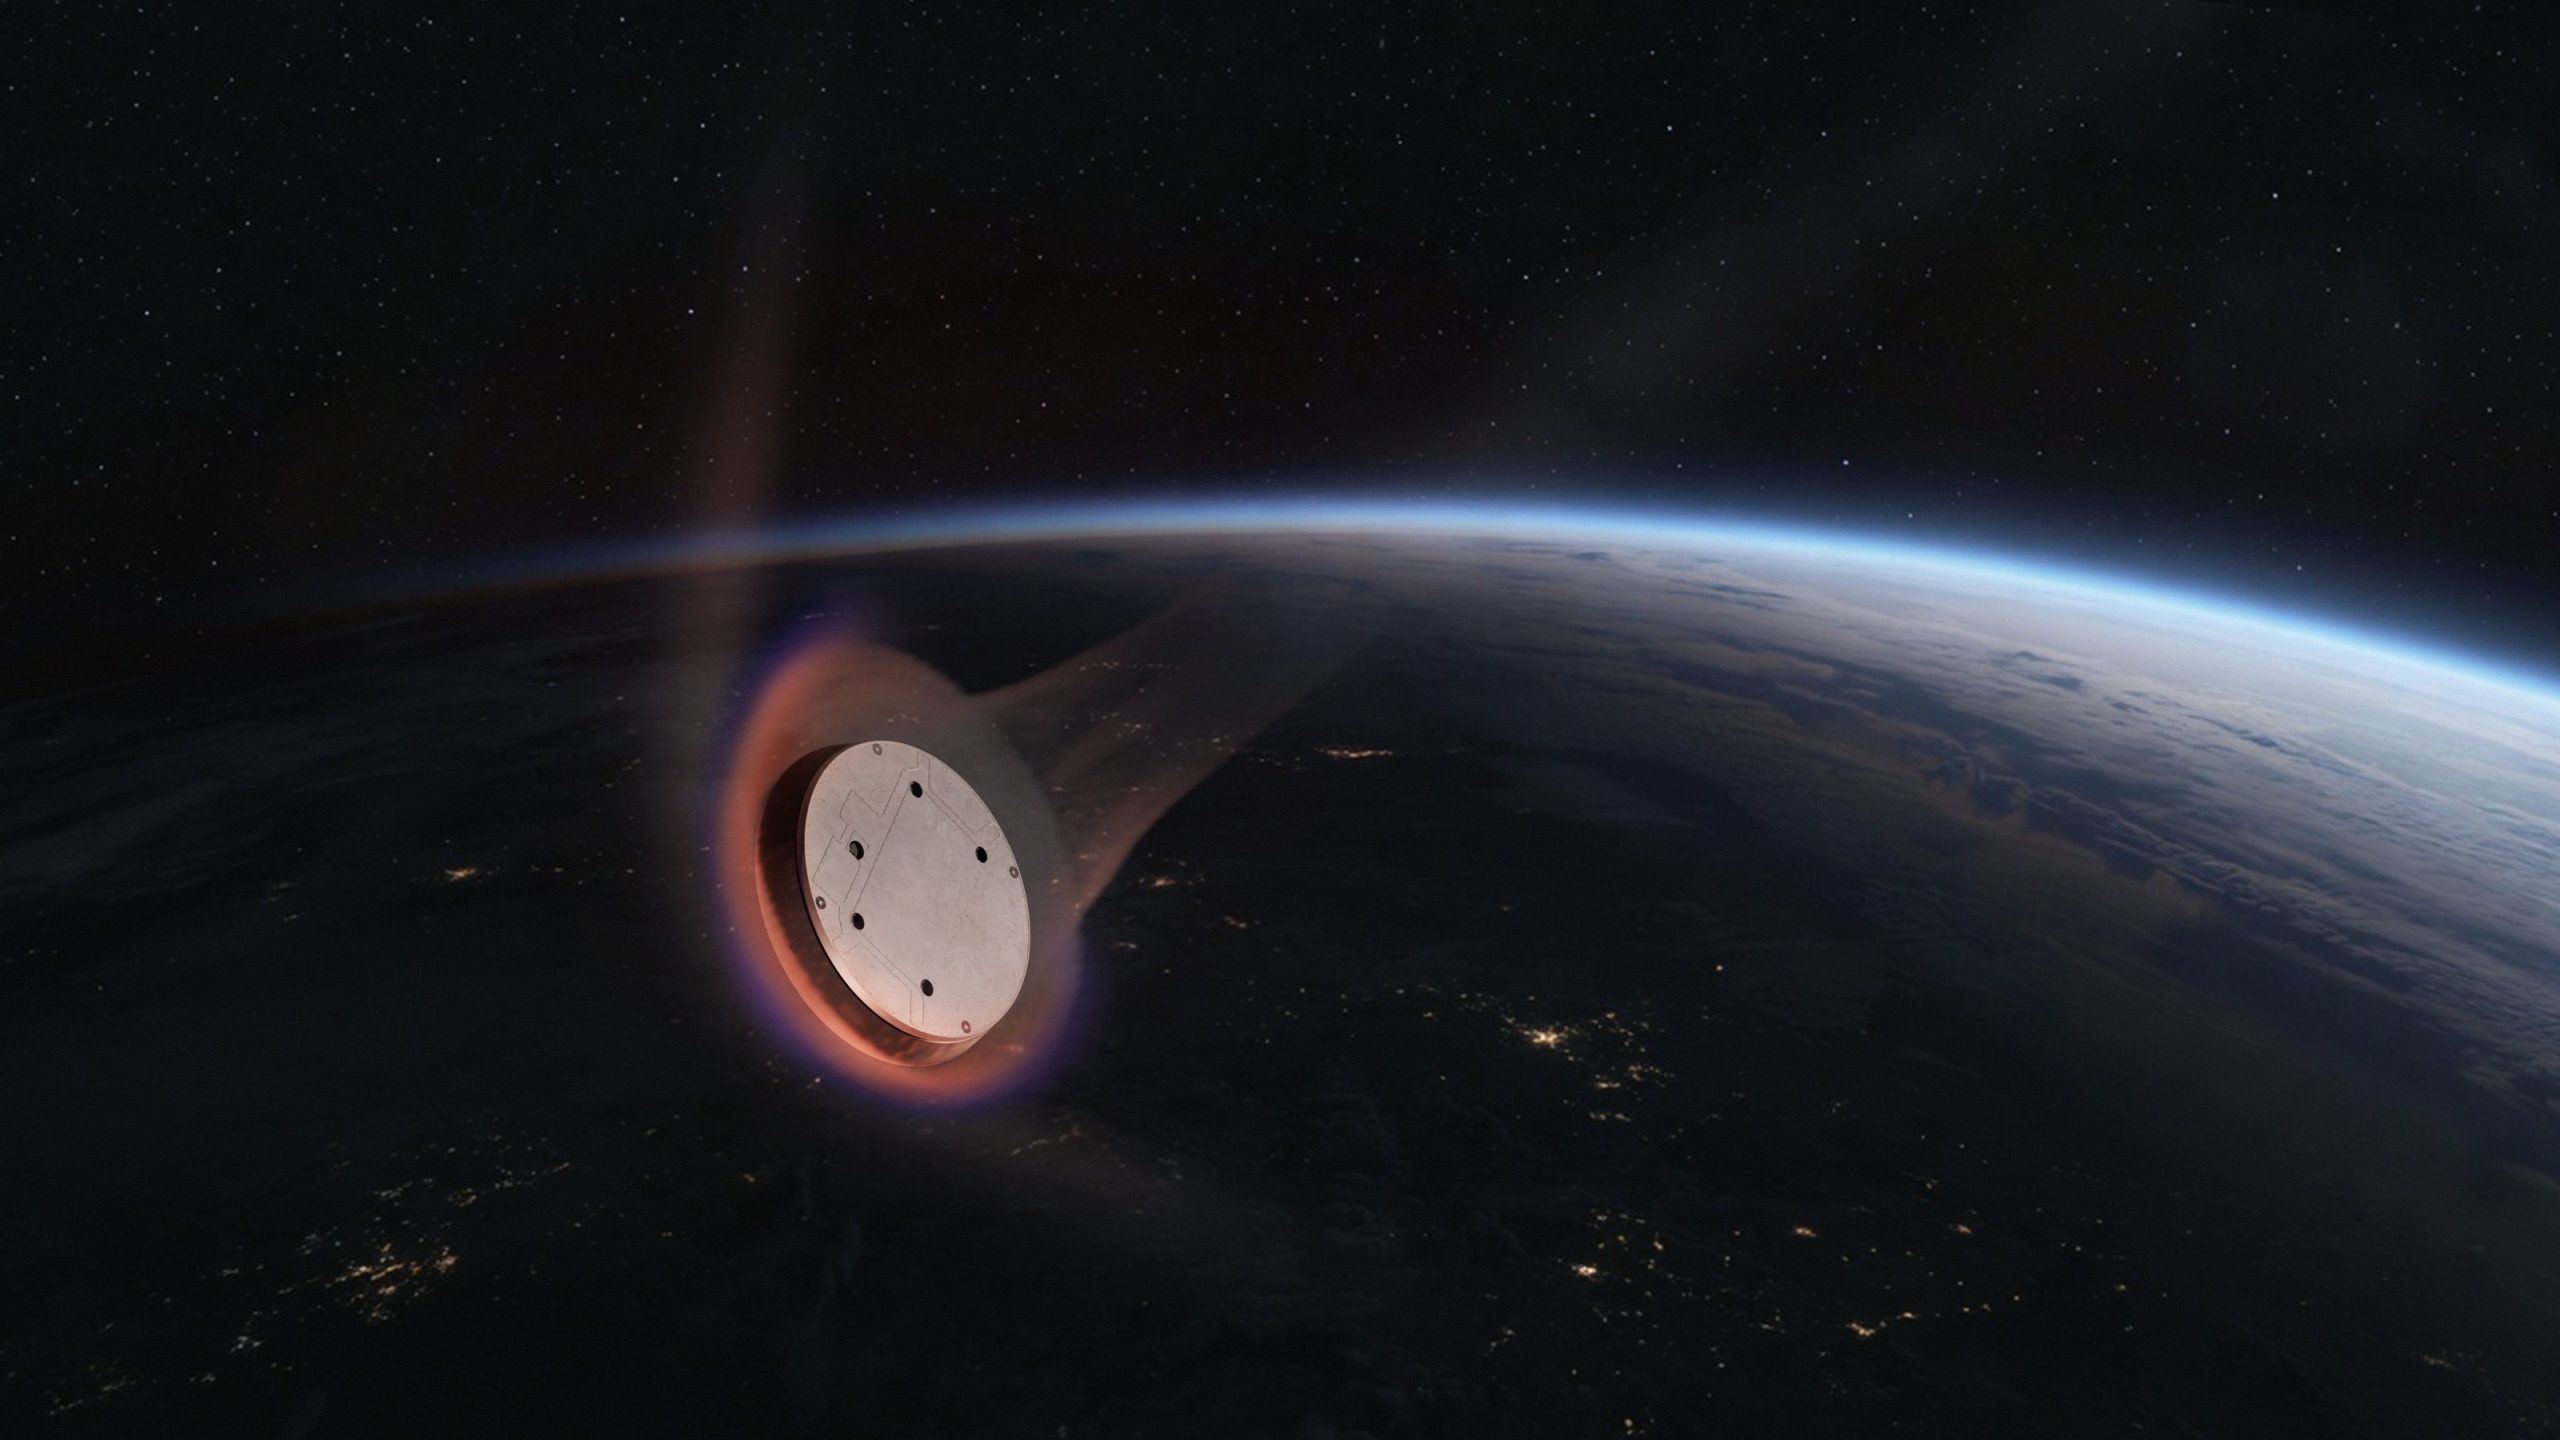
SpaceX launched its Starfall reentry capsule for the second time on Tuesday morning, flying it as the payload of the Bandwagon-5 rideshare mission. Falcon 9 lifted off from Space Launch Complex 40 in Florida at 7:04 a.m. ET with 32 payloads, and the first stage booster, on its 19th flight, landed on the droneship A Shortfall of Gravitas about nine minutes later.
Starfall was scheduled to separate last, 2 hours and 48 minutes after liftoff. The final customer satellite on SpaceX’s mission timeline comes off the upper stage about an hour and nine minutes in, which left a long gap before the capsule was due to be released alone. SpaceX later posted that the payload deployment sequence is complete. At liftoff, the company said Starfall “enables affordable, routine access to a microgravity environment, providing unique opportunities for on-orbit manufacturing, scientific research, and testing.”
Starfall enables affordable, routine access to a microgravity environment, providing unique opportunities for on-orbit manufacturing, scientific research, and testing https://t.co/y8kJg3QDor
— SpaceX (@SpaceX) October 20, 2026
As Teslarati reported before the first Starfall flight, SpaceX made no public announcement about the vehicle then, and nearly everything known came from FAA and FCC filings. This time Starfall is an item name on the official mission page, listed beside paying rideshare customers. SpaceX has still not said what, if anything, is aboard this Starfall, Spaceflight Now noted.
The FAA’s environmental assessment from May describes a disk about 10.2 feet wide and 2.5 feet tall that weighs roughly 4,600 pounds and can bring 2,200 pounds of payload back to Earth.
Interestingly, the same rocket also carries a competitor’s hardware. Varda Space Industries launched its W-Series 7 capsule on Bandwagon-5, a spacecraft about three times smaller than Starfall that will test whether microgravity can improve the solubility of a cancer drug called Protac. It is Varda’s ninth reentry capsule, and W-8 and W-9 launched earlier this month on Transporter-18. SpaceX has been Varda’s launch provider since the company’s first Falcon 9 rideshare contract in 2021.
SpaceX has not published where or how this Starfall will come down. The preview we ran in June described a recovery from the Pacific Ocean, and the company has not said whether this flight follows the same plan. The launch also arrives hours before SpaceX posts its third quarter results after the market closes, a report we previewed earlier this week.

SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms

SpaceX reports its second earnings today: here’s what to expect

SpaceX just launched its secret Starfall saucer again

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


