SpaceX
DeepSpace: A critical juncture for SpaceX, Blue Origin, ULA, other players

This is a free preview of DeepSpace, Teslarati’s new member-only weekly newsletter. Each week, I’ll be taking a deep-dive into the most exciting developments in commercial space, from satellites and rockets to everything in between. Sign up for Teslarati’s newsletters here to receive a preview of our membership program.
A high-pressure competition between all four major US launch providers – SpaceX, ULA, Blue Origin, and Orbital ATK (now NGIS) – is about to head into its most critical stage, a period of 60 days allotted for interested parties to submit their completed proposals. According to the US Air Force (USAF), the final request for proposals (RFP) could come as early as March 29th, giving the four aforementioned companies until May 28th to complete their proposals.
All things considered, the growing pressure and some of the USAF’s strategy behind the program – known as Launch Service Procurement (LSP) Phase 2 – has raised significant questions that remain largely unanswered and lead to a few mild bouts of strife or unhappiness from contract competitors. Most notably, Blue Origin – having just won a USAF development contract worth $500M – has repeatedly requested that the USAF and Department of Defense (DoD) delay the RFP and contract awards until 2021, according to Space News’ Sandra Erwin. Meanwhile, a lack of clarification from the USAF means that it’s unclear whether the strategy behind launch contract awards (LSP) will end up contradicting or undermining a partially connected development program known as Launch Service Agreements (LSA) that saw the USAF award ~$2B to three providers (excluding SpaceX) between 2018 and 2024.
Battle of the Acronyms: LSP vs. LSA
- Recently rebranded by the US military as the National Security Space Launch (NSSL) program, LSP Phase 1 and 2 and LSA are the latest major procurement initiatives begun under the Evolved Expendable Launch Vehicle (EELV) program, spun up in the 1990s to provide a firmer foundation for the commercial launch of military spacecraft after the 1986 Shuttle Challenger disaster pushed most satellites off of the platform.
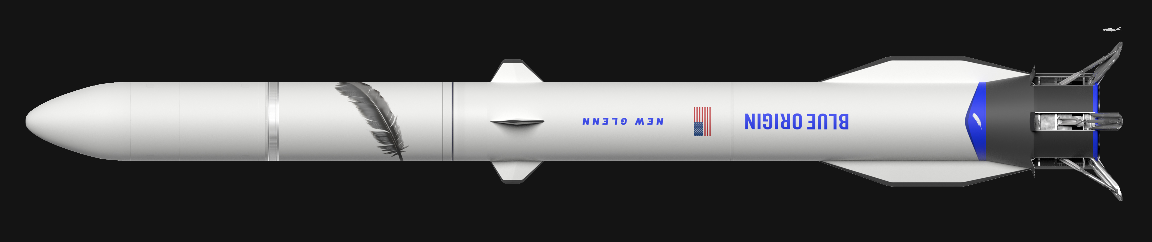
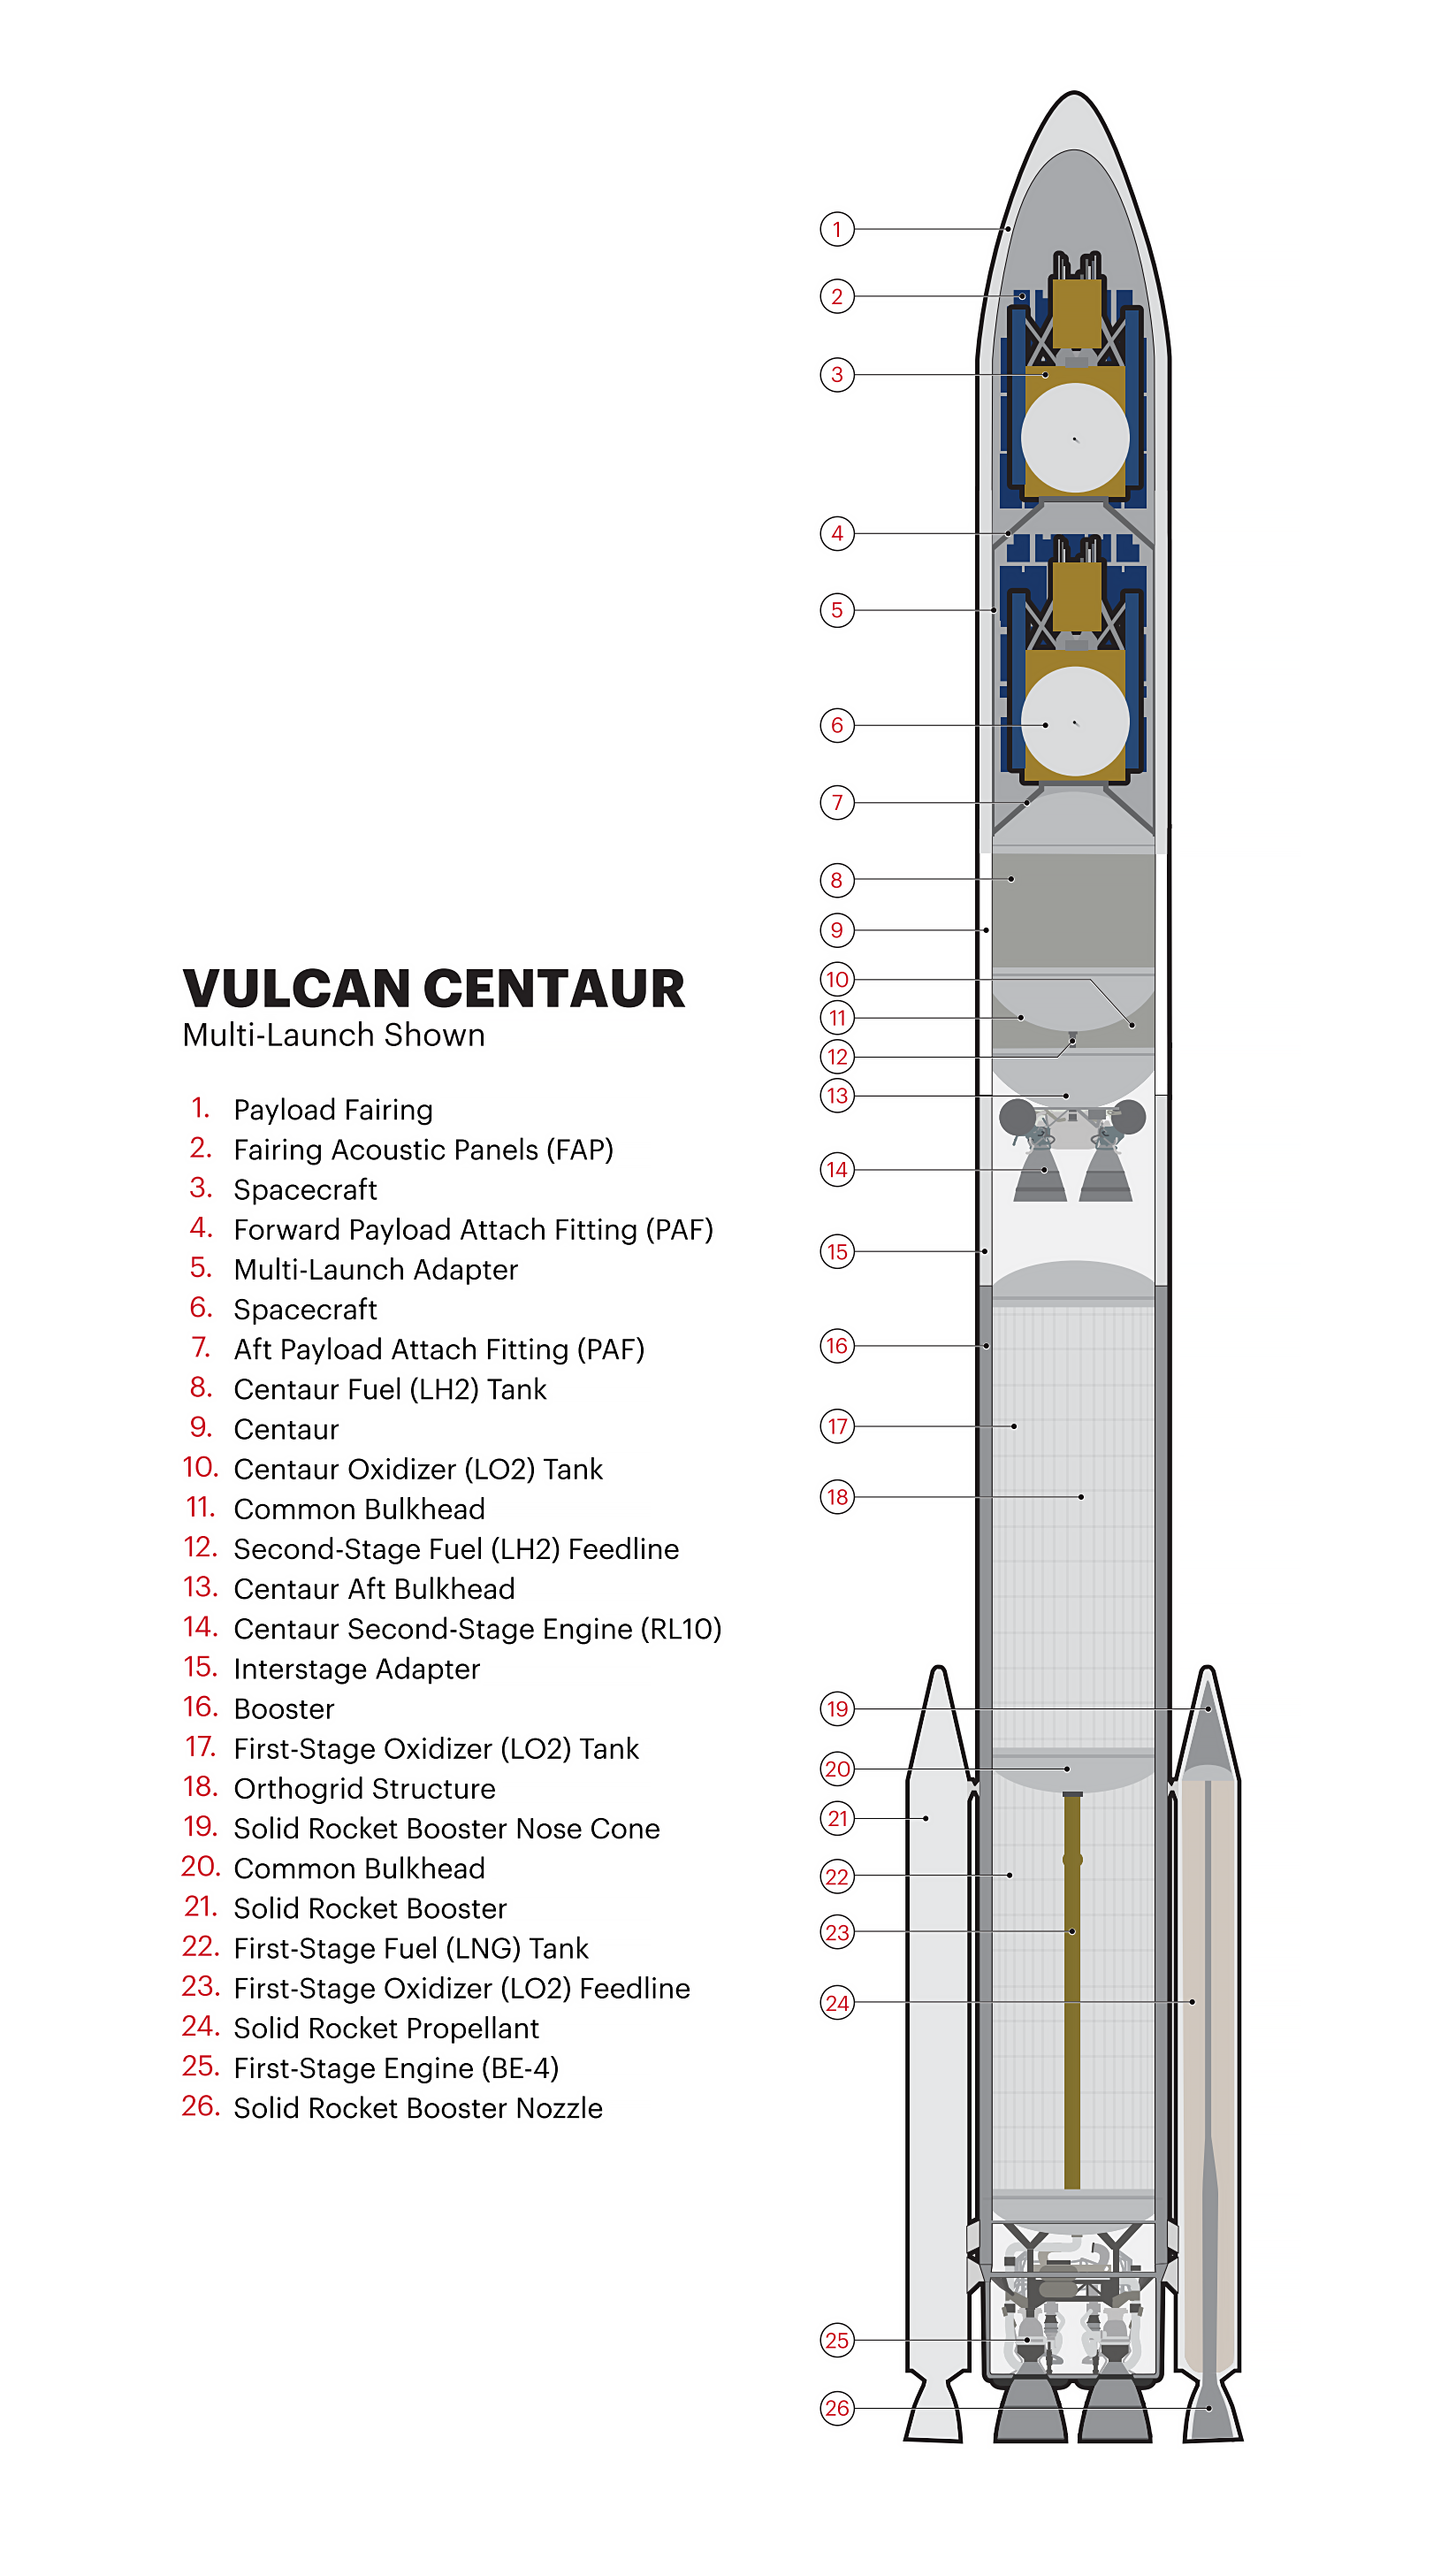
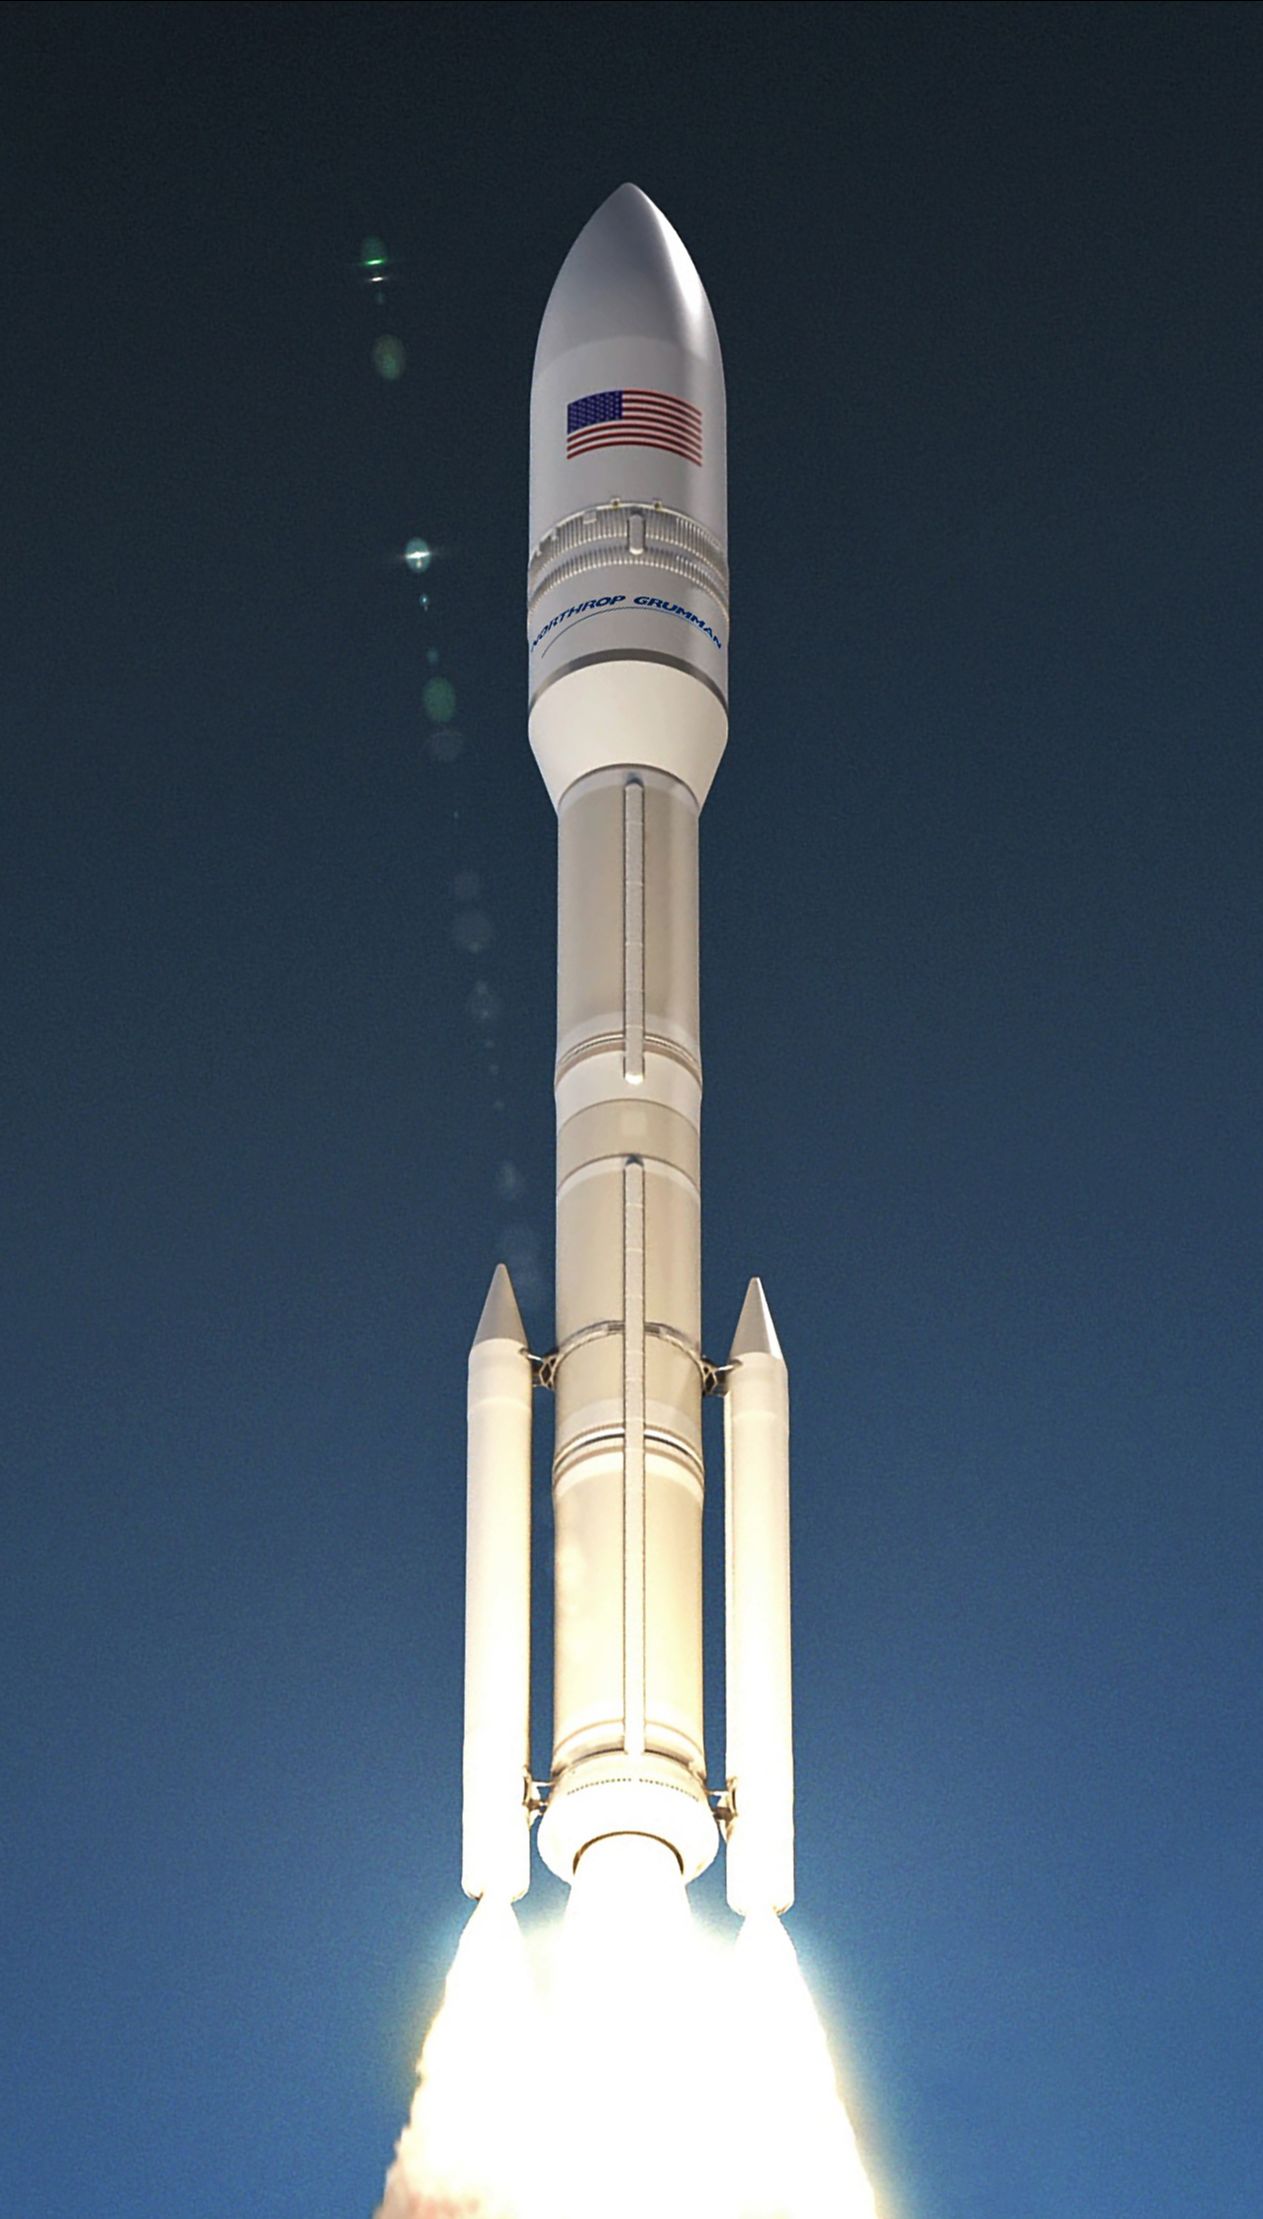
- Phase 2 of the EELV program has been ongoing for several years and will culminate with the procurement of 25+ launch contracts (LSP) from two providers no earlier than 2020. The USAF’s Launch Service Agreements are also a major strategic feature of Phase 2, nominally seeing the military branch contribute major funding to assist in the development of three separate launch vehicles (New Glenn, Vulcan, and Omega) with the intention of ultimately certifying those rockets for EELV (now NSSL) launches.
- LSA also saw the USAF award several tens of millions to SpaceX, Blue Origin, and Aerojet Rocketdyne to develop capabilities centered around advanced, new rocket engines (BE-4, AR-1, and Raptor), but the latest phase of LSA is valued at least several times higher than its earlier engine-specific awards.
-
- Oddly, the purpose of LSA was – at least on the cover – to effectively ensure that the Air Force had multiple (more than two) providers and thus preserve a healthy, competitive military launch market. A senior leader specifically stated that “the goal of [LSA] is to make sure [the US military has] a competitive industrial base.”
- Aside from an initial $181M awarded to Blue Origin, ULA, and Orbital ATK (now Northrop Grumman Innovation Systems, NGIS) in 2018 and 2019, the remaining funding – up to $320M for Blue Origin’s New Glenn, $610M for NGIS’ Omega, and $785M for ULA’s Vulcan – would be dispersed to each provider between 2020 and 2024.
- However, an odd and controversial bit of language behind the coming five-year launch services procurement (LSP) initiative would completely cut off funding to LSA awardees in the event that they fail to be awarded launches from the latest LSP.
- Additionally, the LSP awards are strictly meant – apparently very intentionally – to be distrubuted among two launch providers, despite a minimum at least four being able (SpaceX) or required (ULA, Blue, NGIS) to enter a bid.
- In other words, this guarantees that either one or two of the three LSA awardees would have the vast majority of their supposedly awarded development funding cut off after FY2020, four years early.
- Oddly, the purpose of LSA was – at least on the cover – to effectively ensure that the Air Force had multiple (more than two) providers and thus preserve a healthy, competitive military launch market. A senior leader specifically stated that “the goal of [LSA] is to make sure [the US military has] a competitive industrial base.”
- Despite continued protests from a number of stakeholders, the USAF has refused to budge from its decision to simultaneously A) create a duopoly, B) defeat the purpose of LSA awards, and C) mass-award ~25 launch contracts to two providers in 2020, anywhere from 12-24 months prior to the planned inaugural launches of all three LSA-funded rockets.
- Without cost-sharing development funds from the USAF and a chance of winning more than a handful of US military launch contracts between now and the late 2020s, it can be all but guaranteed that an LSA funding cutoff will either indefinitely pause or slow to a crawl a given provider’s development of their proposed launch vehicle.

A rocket and a hard place
- This sticky situation thus offers up a few potential ways that this badly-designed (or entirely dishonest) military launch development and procurement strategy will end up by the end of 2020. One way or another, the current strategy as it stands will end up providing two (or one, given that SpaceX will not receive LSA funding) companies with several years of development funding and at least five years of bountiful, guaranteed launch contracts.
- The four providers and two LSP slots available offer a set range of possible alternate realities, limited by political barriers that would, say, almost invariably prevent the USAF from severely harming ULA by cutting off the vast majority of the company’s only real source of income for 5+ years.
- ULA and SpaceX win: This maintains the status quo, wholly invalidating the point of using LSA funds to ensure “a competitive industrial base.” NGIS likely cancels/freezes all Omega development with no chance of competing in commercial markets. Blue Origin owner Jeff Bezos could significantly delay New Glenn’s readiness for military missions if he fails to invest an additional $500M in infrastructure. Likeliest result: a marginally competitive duopoly.
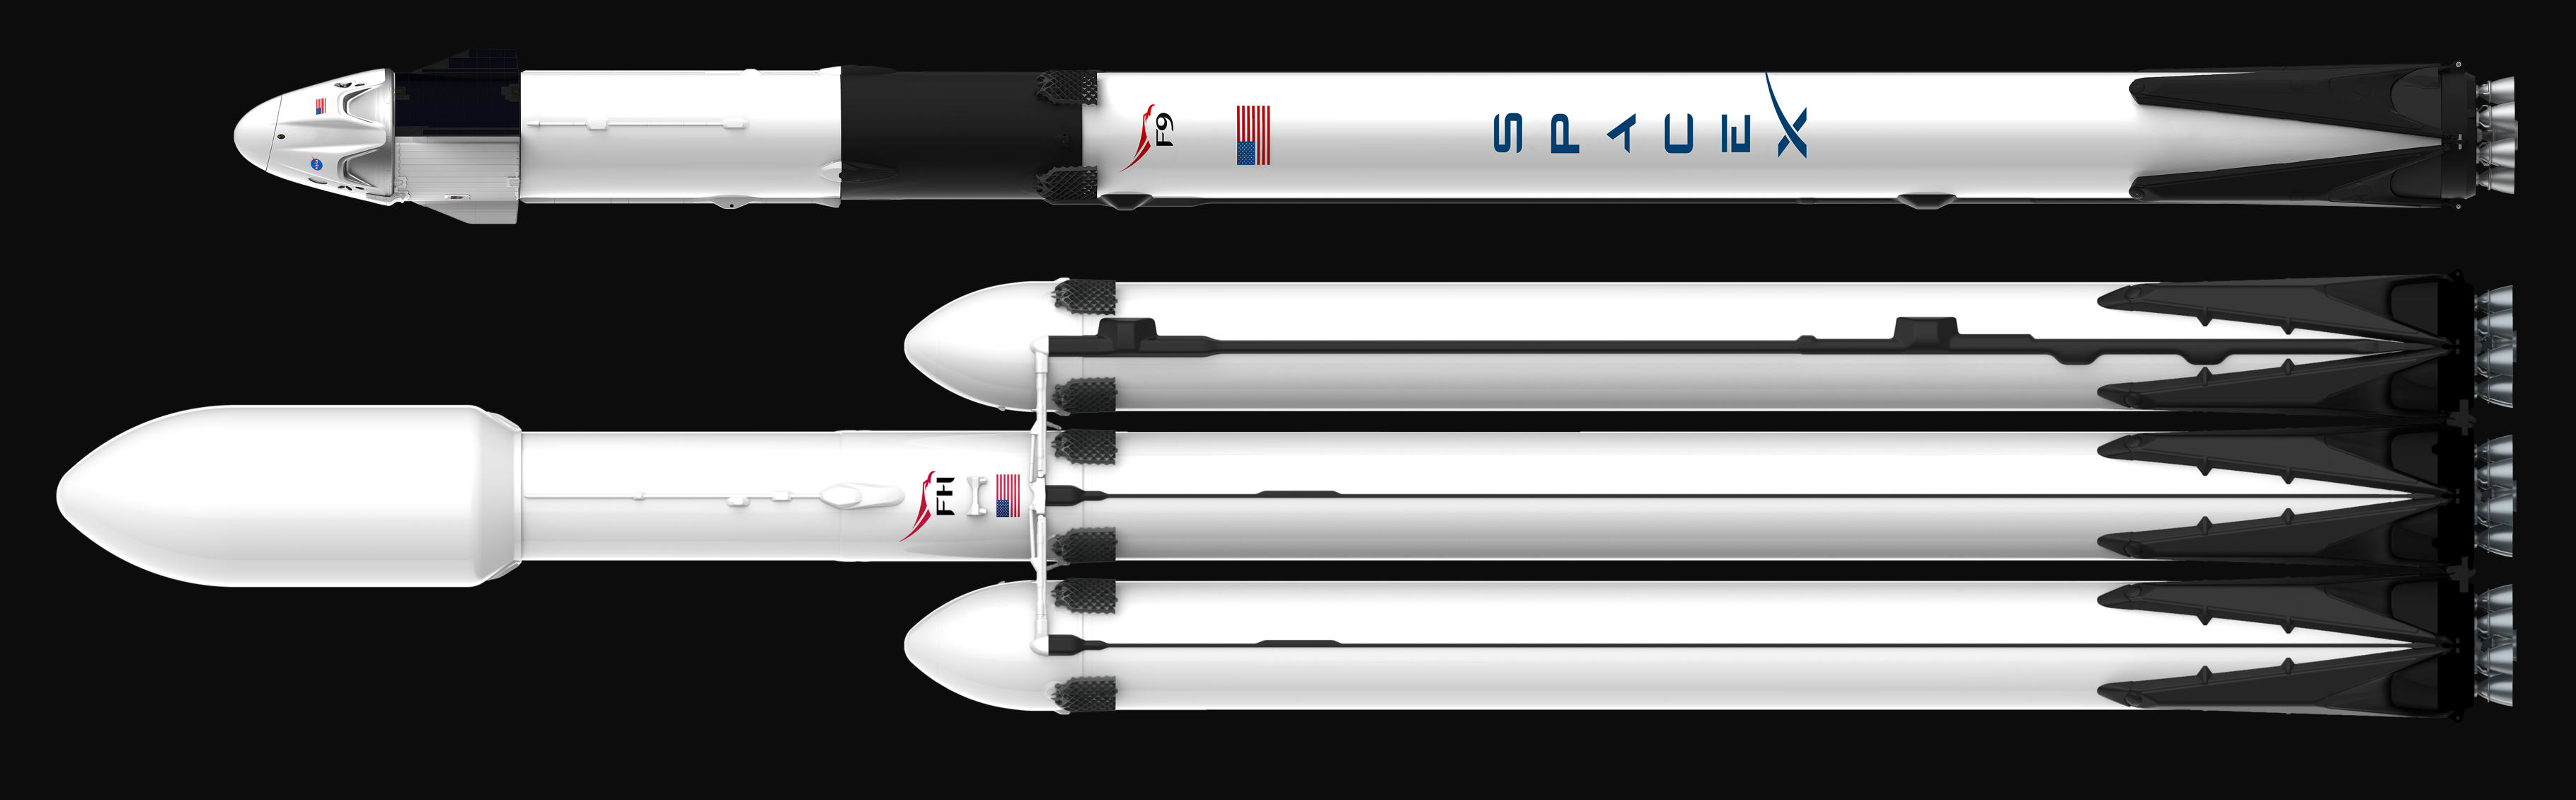
- ULA wins, SpaceX loses: Having just certified Falcon 9 – and nearly Falcon Heavy – for high-value military launches and awarded SpaceX a total of 10 launch contracts (9 yet to be completed), the USAF could effectively spit in SpaceX’s face and award ULA and Blue Origin or NGIS LSP’s 25+ launch contracts.
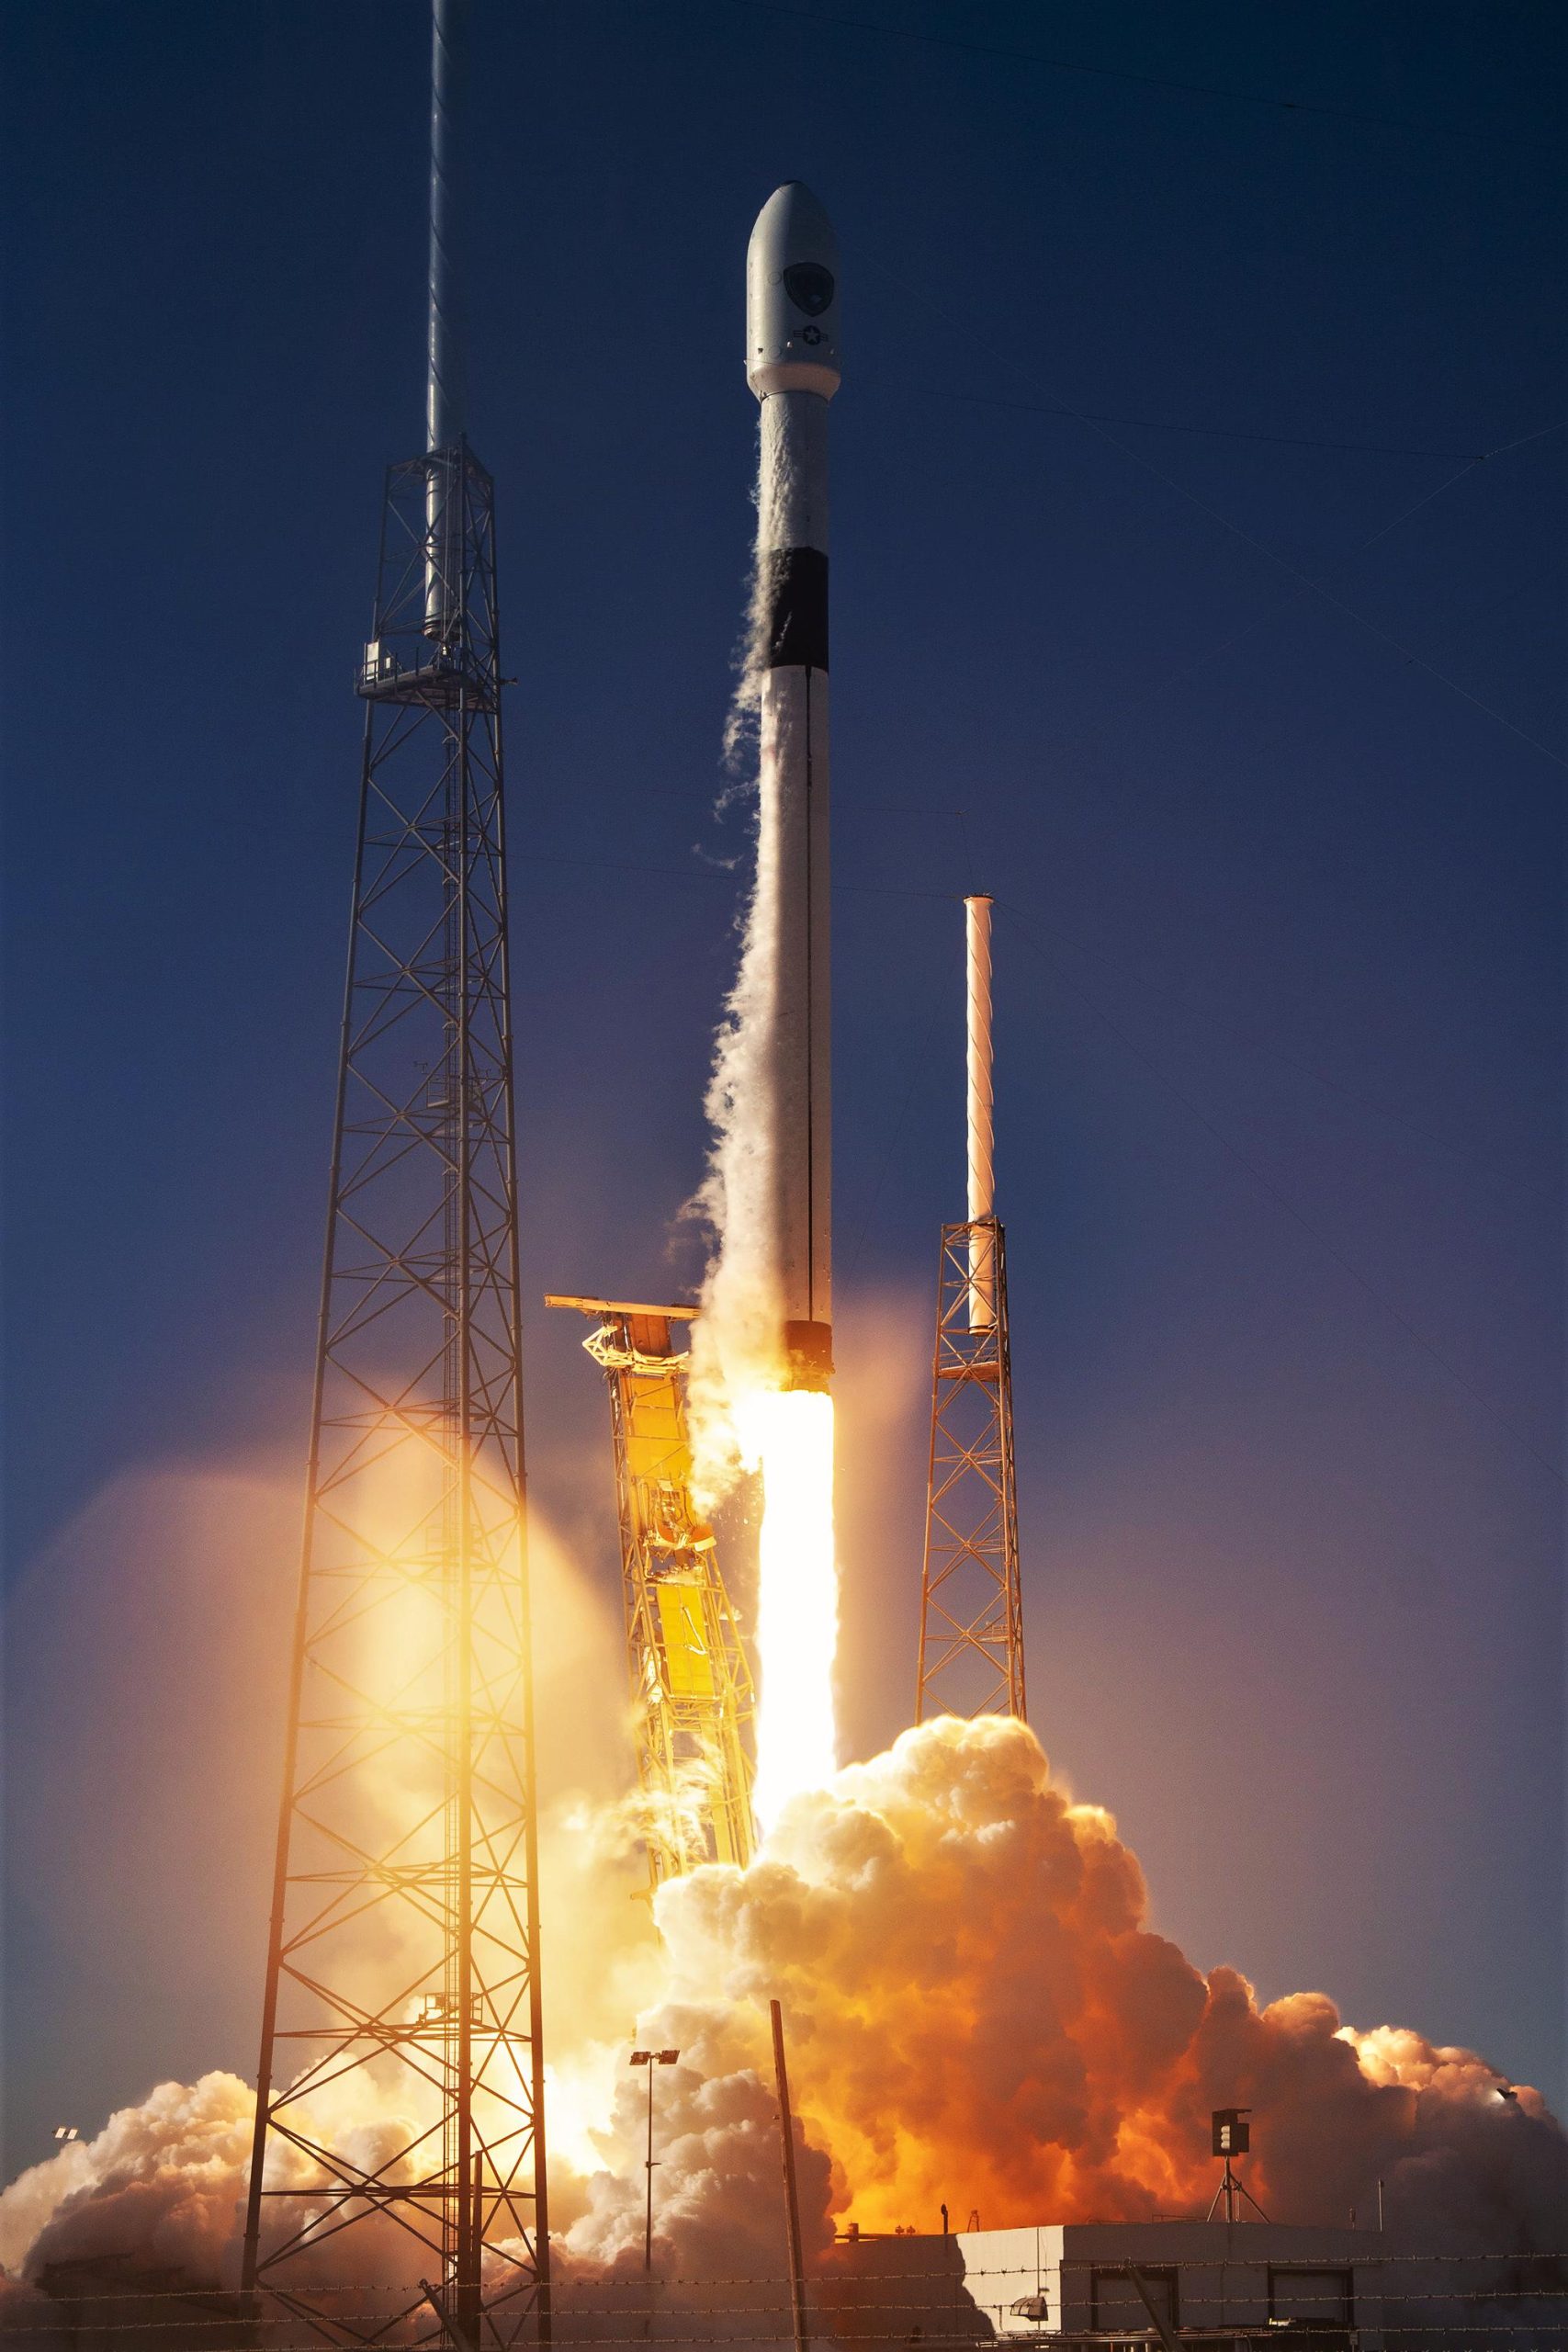
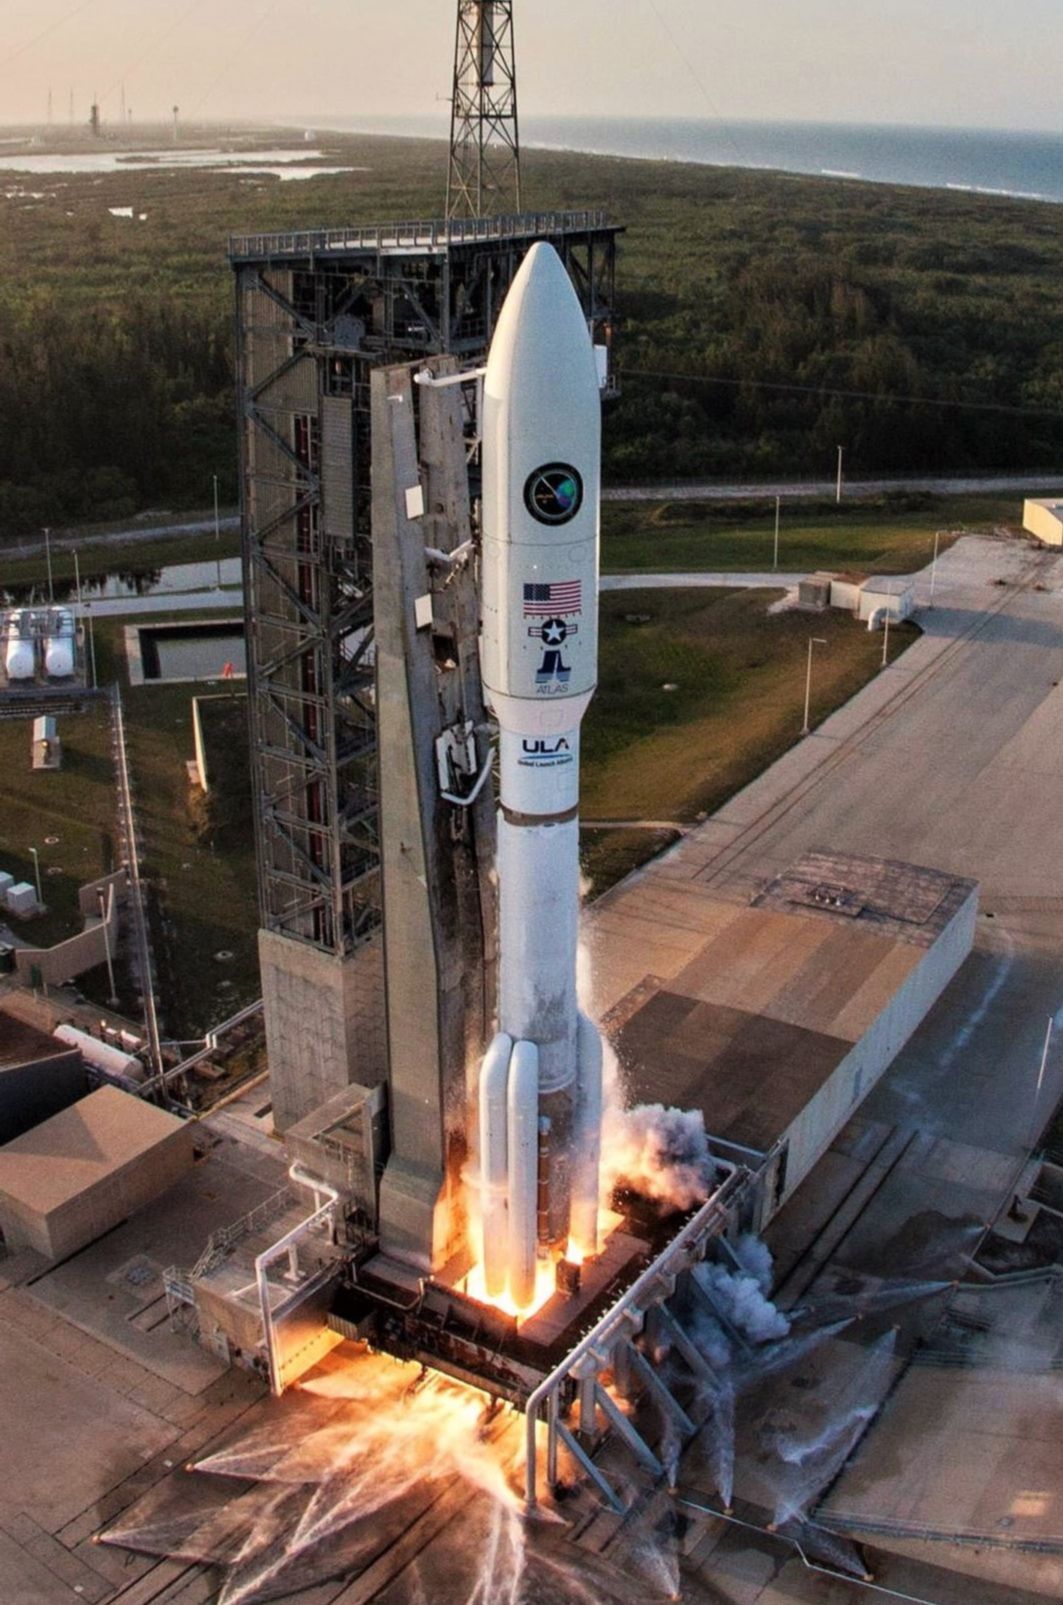
- It’s hard to exaggerate just how much of a slight this would be perceived as by SpaceX and its executives, CEO Elon Musk in particular. The USAF would be risking the creation of a major political enemy, one which has already demonstrated a willingness to take the federal government to court and win. The USAF/DoD would effectively be hedging their bets against an assumption that SpaceX’s nine present military launch contracts will sate the company and ensure that SpaceX indefinitely remains a certified EELV/NSSL provider.
- In this eventuality, either Blue Origin or NGIS would lose LSA funding and the prospect of almost any military launch contracts until the late 2020s. For NGIS, this would likely kill Omega.
- At the end of the day, it’s sadly conceivable that the USAF/DoD may end up awarding LSP contracts to ULA (effectively a politically-forced hand) and NGIS, the latter assuring Omega’s survival. The military would thus be assuming that the political fallout created with SpaceX and Blue Origin would not be enough to severely harm their relationships, while also assuming that their much stronger commercial prospects and independent funding sources would ensure that each provider remains certified and willing to compete for future NSSL/EELV launches.
Regardless of what happens, the contradictory ways the USAF/DoD have structured their LSA and LSP programs seems bizarrely intent on creating major headaches and potential problems where that could easily be avoided with extraordinarily simple changes, namely removing the inexplicable cap and allowing three or more companies to win some of the ~25 LSP launch contracts).
Mission Updates
- The second launch of Falcon Heavy – the rocket’s commercial debut – is still scheduled to occur as early as April 7th.
- After Falcon Heavy, Cargo Dragon’s CRS-17 resupply mission is firmly scheduled for April (April 25th), while the first dedicated Starlink launch is now NET May 2019.
Photo of the Week:

SpaceX CEO Elon Musk offered a glimpse of a 1650 Kelvin (2500ºF/1400ºC) test of Starship’s metallic heat shield, simulating mid-range temperatures such a shield’s windward side might experience during an orbital-velocity reentry.(c. Elon Musk/SpaceX)


Elon Musk said weeks ago during SpaceX’s third-quarter earnings call that the company’s Grok Bot, its autonomous AI Agent platform, was showing “the fastest growth of a product” that he’d ever seen in his life.
Now, SpaceXSI is scaling back Grok Bot users’ weekly limits, much to the surprise of those who have relied on it to take away monotonous tasks in their lives.
Elon Musk’s terse November 1 reply on X captured a sharp tension in the early days of agentic AI. Responding to a user who asked for a Grok Bot usage reset after hitting 100 percent with four days still left on the weekly cycle, Musk wrote: “The cost of serving Grok Bot was unsustainably high relative to revenue.”
@DogecoinNorway The cost of serving Grok Bot was unsustainably high relative to revenue
— Elon Musk (@elonmusk) November 1, 2026
The post arrived amid a wave of similar complaints from paying subscribers whose meters had jumped unexpectedly toward or to the limit, sometimes overnight and with little corresponding activity. It also stood in clear contrast to statements Musk had made only days and weeks earlier.
On the SpaceX third-quarter earnings call in mid-to-late October, Musk had described Grok Bot in almost the opposite terms. He called it “the fastest growth of a product that I’ve ever seen in my life” and said he had “never seen anything grow this fast.”
Company figures put paid weekly users at roughly 800,000 earlier in the month, more than doubling over the prior period. Daily active users had climbed from under 100,000 in early September to over 600,000 by late October.
Musk emphasized that the product has no free tier and that users appear to be getting real value beyond what they pay. In other remarks, he noted that usage per user was rising rather than declining, the opposite of the usual decay pattern for new software.
Grok Bot, launched around August, functions as an always-available agent with its own persistent cloud computer; it can schedule, research, shop, browse, and execute multi-step workflows even after the user steps away. Access is bundled into X subscription tiers (roughly $30, $100, and $200 per month) and certain Cursor plans, drawing from shared weekly usage pools whose exact sizes have not been publicly detailed.
The economics of that model are what Musk’s November 1 post put in the spotlight. Agentic systems burn far more compute than ordinary chatbot exchanges. Each task can trigger repeated model calls, tool use, web actions, and sustained background work.
When growth is as rapid as Musk celebrated, the absolute compute bill scales quickly even if average revenue per user stays fixed under flat monthly subscriptions. Industry observers noted the opportunity cost as well: the same GPUs can be rented to other AI labs at higher rates.
A simple back-of-the-envelope comparison circulating after the post illustrated the gap: if every reported daily user paid the top tier, annualized subscription revenue would still be modest relative to the scale of compute infrastructure SpaceX is building and leasing to companies like Anthropic.
Some users also reported possible dashboard anomalies around the same period, though Musk’s framing treated the underlying cost-revenue imbalance as the core issue rather than a pure metering glitch.
The juxtaposition is the core of this exchange. Within roughly two weeks of publicly framing Grok Bot as an unprecedented success with strong unit economics and no free tier, Musk acknowledged that serving the same product had become unsustainable relative to the revenue it generates.
For the broader industry, the episode underscores a structural challenge of the agent era: demand is real and growing faster than many expected, yet the cost of fulfilling that demand through always-on, multi-step agents can outrun subscription pricing before companies can adjust limits, introduce metered billing, or raise prices.
Musk’s reply did not promise an immediate reset or higher allowances; it simply stated the constraint. In doing so, it supplied a rare, explicit public data point on the unit economics of a high-profile AI agent just as adoption numbers were still being celebrated as the fastest in Musk’s experience.
The tension between rapid, paid growth and the compute required to deliver it is now on the record.
Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.

Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.
Elon Musk
SpaceX President to gift Trump Accounts her SpaceX stock
Gwynne Shotwell’s 2 million SpaceX shares are headed to children’s Trump Accounts starting this December.
SpaceX President Gwynne Shotwell said Friday that more than 2 million SpaceX shares belonging to her and her husband, Robert, will be distributed to children’s Trump Accounts in December, turning a pledge she made over the summer into an actual transfer. “Robert and I are thrilled that our gift of over 2 million shares of SpaceX stock will be distributed to children’s Trump accounts in December!” Shotwell wrote on X, adding that the shares are “transferring to escrow as we speak.”
The first round goes to children aged 11 to 17 who live in ZIP codes where the median family income is $57,000 or less, along with kids in ZIP codes with too few residents for the Census to report that figure. Shotwell said those families should receive a notice by Monday, Reuters reported.
A second gift is expected to be finalized in the next few weeks. That round will cover eligible children in military families serving overseas, children in foster care, and more kids in Texas counties near the Shotwells’ home where median family income is $90,000 or less. Elon Musk replied to the announcement with “Cool” and a heart emoji.
Shotwell first announced the donation on July 6, less than a month after SpaceX priced its record IPO at $135 per share on the Nasdaq. IPO filings showed Shotwell owned about 12.6 million SpaceX shares, Quartz reported at the time, which makes the gift roughly one sixth of her stake. At the roughly $146 per share used to value Musk’s own pledge earlier this month, 2 million shares are worth about $290 million.
How the stock would actually reach the accounts had been an open question since July. Treasury guidance acknowledged that stock donations could flow into Trump Accounts, but it did not explain the mechanics for a program whose contributions default into an S&P 500 index fund. Shotwell thanked the Treasury, the IRS, the Dell Foundation, Greater Horizons, Invest America and the law firms Morgan Lewis and Gibson Dunn for “working over the past few months to make this happen.”
The transfer also works as a dry run for a far larger gift. On October 19, Musk said he would give one of his SpaceX shares to every kid in America next year and called it “the first of many.” With roughly 72 million children in the country, that pledge is worth about $10.5 billion. President Donald Trump thanked Musk the same day and said the shares would go through Trump Accounts, though neither SpaceX nor the Treasury has published how or when that distribution will happen.
Shotwell’s recipients also fill a gap in the program itself. Trump Accounts launched on July 4, and the $1,000 Treasury deposit only goes to babies born between 2025 and 2028. Teenagers aged 11 to 17 receive no government seed money, so for many of the families getting a notice on Monday, SpaceX stock will be the first asset in the account. The accounts convert into retirement accounts when the child turns 18.

Grok Bot users hit with weekly limits early, Elon Musk explains what happened

Tesla owners who tap Emergency Drive Away for fun are in for a surprise


