News
SpaceX wins new Falcon Heavy launch contract as rocket’s prospects stabilize

SpaceX has won a new Falcon Heavy launch contract from Swedish telecommunications company Ovzon, which hopes to procure a large geostationary communications satellite in time for launch in the fourth quarter of 2020.
Excluding two pending contracts, a consequence of the many years of delays suffered since SpaceX first began marketing the rocket, Ovzon’s commitment is now the fourth commercial contract secured by Falcon Heavy in 2019 and 2020, solidifying enough demand to sustain – on average – biannual launches over the next two or so years.
Ovzon signs agreement with SpaceX for first satellite launch – read the full release here: https://t.co/M9YWRCyp5L
In an important step towards growing our satellite service offering, Ovzon has entered into an agreement with SpaceX for launch of Ovzon’s first GEO satellite. pic.twitter.com/HfMfl9jnNV— Ovzon AB (@OvzonAB) October 16, 2018
Speaking at IAC 2018, SpaceX VP of Reliability Hans Koenigsmann was by no means wrong when he described the latent demand seen for Falcon Heavy launches, stating that “there aren’t too many customers for it”. Indeed, just three firm launch contracts over the next two years did not bode particularly well for Falcon Heavy as a competitive complement to SpaceX’s commercial launch business – without regular demand and assuming a competitive and fixed-price market, the cost of maintaining the infrastructure needed to build and fly a distinct launch vehicle will inevitably end up cannibalizing profitability or even the ability to break even.
For vehicles like ULA’s Delta IV Heavy, NASA’s SLS, or the late Space Shuttle, the unique capabilities offered by certain low-volume rockets or even just the risk of faltering can lead to situations where anchor customers will swallow huge cost premiums for the sake of simply preserving those capabilities. In non-competitive markets, it does not take much for nearly any capability to become essentially priceless. SpaceX, however, paid for Falcon Heavy’s development without seeking – and even actively turning down – most government development funding or guaranteed launch contracts.
-
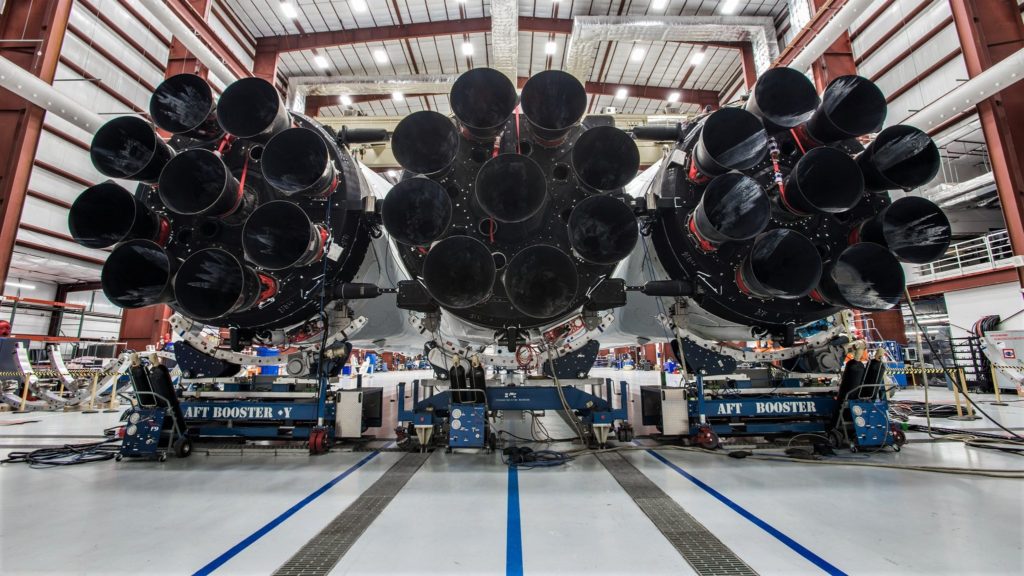
- Falcon Heavy ahead of its inaugural launch. (SpaceX)
-
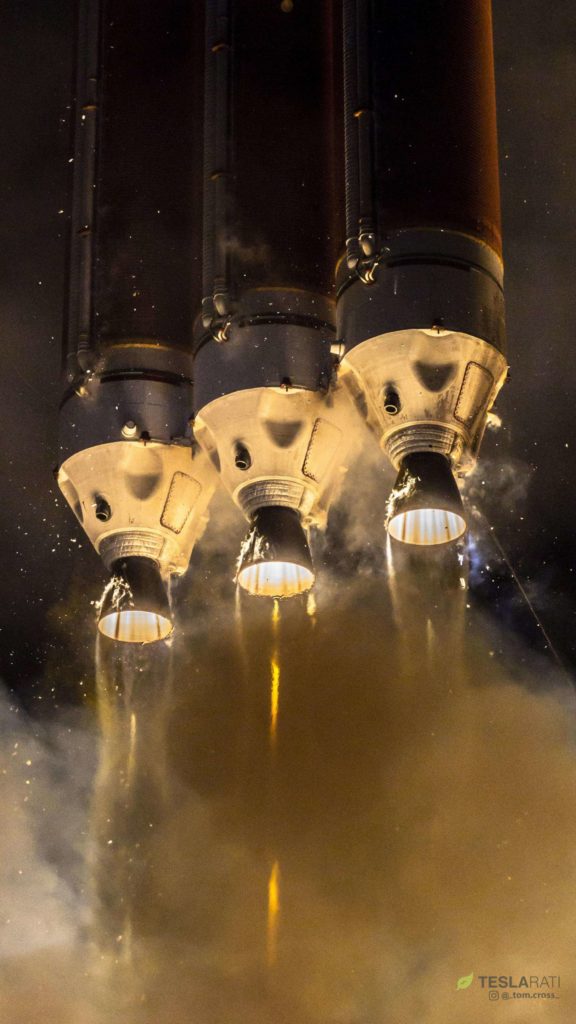
- The extraordinary might of Delta IV Heavy’s hydrolox-burning RS-68A engines, producing a combined 2.1 million pounds of thrust at liftoff. (Tom Cross)
A tough life for big birds
As such, Falcon Heavy’s utility and existence are in a far more precarious position than most rockets, owing to the fact that SpaceX would likely not hesitate to kill the vehicle if commercial demand rapidly withered to nothing, far from impossible with just three total launches contracted over a period of fewer than two years. Prior to the USAF announcing a new Falcon Heavy launch contract in June 2018, that number was just two secured launches. Combined with the USAF purchase, Ozvon’s new contract suggests that prospects for the super-heavy-lift rocket may be at least warm enough to sustain its useful existence.
SpaceX's Falcon Heavy manifest:
– Arabsat 6A (NET early 2019)
– STP-2 (NET 2019)
– AFSPC-52 (NET September 2020)
– Ovzon (NET Q4 2020)Pending confirmed payloads:
– Viasat
– Inmarsat— Michael Baylor (@MichaelBaylor_) October 16, 2018
There is also a decent chance that, once Falcon Heavy has proven itself with one or two real satellite launches, commercial launch customers will warm to its impressive capabilities. Most notably, Ozvon may have sided with Falcon Heavy solely because the powerful rocket can place its Ozvon-3 communications satellite directly into geostationary orbit (GEO), compared to the far more common process of launching the satellite roughly halfway there and letting it finish the journey on its own, known as geostationary transfer orbit (GTO) insertion.
There is undoubtedly significant commercial upside for geostationary communications satellites to arrive at their operational orbits as quickly as possible, rather than spending weeks or even months slowly making their way uphill from GTO. The cost of dedicated launches of Delta IV Heavy or Ariane 5 have far outweighed the benefits of earlier operability for as long as the rockets have been flying, though, and smaller and more affordable vehicles like Falcon 9, Atlas 5, or dual-manifested Ariane 5s simply aren’t powerful enough to launch traditionally-sized commsats directly to GEO.
-
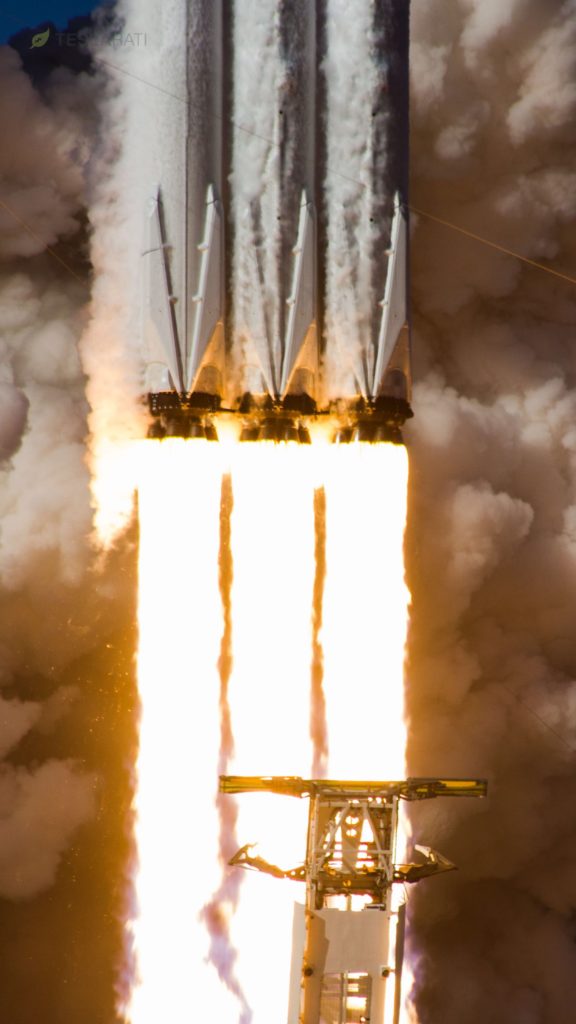
- Falcon Heavy clears the top of the strongback in a spectacular fashion. Two of the rocket’s three manifested missions are now for the USAF. (Tom Cross)
-
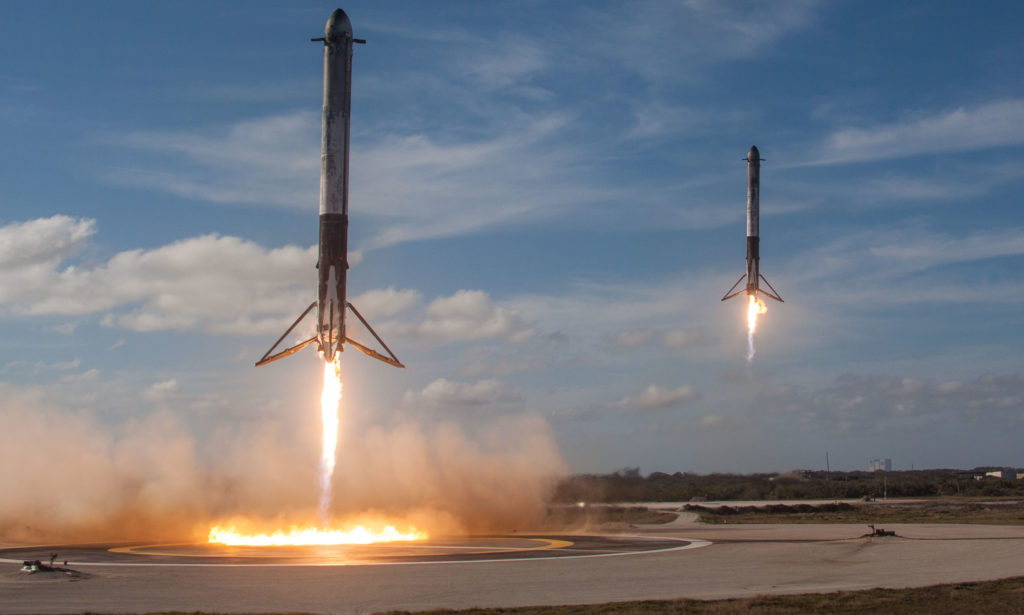
- Falcon Heavy’s stunning dual side booster recovery. (SpaceX)
-
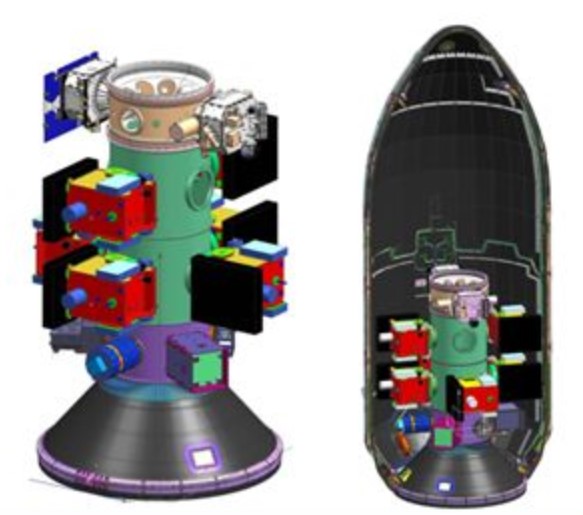
- SpaceX’s second Falcon Heavy launch will either be the USAF’s STP-2, a collection of smaller satellites, or Arabsat 6A, a large communications satellite. (USAF)
-
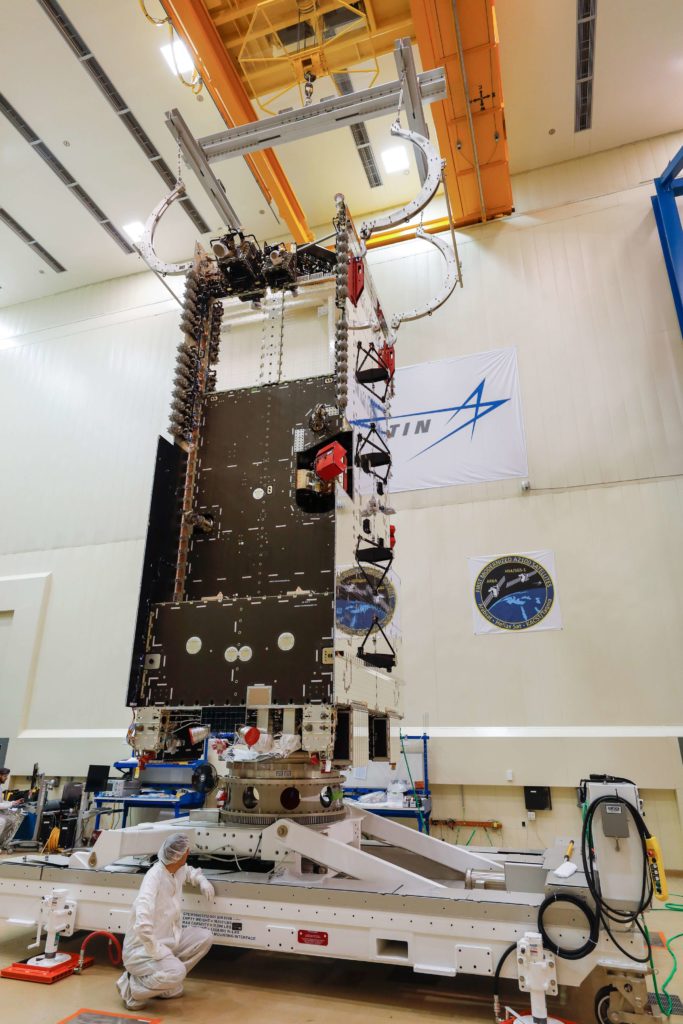
- The communications satellite Arabsat-6A. (Lockheed Martin)
In that regard, Falcon Heavy launches could become a commercial game changer and a distinct competitive advantage for companies that select it. Now with at least four launch contracts secured over the next ~24 months, Falcon Heavy will have a much better chance at demonstrating its true capabilities, potentially enabling military-premium launch services (~$250m+) at commercial-premium prices (~$90-150m). If it performs as intended in its next few launches, expected sometime in H1 2019, Falcon Heavy will be a strong contender for at least five additional USAF contracts as well as certain NASA missions scheduled to launch in the 2020s.
Experience with Falcon Heavy may only be tangentially beneficial at best to SpaceX’s greater BFR ambitions, but commercially, competitively, and reliably operating a rocket as large as FH for customers like the USAF and NASA would go a long, long way towards solidifying SpaceX’s perception as a ULA-equivalent launch provider for roughly half the cost.
For prompt updates, on-the-ground perspectives, and unique glimpses of SpaceX’s rocket recovery fleet check out our brand new LaunchPad and LandingZone newsletters!



Update: 10/22 10:51a – Para 1 consumers changed to “customers” for accuracy.
Tesla Cybercab units finally got a definitive date for when they will be able to be purchased by customers, ending speculation regarding whether the fully autonomous vehicle would be available in the near term.
During Tesla’s third-quarter 2026 earnings call on October 21, Vice President of Engineering Lars Moravy said the company is aiming to begin delivering its purpose-built Cybercab robotaxi to customers before year-end.
🚨 In short, Cybercabs are slated to go to customers by end of the year. All units are going into Robotaxi fleet currently, per @larsmoravy
Cybercab will be “transport-as-a-service,” but vast majority of Cybercab will be “Tesla-owned,” @elonmusk says https://t.co/R8Qu8QWdmp
— TESLARATI (@Teslarati) October 21, 2026
“We’re trying to get Cybercabs to customers by the end of this year, 2026,” Moravy said. He added that production is underway on the line at Gigafactory Texas, but “all of those are currently going to our own internal Robotaxi fleet.”
Moravy explained that as operations scale, Tesla will “mainly deliver fully designed autonomous vehicles to our customers,” with the Cybercab as the first such vehicle. Initial customer deliveries will start small while the company gains experience with delivery logistics, ownership models, fleet management, and operating autonomous vehicles outside its direct control.
CEO Elon Musk reinforced the limited nature of private sales, describing the Cybercab primarily as a “transport-as-a-service” offering rather than a personal ownership vehicle like the Model 3, Model Y, or upcoming Roadster. “The vast majority of the Cybercab stuff will be Tesla-owned and transport-as-a-service,” Musk said.
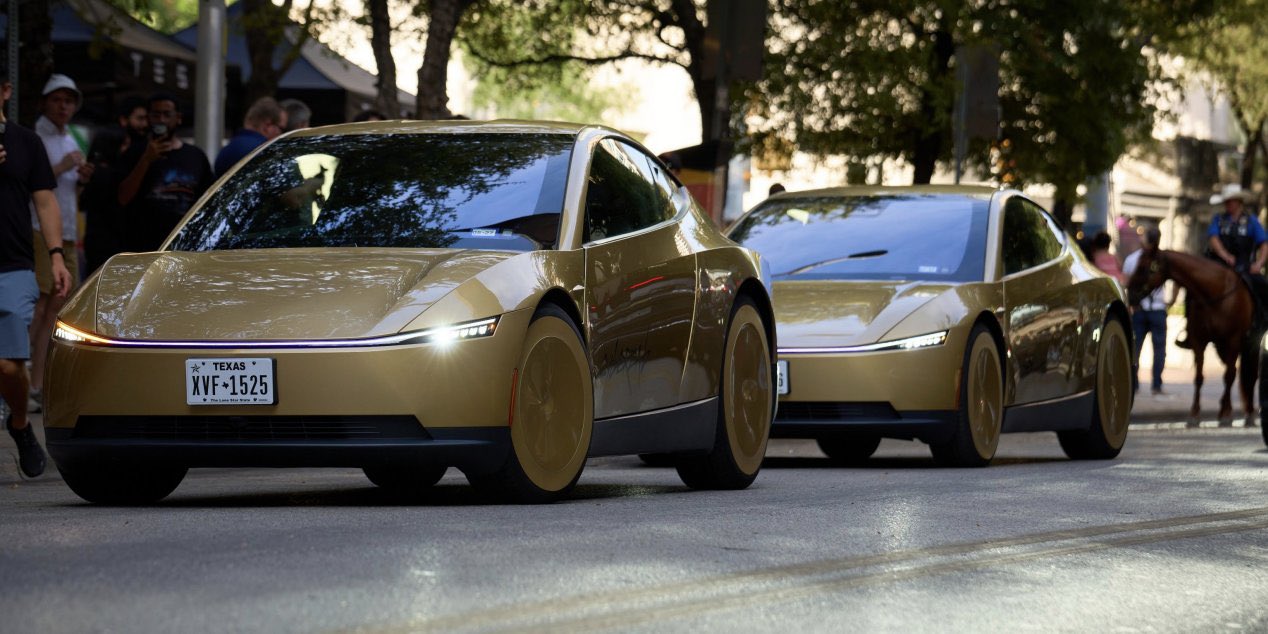
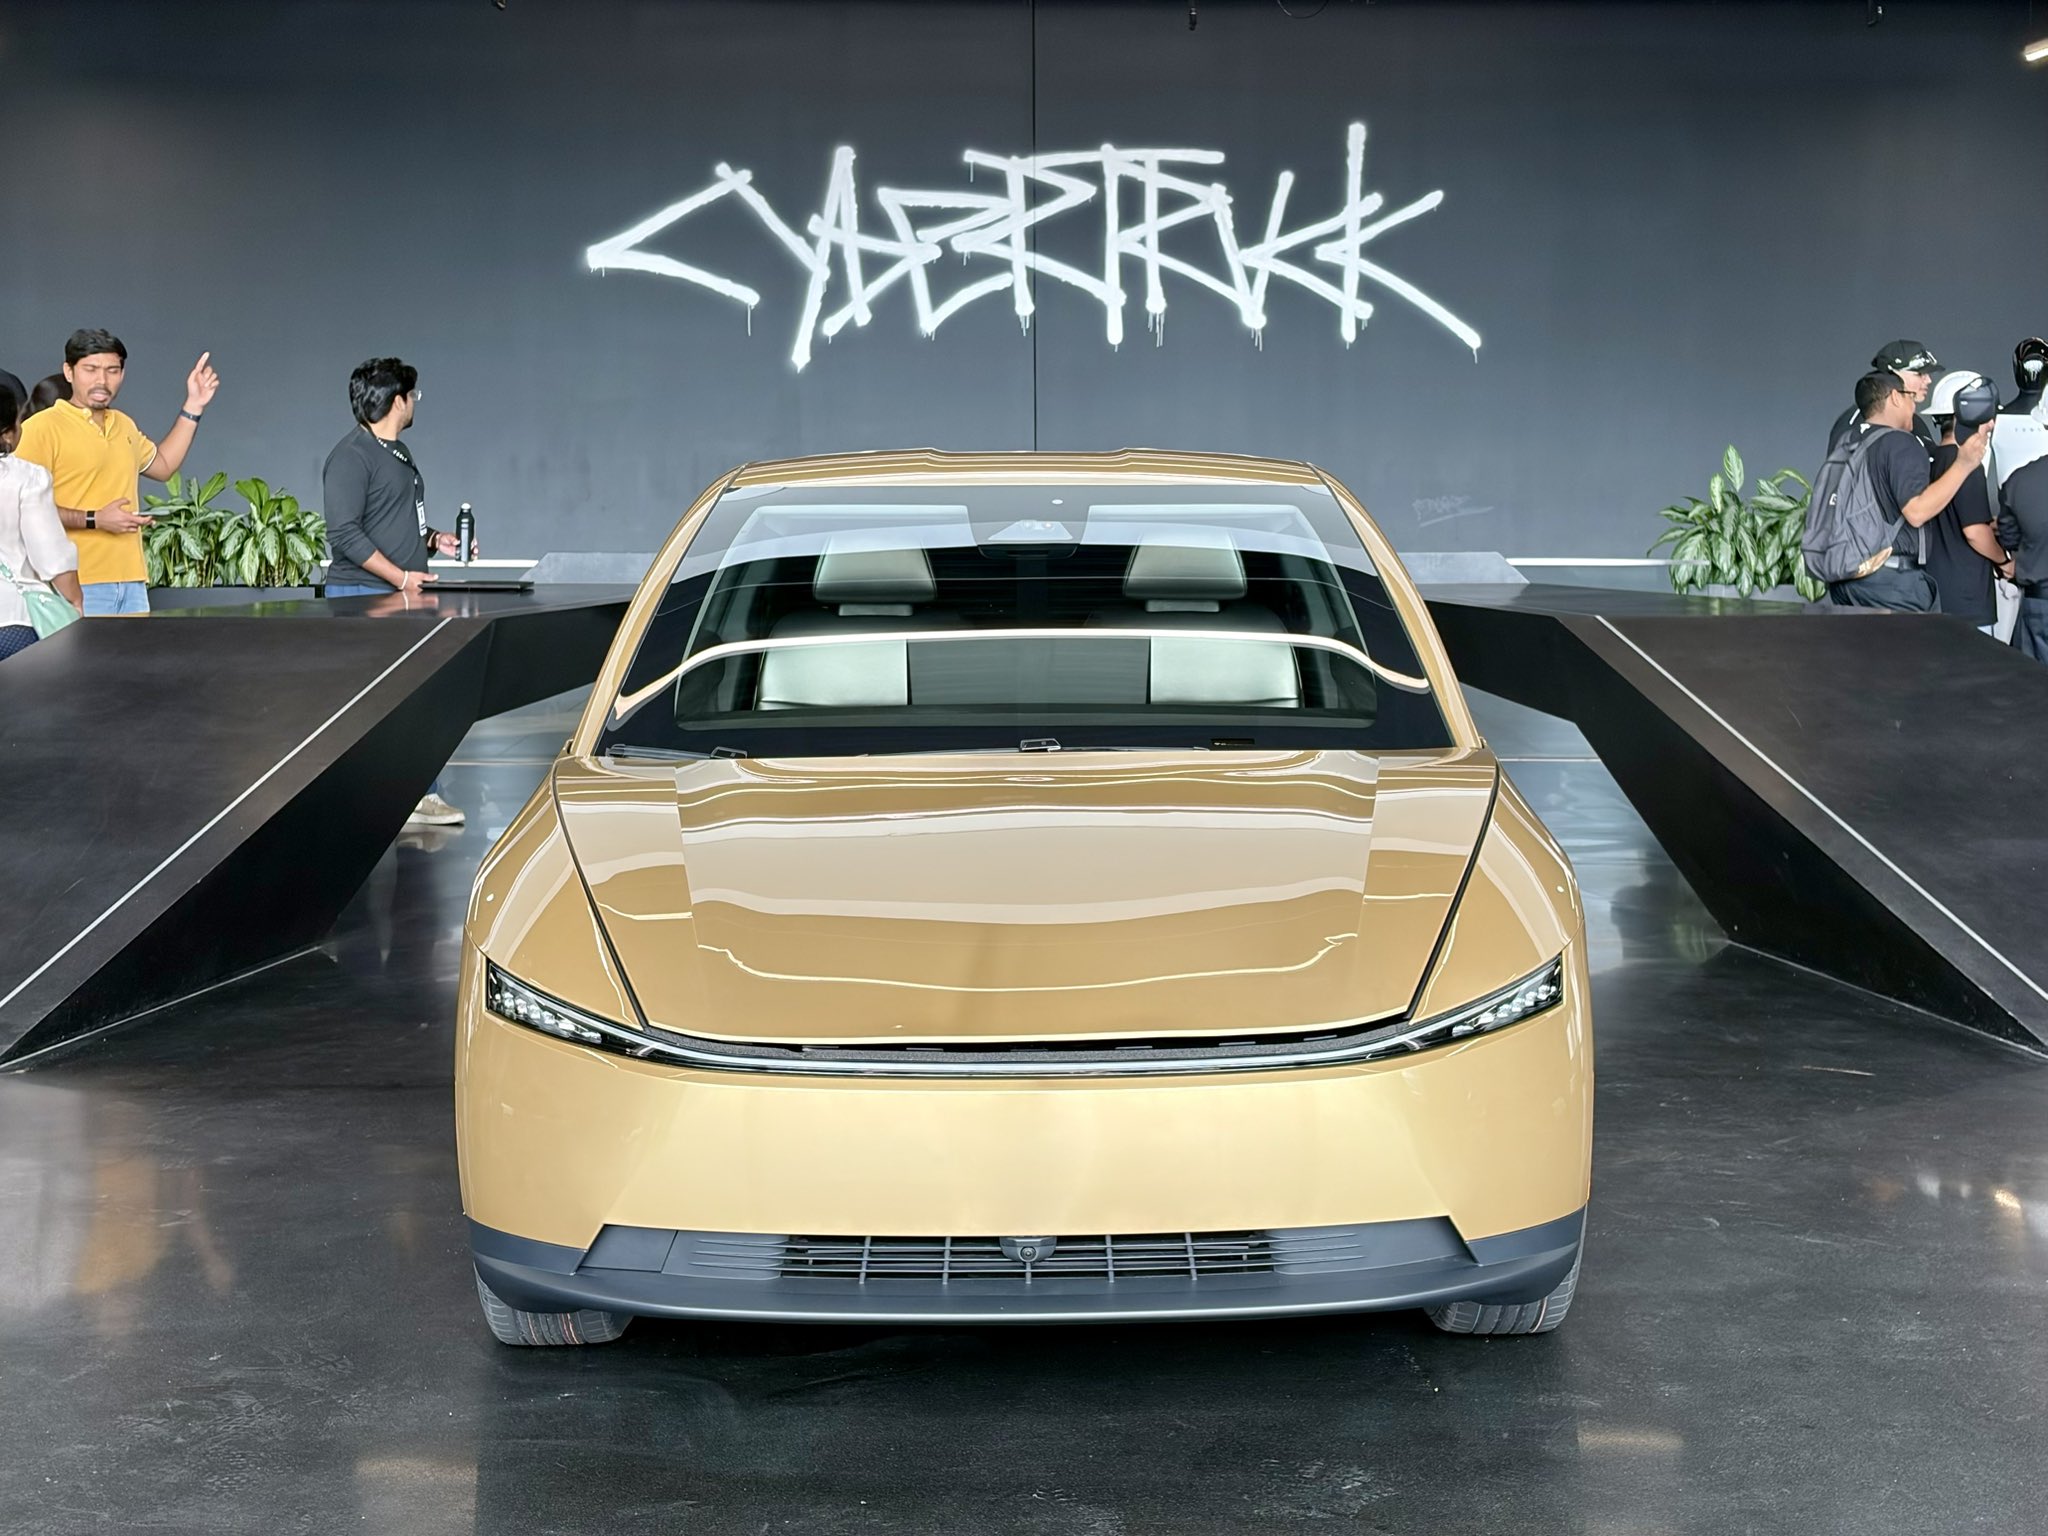
The Cybercab is a two-seater vehicle developed by Tesla without a steering wheel or pedals. It relies completely on Tesla’s Full Self-Driving suite and has been in production since February. Early units have been put in Tesla’s Robotaxi service as of early September, when the company launched rides to the public. Tesla previously indicated it would aim to sell Cybercabs for about $30,000.
Unsupervised Full Self-Driving is expected to ship to consumer cars during Q2 2027, Ashok Elluswamy, Tesla’s Head of AI, indicated during the call. Early buyers or fleet operators may receive vehicles whose autonomous operation remains geographically restricted due to lagging regulatory agencies. There are some hurdles that remain ahead of Cybercab deliveries.
Tesla (NASDAQ: TSLA) reported its earnings for the third quarter of 2026, marking a reasonable performance on the various financial metrics. Tesla still plans to hold a call that will field investor questions at 5:30 p.m. ET, 4:30 p.m. CT.
Here’s where Earnings came in:
- Total Revenues: $28.046 reported vs. $28.34B expected
- Non-GAAP EPS: $0.48 reported vs. $0.45 expected
- Operating Margin: 2.6 % reported vs. 2.5% expected
- Operating Income: $718M reported vs. $721M expected
- Free Cash Flow: $1.531B reported vs. ~-$4.51B expected
Tesla $TSLA Earnings Results:
Revenues: $28.046B
Non-GAAP EPS: $0.48
Operating Margin: 2.6%
Operating Income: $718M
FCF: $1.531B— TESLARATI (@Teslarati) October 21, 2026
Major Takeaways
Full Self-Driving (Supervised)
“FSD (Supervised)⁴ attach rate continued to grow, reaching over 75% of new vehicle deliveries in North America – our most mature market – a nearly twenty percentage point sequential increase. We believe that FSD is driving demand in markets where it is available, and we continue to work with regulators to get it approved in other markets.”
Tesla Semi
“We began volume production of Tesla Semi, our Class 8 heavy-duty truck. The top variant can go 500 miles at full 82,000 lbs gross combination weight while achieving an efficiency of 1.7 kWh/mile. That efficiency allows the Tesla Semi to use a third of the energy used by a comparable diesel truck to haul the same payload. In a transportation market where energy is one of the largest components of total cost per mile, this will provide a meaningful advantage to Tesla Semi operators.”
SI Compute
“We plan to reach 400 MW of SI training compute by the end of the year, supporting the development of both vehicle and humanoid robot autonomy software. Additionally, we continued construction for the Austin Fab, where we plan to start commissioning equipment in 2027.”
Robotaxi
“We began deployment of Cybercab into our Robotaxi fleet in Austin. We reached nearly two million cumulative unsupervised miles for our Robotaxi service as of the end of the quarter. Operating hours in Austin are now 6am to midnight, and we expect to reduce wait times via increased fleet supply and improvement of Robotaxi orchestration algorithms. Grok is available in Cybercab with access to Grok Bot and Connectors, which allows users to manage their inbox, calendars, files, chats and tasks – all hands free via voice command – making Cybercab a mode of transport, a productivity space and, with our entertainment options, a second living room.”
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.

Tesla Cybercab gets a for sale date at last

Tesla Q3 2026 Earnings results: in-line revenues, slight beat on EPS


