News
SpaceX’s next-gen Falcon Heavy closer to reality as side booster leaves factory

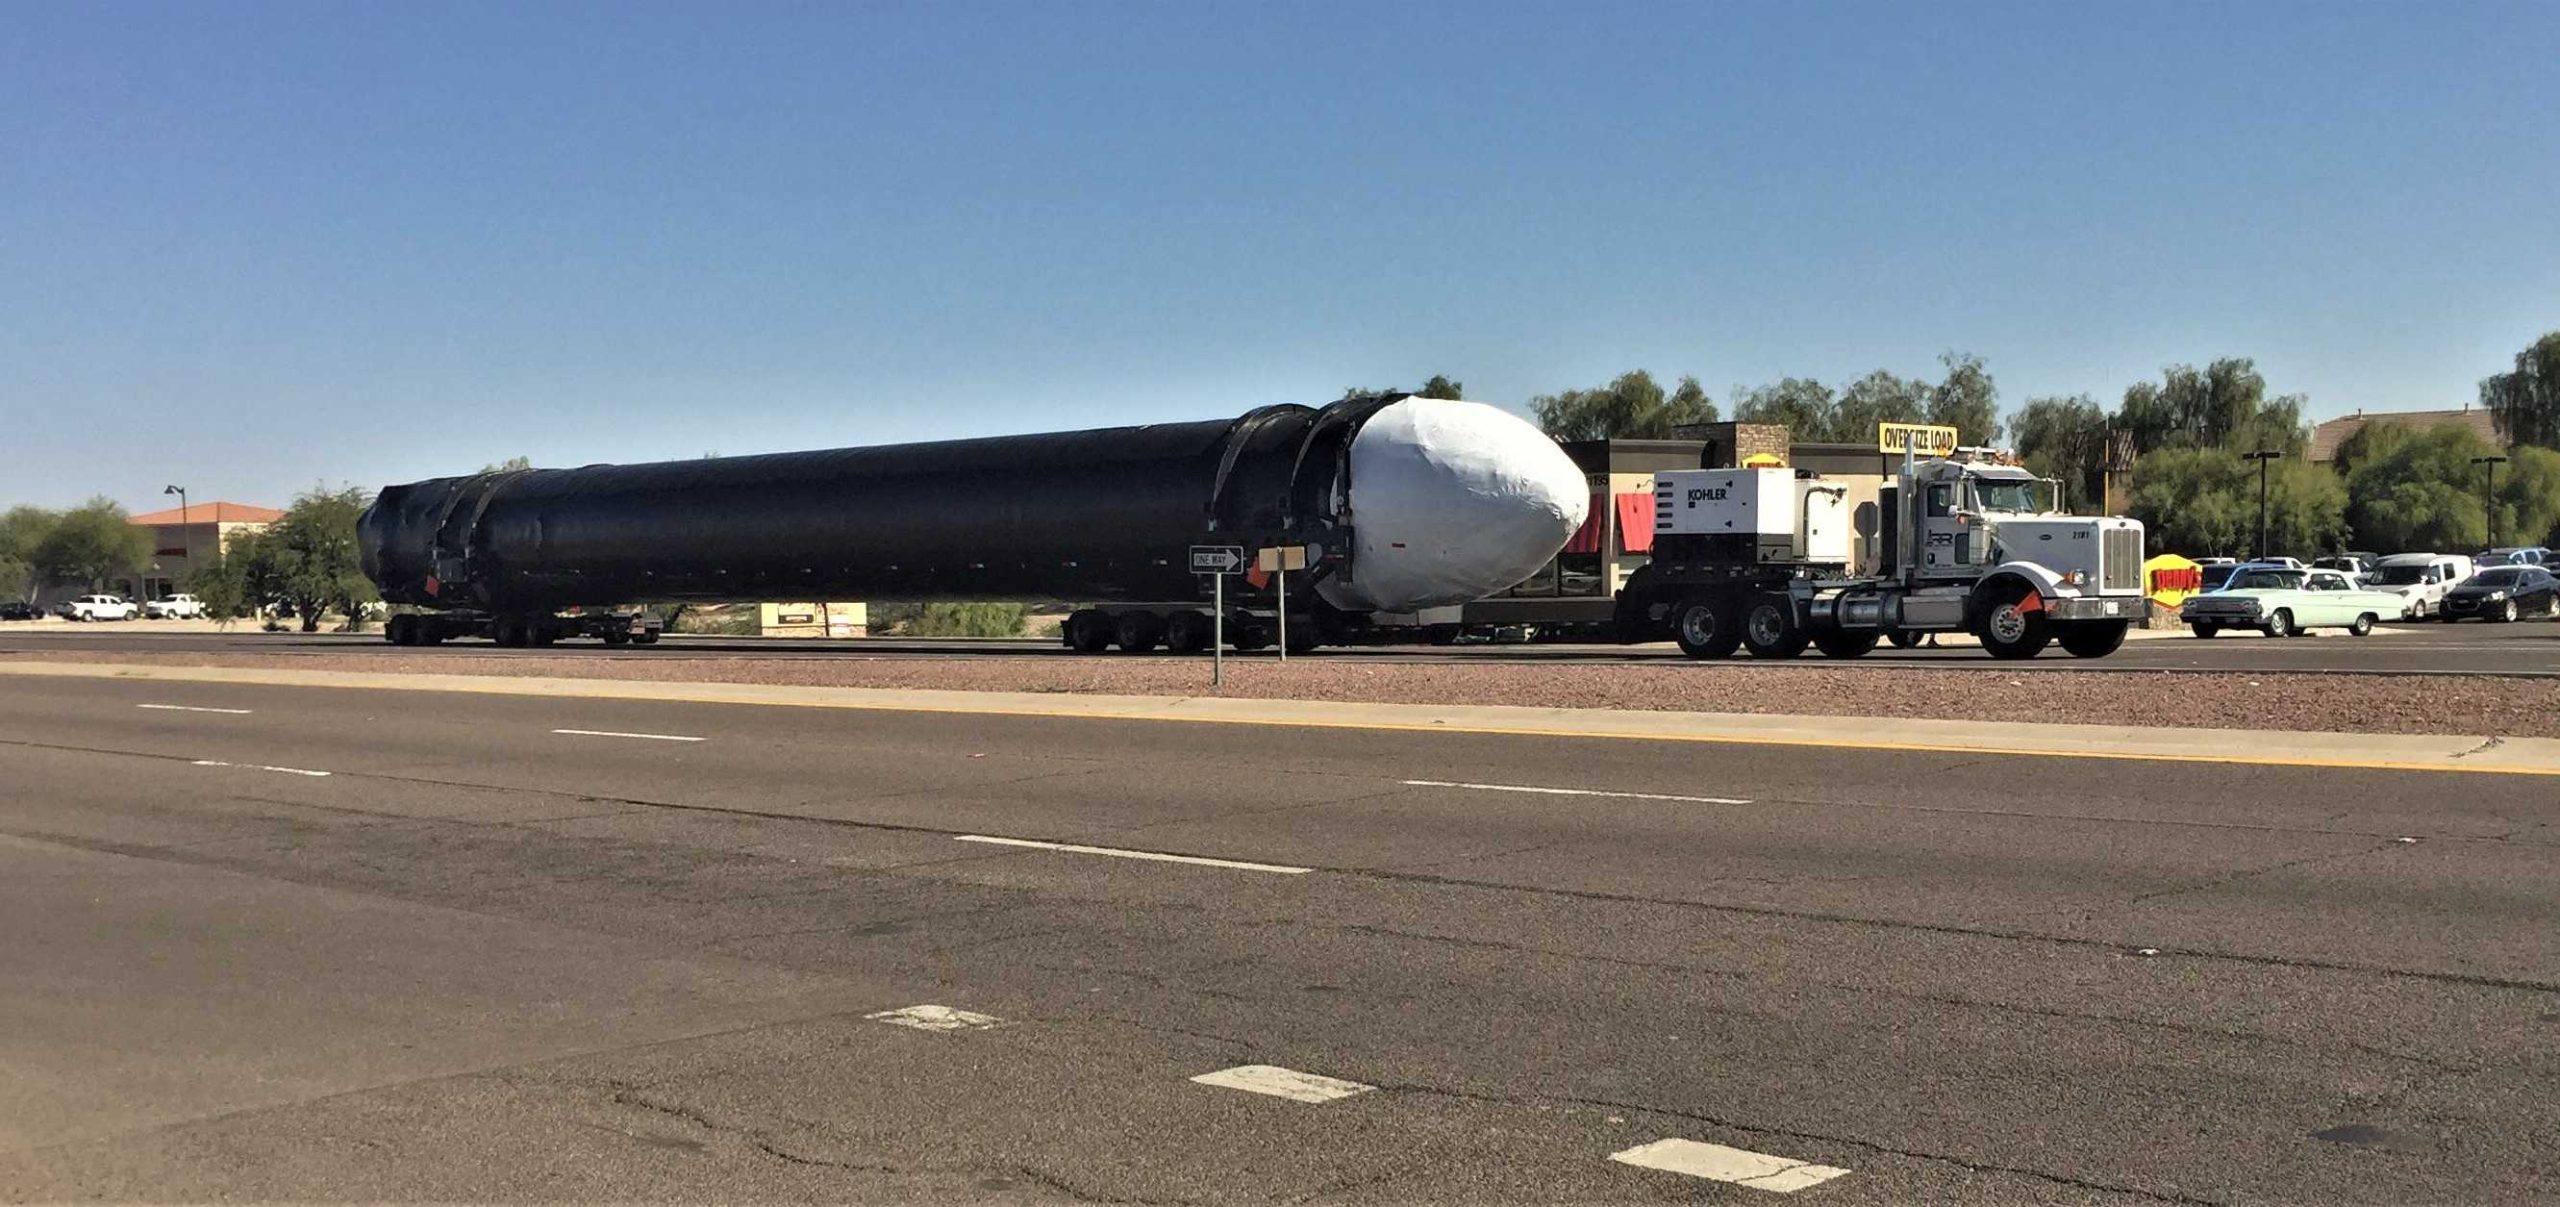
A duo of rocket spottings on November 9th and 10th confirm that SpaceX’s next Falcon Heavy rocket – an amalgamation of three Falcon 9 boosters, an upper stage, and extensive modifications – is already in the late stages of manufacturing and is nearing the beginning of integrated structural and static fire testing.
As of now, this Falcon Heavy side booster could end up supporting either or both of two near-term launch contracts in place for the rocket, communications satellite Arabsat 6A or the US Air Force’s second Space Test Program (STP-2) launch
SpaceX's second Falcon Heavy is slowly but surely coming together 😀 https://t.co/AYJsQ8Mld5
— Eric Ralph (@13ericralph31) November 13, 2018
The question of the hour – at least for Falcon Heavy – is which of those two available payloads will be atop the rocket on its first truly commercial launch. While suboptimal, a few general characteristics of each payload, SpaceX’s history of commercial launches, and Falcon Heavy itself can offer a hint or two.
Triple the rocket, triple the trouble
Thanks in large part to the fact that the first integrated Falcon Heavy was composed of two relatively old Falcon 9 booster variants and a center core that was quite literally a one-off rocket, the process of reenginering and building another Falcon Heavy rocket off of the family’s newest Block 5 variant has likely been far harder than simply building another Falcon Heavy. Although all three original Falcon Heavy boosters (B1023, B1025, and B1033) were in the same league as Block 5, their Block 2 and Block 3 hardware was designed for approximately 10% less thrust and are almost entirely different vehicles from the perspective of structures and avionics.
Perhaps even more importantly, it’s unknown whether Falcon Heavy Block 1 (for lack of a better descriptor) was designed with serious reusability in mind, at least in the same sense as Falcon 9 Block 5 was. For instance, a major portion of the rocket’s extreme complexity and difficulties lies in the basic need to transmit three times as much thrust through the center core. To do that and do it without rocket-powered separation mechanisms, SpaceX had to develop structural attachments and connections capable of surviving unbelievable mechanical and thermal stresses for minutes on end.
-
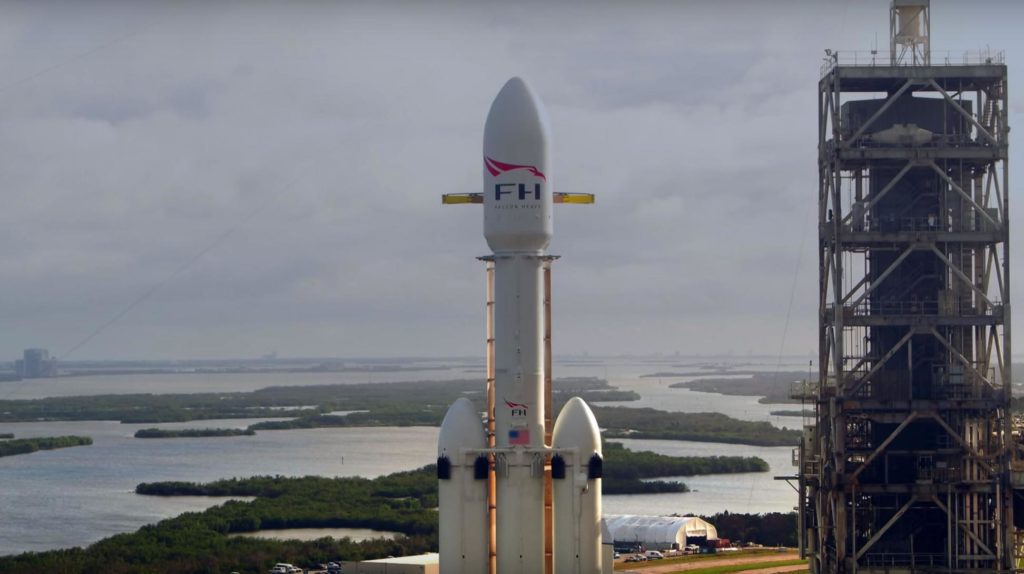
- The first Falcon Heavy was a Frankenstein’s monster of sorts. (SpaceX)
-
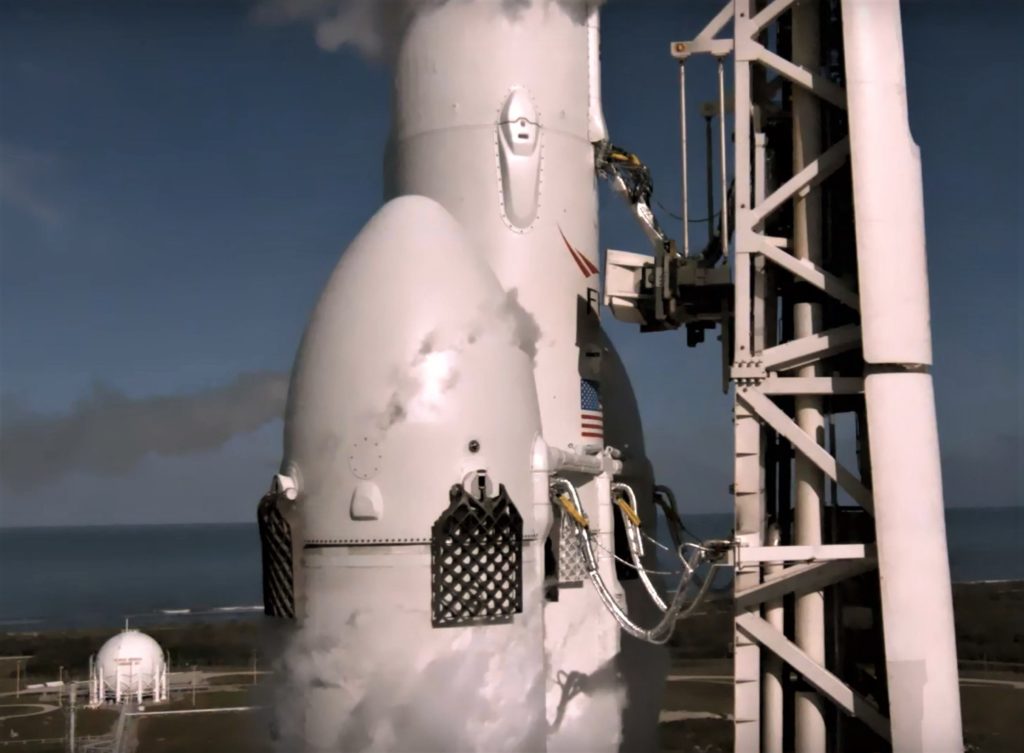
- Falcon Heavy is seen here lifting off during its spectacular launch debut. (SpaceX)
-
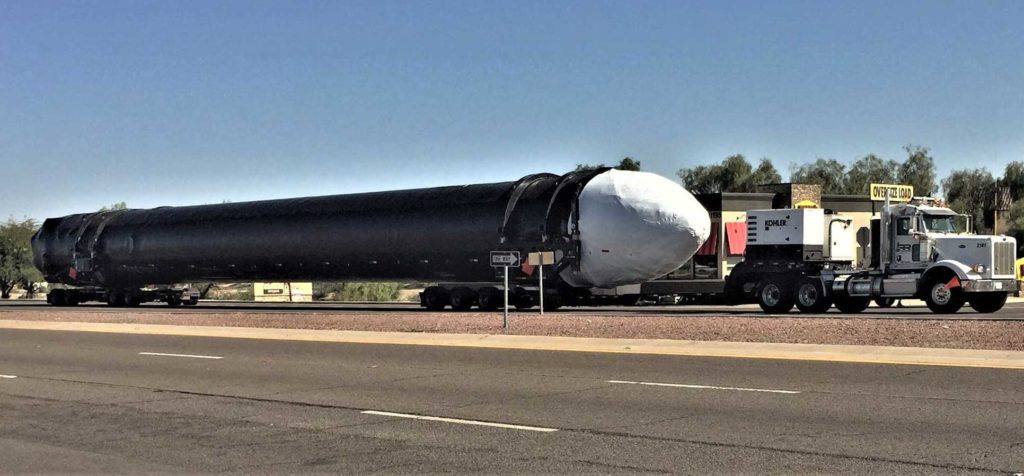
- A Falcon Heavy side booster was spotted eastbound in Arizona on November 10th. (Reddit – beast-sam)
Clearly, this was an unfathomably difficult problem to solve in such a manner that Falcon Heavy would work at all the first time. Factor in the strategic need for those same components to survive repeated cycles of those stresses with minimal refurbishment in between and the problem at hand likely becomes a magnitude more difficult, at least. In large part, this helps to explain why there will end up being a minimum of 11-12 months between Falcon Heavy’s first and second launches.
Arabsat or STP?
Over the course of SpaceX’s last 2-3 years of commercial launch activity, the company and its customers have demonstrated time and time again a reliable pattern: commercial customers (in the sense of private entities) are far more willing to take risks with new technologies than SpaceX’s government customers. NASA’s Commercial Resupply Services is the exception for the latter group but also has no Falcon Heavy launch contracts. For Falcon Heavy, there are thus main three options at hand.
- Arabsat 6A launches first with 1-2 flight-proven boosters; the Air Force’s STP-2 mission flies on an all-new Falcon Heavy 4-6 months later.
- SpaceX builds entirely new Falcon Heavy rockets for both customers, requiring four new side boosters and two new center cores.
- STP-2 launches first on an all-new Falcon Heavy; Arabsat 6A launches second on the first flight-proven Falcon Heavy after 6+ months of additional delays.
-
- The USAF’s STP-2, a combination of a few dozen different satellites. (USAF)
-
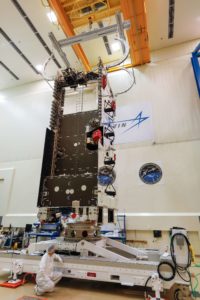
- The communications satellite Arabsat-6A. (Lockheed Martin)
-
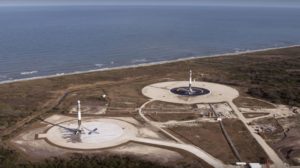
- LZ-1 and LZ-2, circa February 2018. (SpaceX)
-
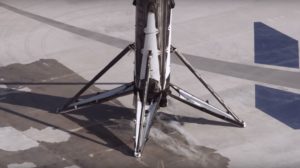
- A closeup of one of Falcon Heavy’s side boosters after landing. (SpaceX)
Arabsat is far more likely to accept – for a significant discount – a ride aboard the first flight-proven Falcon Heavy, especially if it means preventing more major launch delays. If the Falcon Heavy side booster spotted eastbound last week is a refurbished Block 5 booster rather than a new rocket, than option 1 is the easy choice for most probable outcome. The real pack leader for Falcon Heavy Flight 2, however, will be the completion of a new Block 5 center core and its shipment to Texas for structural and static fire testing.
Time will tell. For now, a completed Falcon Heavy side booster is the best sign yet that SpaceX may manage the rocket’s second launch in the first quarter of 2019, whichever launch that may be.


Elon Musk
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Tesla and SpaceX formed special committees to weigh a merger, and Elon Musk supports it.

Elon Musk confirmed Tuesday that Tesla and SpaceX have each formed special committees of independent directors to study a possible merger, the first formal step toward combining the two companies after months of speculation.
Musk made the disclosure during SpaceX’s third quarter earnings call. “Both SpaceX and Tesla have formed special committees to discuss this idea at the request of shareholders,” he said. “Because I’m a conflicted party, I can’t actually be in the discussions of the special committees.” He described the setup as “an odd kabuki dance where two groups of people are talking and I can’t be in the conversation.”
Musk did not hide where he stands. “Do I think it would be a good idea? Yes,” he said, pointing to shared work on super intelligence software, chip design, the Terafab facility in Austin, robotics, mass to orbit and connectivity. “I do think there’s a lot of merit to combining the companies as we are pretty much in the super intelligence singularity.”
He also tried to cool expectations. The committees have not agreed on terms for any transaction, and Musk said assuming a merger is a certainty “would be overstating it.” Any deal would go to shareholders, and on the Tesla side it would need approval from 50 percent of all outstanding shares, not just the shares that are voted. Musk called that “quite a high hurdle.”
That bar has tripped Tesla up before. The company’s 2025 attempt to declassify its board won support from only 39.4 percent of outstanding shares and failed. Musk’s own voting stake sits near 20 percent after he exercised his 2018 options in June, so a deal would need broad backing from institutions and a retail base that often leaves votes uncast.
Timing is another open question. Tesla filed its proxy statement Monday for its December 3 annual meeting, and the ballot has only three items: director elections for Musk, Robyn Denholm and JB Straubel, a say on pay vote and auditor ratification. Barclays analyst Dan Levy had argued that an announcement would need to land by late October or early November to make the annual meeting, as Teslarati noted in its SpaceX earnings preview. With no terms agreed, any vote would likely require its own special meeting.
Elon Musk gives his most telling Tesla-SpaceX merger conversation yet
Musk has been edging toward this for weeks. At the All-In Summit in September, he asked “who can imagine what action one might take when there’s so much close collaboration,” Teslarati reported. Last week’s Roadster unveil, built around SpaceX derived cold gas thrusters, pushed the talk further. The two companies already share the Terafab chip project, and Tesla holds a small SpaceX stake that came from its earlier investment in xAI.
SpaceX brought strong numbers to the conversation. It reported Q3 revenue of $14.58 billion, up 161 percent year over year, with its Super Intelligence segment now its largest at $7.56 billion. A higher SpaceX valuation would shape any exchange ratio Tesla holders are offered.
Tesla reports its own third quarter results after the close on Wednesday, October 21. Investors had already ranked merger timing among the top retail questions for SpaceX’s call, and the committees will almost certainly come up again on Tesla’s.

SpaceX reported its third-quarter 2026 financial results on October 20, posting the company’s first solidly profitable quarter since going public earlier in the year under the ticker $SPCX.
Revenue reached $14.58 billion, up 161 percent year-over-year from $5.6 billion, and well ahead of consensus estimates in the $12.7 to $12.9 billion range. The results highlight a rapid shift in SpaceX’s center of gravity toward artificial intelligence/super intelligence, while Starlink and traditional space operations continue to show robust progress.
Here are the key financial results for the quarter:
- Revenue of $14.58 billion (+161% YoY)
- Adjusted EBITDA of $8.8 billion (+306% YoY)
- GAAP net income of $4.4 billion (versus a $1.1 billion net loss in the prior-year quarter)
- Adjusted EPS of approximately $0.35 (versus roughly $0.13–0.16 expected)
- Income from operations of $2.8 billion
The AI/SI segment generated $7.56 billion in revenue, an 830 percent year-over-year increase, making it the company’s largest segment for the first time. Growth was primarily driven by the activation of major cloud services agreements, the integration of Cursor (acquired earlier in 2026), and rising usage of Grok models and the newly introduced Grok Bot personal agent.
🚨 SpaceX just reported earnings! Here are some highlights:
Financial:
Revenue $14.58B (+161% YoY) vs. consensus ~$12.7–12.9B
Adjusted EBITDA $8.8B (+306% YoY)
GAAP net income $4.4B (vs. prior-year loss; first solidly profitable quarter post-IPO)
Adjusted EPS ~$0.35 vs. ~$0.13–0.16 expectedSegments:
Super Intelligence (SI, formerly AI): $7.56B (+830% YoY) — now the largest segment, driven by cloud contracts, Cursor, and Grok.
Connectivity (Starlink): $5.25B (+69% YoY).
Space: $1.77B.Other highlights:
Starlink subscribers: 13.6M (+89% YoY).
Nameplate compute: 1.7 GW.
Capex: $19.6B (majority AI infrastructure).
Cash & marketable securities: ~$90B.
First revenue-generating Starship mission (26 V3 Starlink satellites, ~10× Falcon 9 downlink capacity per launch).— TESLARATI (@Teslarati) October 20, 2026
SI adjusted EBITDA reached $5 billion, and nameplate compute capacity stood at 1.7 GW at quarter-end, up from 1.4 GW in June and 0.6 GW a year earlier. Capital expenditures totaled $19.6 billion, with the majority allocated to AI infrastructure, including continued expansion of the Colossus facilities.
The Connectivity segment, which primarily surrounds Starlink, produced $5.25 billion in revenue, a 69 percent year-over-year and 22 percent sequentially. These are pleasant results to see and expected, considering how many airlines have adopted Starlink over the past year.
Starlink consumer subscribers reached 13.6 million, an 89 percent increase from the prior year, and a sequential gain of 1.6 million. Consumer average revenue per user improved to $69. Meanwhile, Enterprise and Government revenue also grew strongly, and Starlink is now installed on more than 3,800 aircraft, making internet more accessible and better performing than previous options.
The Space segment also performed well and contributed $1.77 billion in revenue, up 6 percent year-over-year and 84 percent sequentially. A major milestone was the successful first revenue-generating Starship mission (Flight 14), which deployed 26 V3 Starlink satellites. Those satellites added roughly 10 times the downlink capacity of a typical Falcon 9 Starlink launch.
SpaceX completed 12 customer launches during the quarter, including NASA’s Nancy Grace Roman Space Telescope mission, and continued to grow its backlog of crewed, national security, and commercial flights.
CFO commentary noted that the combination of launch leadership, recurring Starlink revenue, and rapid SI expansion is producing meaningful operating leverage.
The company ended the quarter with roughly $90 billion in cash and marketable securities, providing substantial resources for ongoing investment while targeting an investment-grade balance sheet. Sequential revenue nearly doubled from the $7.81 billion reported in the second quarter, illustrating the pace of the AI-driven acceleration. Things are looking strong for SpaceX.
What’s incredibly striking is the fact that SI has grown to be larger than the rest of the company in such a short amount of time. CEO Elon Musk said on the earnings call that Grok Bot is the “fastest-growing product I’ve ever seen,” so it seems that it could be a true keystone of SpaceXSI over the next few years.
SpaceX (NASDAQ: SPCX) will report its second public earnings call today since its IPO earlier this year, and there are a few things we expect to hear about, as well as Wall Street analysts, who have already outlined their expectations for the call.
Wall Street analysts have a consensus of $12.72 billion in revenue and an earnings per share (EPS) of $0.13. These are broken down into three sectors: Space, Connectivity, and AI/SI, which are perceived in this way:
- Space: $1.41 billion
- Connectivity: $4.84 billion
- AI/SI: $6.47 billion
Other outlets cluster near $12.8 or $12.9 billion in revenue and $0.14 – $0.15 EPS. This implies a roughly 65 percent sequential growth from Q2’s $7.81 billion, driven mostly by AI/SI, with the first post-IPO positive EPS expected.
Here are the three things to watch for on the call:
AI Revenue Ramp and the $100B+ ARR target
AI is truly the swing factor for SpaceX, and analysts expect it to roughly double from Q2’s $2.56 billion and become about half of total revenue. Management previously guided to a $100 billion+ annualized run rate by December, including the Cursor acquisition, which was $60 billion, to close the quarter.
Listen for updates on SpaceX’s compute capacity, especially pertaining to its contracts with Google, Anthropic, and others, revenue per watt, any new deals, and Cursor’s early contribution.
Starlink/Connectivity Metrics and Mobile Expansion
Connectivity remains a main profit engine for SpaceX. Subscriber additions will be something to pay attention to, as Q2 ended at 12 million and previews are looking at 14 million for this quarter. Additionally, ARPU trends, enterprise and government growth, and any commentary on Starlink Mobile will be something to pay attention to, especially following the recent low-band spectrum deal and FCC-related constellation approvals.
Capex Trajectory, Cash Burn/FCF, and Starship/Operational Updates
Q2 capex of roughly $18.4 billion weighed on the stock. Investors will look to scrutinize Q3 spending levels, any guidance on the pace into Q4/2027, free cash flow, backlog, and liquidity. Operational color on Starship (Flight 14 milestones and Flight 15 timing/reusability progress), Falcon cadence, and government/NASA contracts are also in focus.
Of course, there will also be some speculation on the potential Tesla-SpaceX merger, but there was nothing mentioned in the company’s proxy it sent earlier this week.
SpaceX will report earnings after market close today and will stream the call on X.
Watch live as SpaceX discusses our Q3 2026 earnings at 3:30pm CT today → https://t.co/Qrb0qeVG15
— SpaceX (@SpaceX) October 20, 2026
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here

Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for

SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms

SpaceX reports its second earnings today: here’s what to expect

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


