News
Tesla gets generous price target projection from ARK without several crucial factors

Tesla got a new, generous price target projection from analyst Cathie Wood and her firm ARK Invest, even though it left out several massive factors.
According to ARK’s latest Tesla projection report, which was released on Wednesday, the firm expects the company’s value to swell to $2,600 per share, with a bull case of potentially $3,100 and a bear case of $2,000.
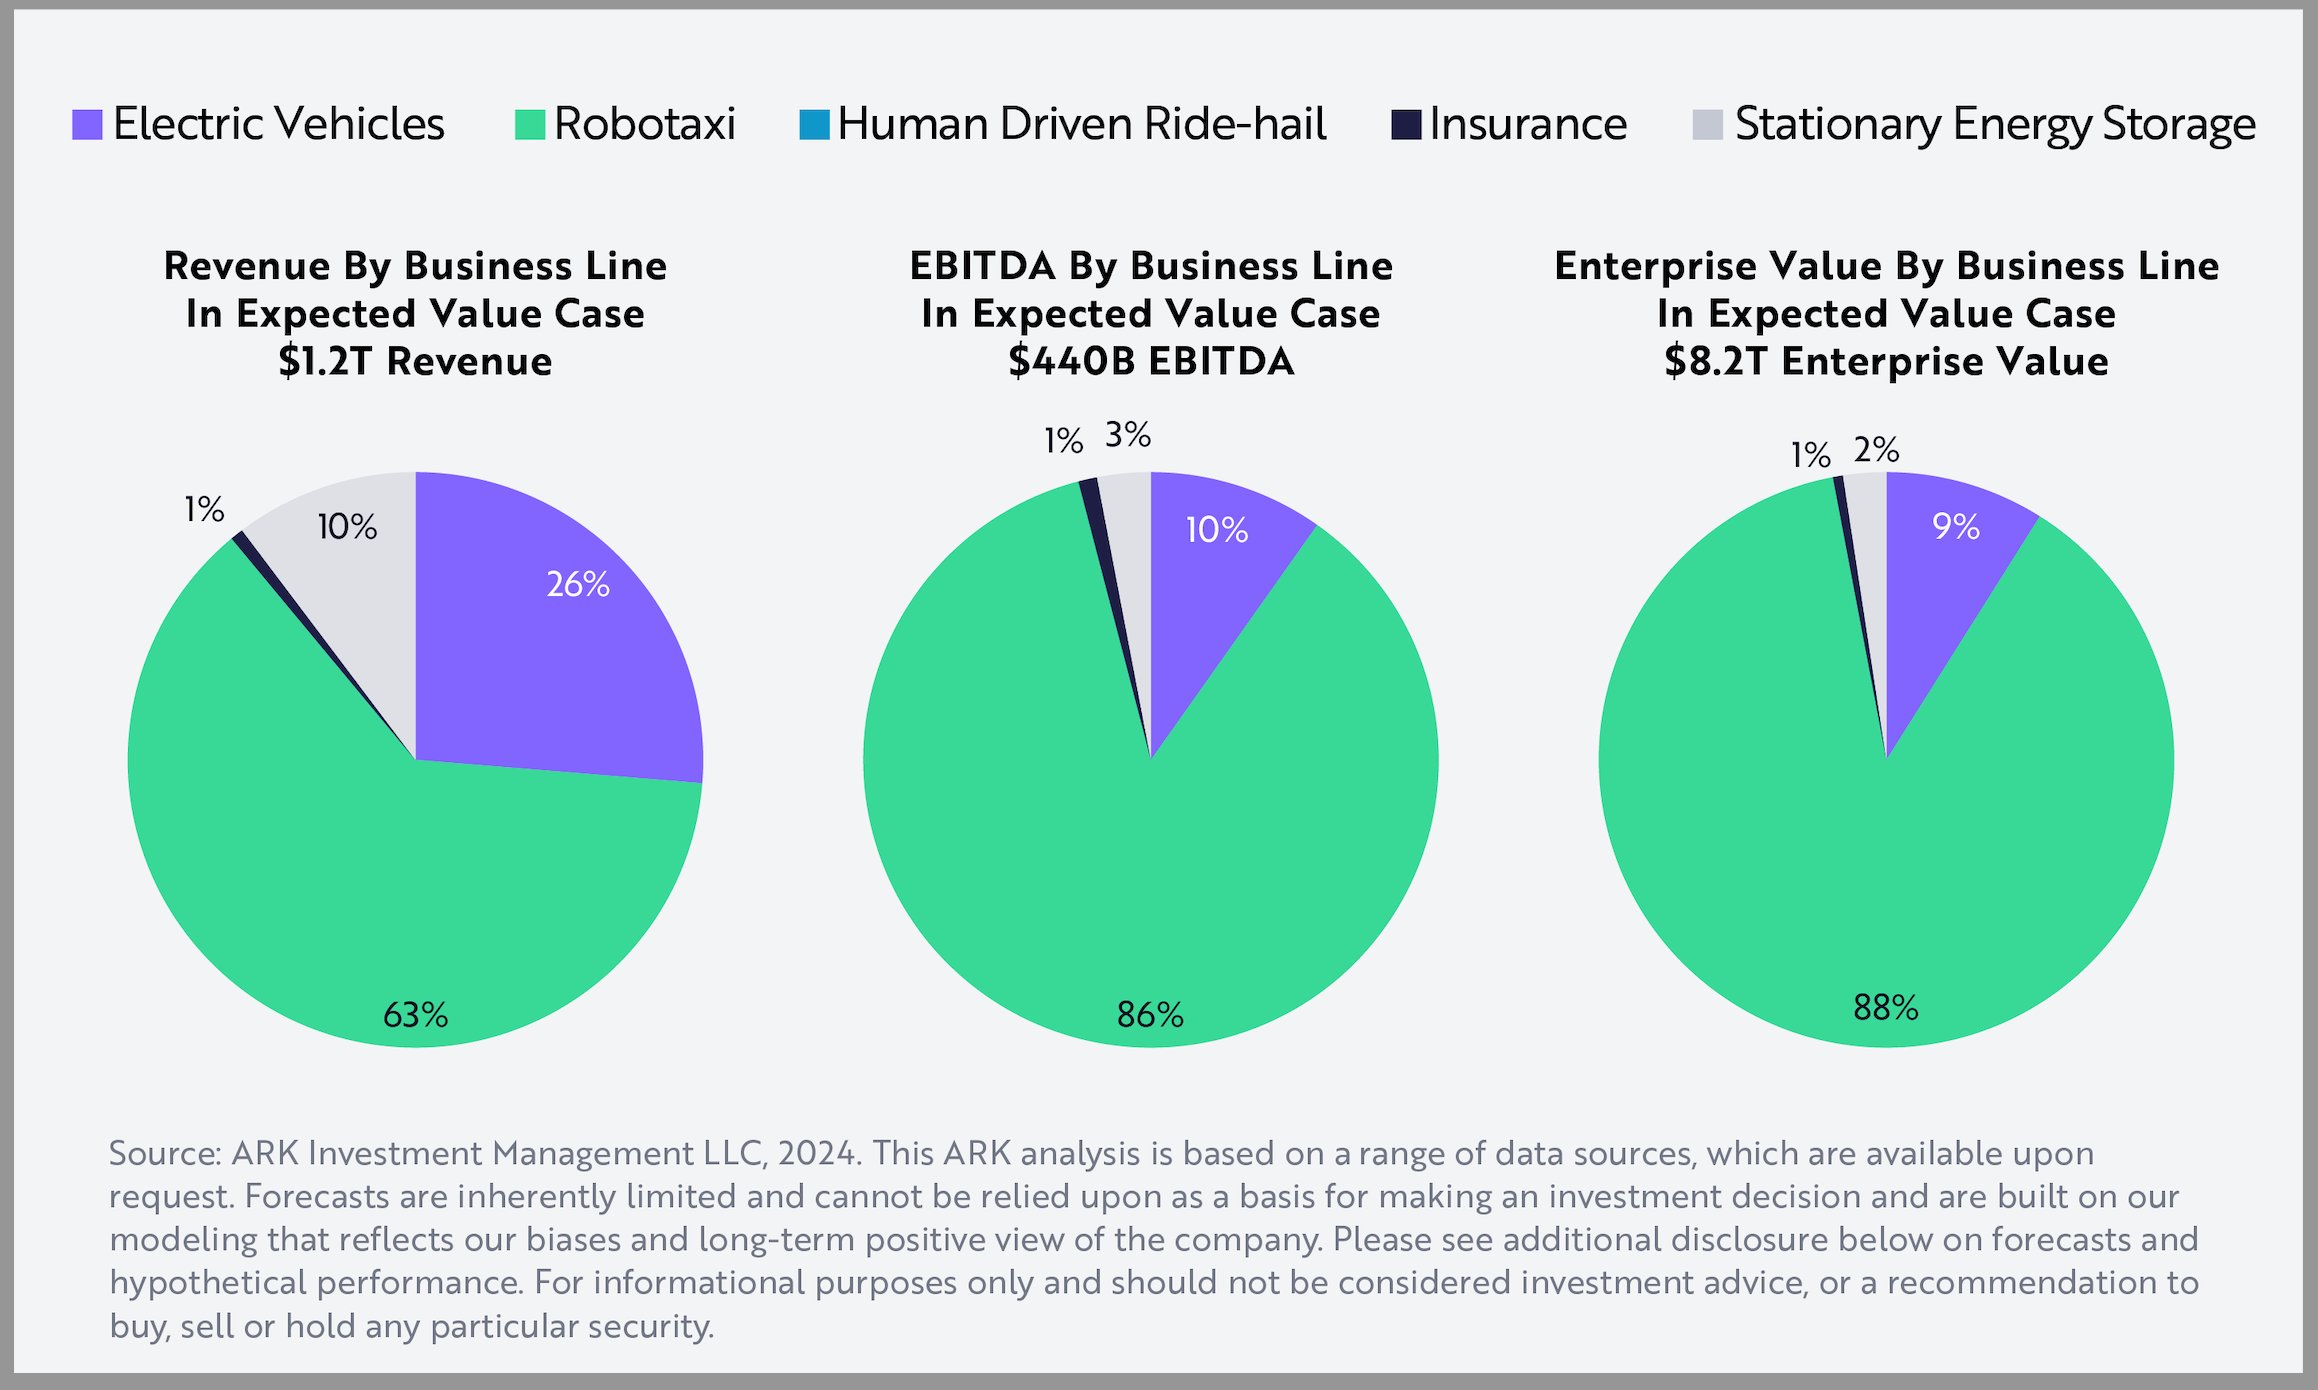
“ARK estimates that nearly 90% of Tesla’s enterprise value and earnings will be attributed to the robotaxi business in 2029, as shown below. Meanwhile, electric vehicles could approximate a quarter of total sales and ~10% of Tesla’s earnings potential, as we believe the robotaxi business will have much higher margins. The charts below break down attributable revenue, EBITDA, and enterprise value by business line,” its analysis breakdown said.
It is important to note ARK Invest has been particularly bullish on Tesla and its business model for some time. However, it was sure to note that in its latest projections, it did not factor in robotics, as Tesla continues to develop its Optimus Bot and recently stated it has been using it in Gigafactory Texas.
We conservatively assumed that Tesla does not sell Optimus externally in our model, and that Optimus manufacturing savings modestly impact Tesla’s costs in single digit percentages over the next five years.
— Tasha Keeney (@TashaARK) June 12, 2024
ARK broadened this idea in its report:
“We assume that Optimus will have minimal impact on our price target. Over the next decade, we expect Tesla to become a leading manufacturer and service provider of robots that move through physical space, as it will have the opportunity to leverage learnings from robotaxis as well as its in-house inference chips, training compute, and manufacturing scale. Tesla expects Optimus to be completing useful factory tasks by year end. Assuming that it were able to subsume 10-20% of Tesla’s labor hours worked with productivity equal to or twice that of its human counterparts, Optimus could save Tesla $3-4 billion, or 1-2% in manufacturing costs, in 2029.”
In fact, the largest single factor in its analysis is that of the Robotaxi, which accounts for the vast majority of the breakdowns ARK illustrated for Revenue, EBITDA, and Enterprise Value:
There are several things ARK left out of its analysts, and a few of them are arguably groundbreaking and could potentially have a major impact on Tesla’s business in the future:
- Tesla Semi – ARK does not believe the Tesla Semi will “contribute significantly” to the company’s value within the five-year investment time horizon
- Supercharging Network – Tesla Superchargers are “unlikely to generate significant revenue,” although they are essential for EVs
- FSD Licensing – Non-Tesla FSD vehicles are unlikely to debut within the five-year timeframe
- AI-As-A-Service – AI-inference-as-a-service and Dojo training-as-a-service is “probably” outside the five-year timeframe
You can read ARK’s full report here.
I’d love to hear from you! If you have any comments, concerns, or questions, please email me at joey@teslarati.com. You can also reach me on Twitter @KlenderJoey, or if you have news tips, you can email us at tips@teslarati.com.

News
NHTSA just escalated its Tesla Cybercab investigation in a big way
NHTSA escalated its Cybercab audit into a sworn Special Order with a September 30 deadline.

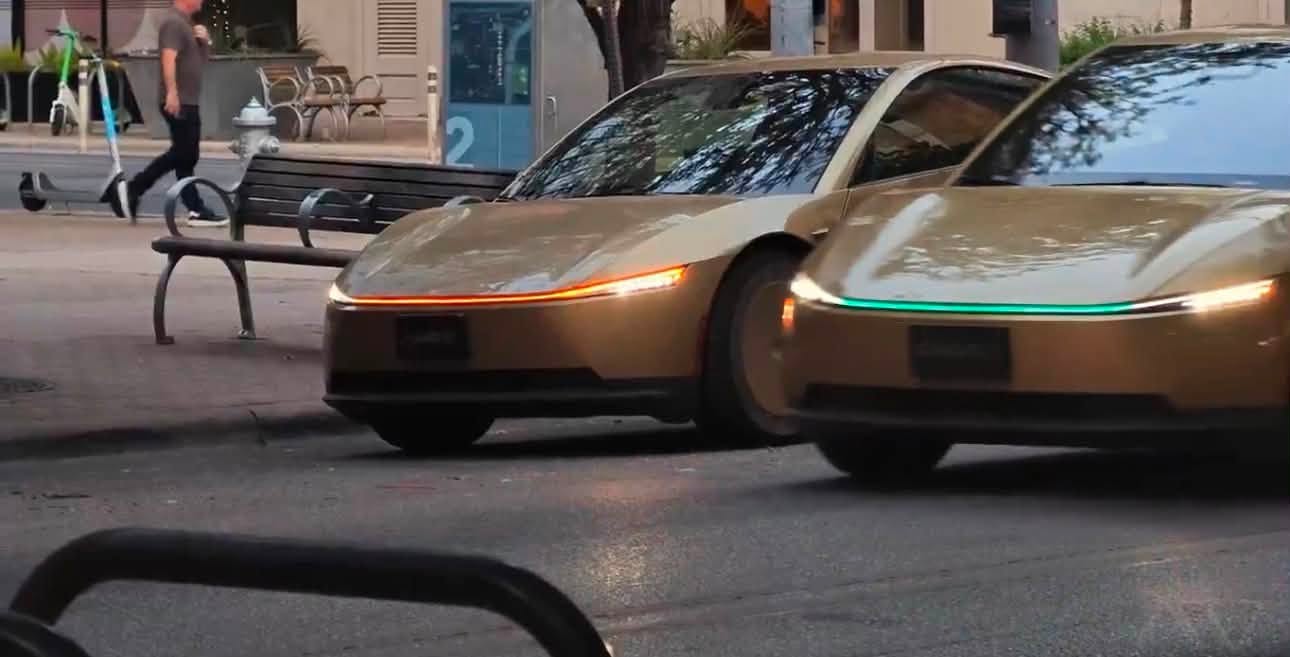
Federal regulators have moved from asking Tesla questions about its Cybercab to demanding sworn answers. The National Highway Traffic Safety Administration issued a Special Order that requires a Tesla officer to sign an affidavit attesting to the completeness of the company’s responses, with a deadline of September 30.
The order builds on Audit Query AQ26002, which NHTSA opened on September 3, the same day Tesla began commercial Cybercab service in Austin. Teslarati covered that initial inquiry when it surfaced, noting the agency wanted to understand how Tesla certified a vehicle with no permanently attached steering wheel, pedals, or mirrors as compliant with Federal Motor Vehicle Safety Standards. A Special Order is a different tool and converts a fact finding review into a legally enforceable demand, the same mechanism NHTSA used against Tesla in 2023 during its Autopilot investigation.
Several of the 21 requests target a specific gap in Cybercab’s design. One asks whether Tesla used temporarily attached human controls at any point to help certify the vehicle, and if so, which standards depended on that equipment being present. Another quotes an existing rule directly: “The service brakes shall be activated by means of a foot control.” Cybercab has no foot pedal. NHTSA wants a detailed explanation of how the vehicle satisfies that requirement, and how it complies without the kind of exemption granted to Zoox in July under Part 555, the regulatory pathway built for steering wheel free vehicles.
The order does not claim Cybercab is unsafe or that Tesla broke a rule. It requires Tesla to explain, under oath, the reasoning behind decisions the company already made when it self-certified the vehicle. That distinction matters, but so does the exposure. Motor1’s reporting, summarized here, put potential civil penalty exposure as high as $139 million if NHTSA later finds the certification was flawed, on top of whatever criminal risk comes with a false sworn statement.
Tesla has not said publicly how it plans to respond. Cybercab is still carrying passengers in Austin through the Robotaxi app while the September 30 deadline approaches, and the company has continued expanding the vehicle’s footprint even as the regulatory question remains open. The Special Order does not pause any of that and just sets a date by which Tesla has to put its certification logic on the record, with a company officer’s name attached to it.
In a new interview on Wednesday, Tesla uber bull Ron Baron said that anyone looking to buy the company’s stock should do so as soon as they can.
Baron, founder and CEO of Baron Capital and one of Tesla’s most persistent institutional bulls, used a CNBC Squawk Box appearance on Wednesday to deliver a familiar message with fresh urgency: In his opinion, Tesla stock is a buy:
“The time to buy the stock is now. FSD is catching on, and it’s going to be bigger and bigger. 55% of new buyers are buying it (Teslas) with FSD. It’s going to be everywhere. It’s safer.”
The Baron Capital frontman’s case is built around Full Self-Driving. Tesla reported 1.48 million active FSD subscriptions in the second quarter, up 56 percent year over year, and company officials have said roughly 55 percent of new North American deliveries left with a subscription enabled.
Baron framed that attach rate as proof the product is moving from enthusiast extra to default expectation, and as a reason software, not just vehicle volume, should drive the next phase of value.
His conviction on Tesla shares is not theoretical, as Baron Capital made its first Tesla investment in 2014, after years of meetings that began around the 2010 IPO roadshow. The firm later built a large SpaceX position starting in 2017.
Ron Baron today in new interview on Tesla:
“The time to buy the stock is now. FSD is catching on, and it’s going to be bigger and bigger. 55% of new buyers are buying it (Teslas) with FSD. It’s going to be everywhere. It’s safer.” pic.twitter.com/Rv5PB0bVZ2
— Sawyer Merritt (@SawyerMerritt) September 16, 2026
Baron said those Musk-led bets have generated about $30 billion of the $71 billion in profits Baron Capital has produced for clients. He put the firm’s current exposure at roughly $25 billion in SpaceX and $5 billion in Tesla. Personally, he described SpaceX as his largest holding, at about $5 billion, with about $1.5 billion in Tesla and additional Tesla exposure through the firm’s funds.
That concentration is also a statement of loyalty. Asked about talk of a SpaceX-Tesla combination, Baron said he had already walked Elon Musk through arguments for and against a deal, then declined to repeat them on air. His public position was simpler: “Whatever you decide is better is what I’m going to support,” he said to Musk.
Baron also said that he picked up the farewell edition of the Model S after Tesla decided to sunset the vehicle earlier this year, calling it his favorite car he’s ever driven.
Elon Musk
SpaceX’s next Starship launch is about to attempt its biggest leap yet
SpaceX targets September 22 for Starship Flight 14, its first attempt to reach real orbit.
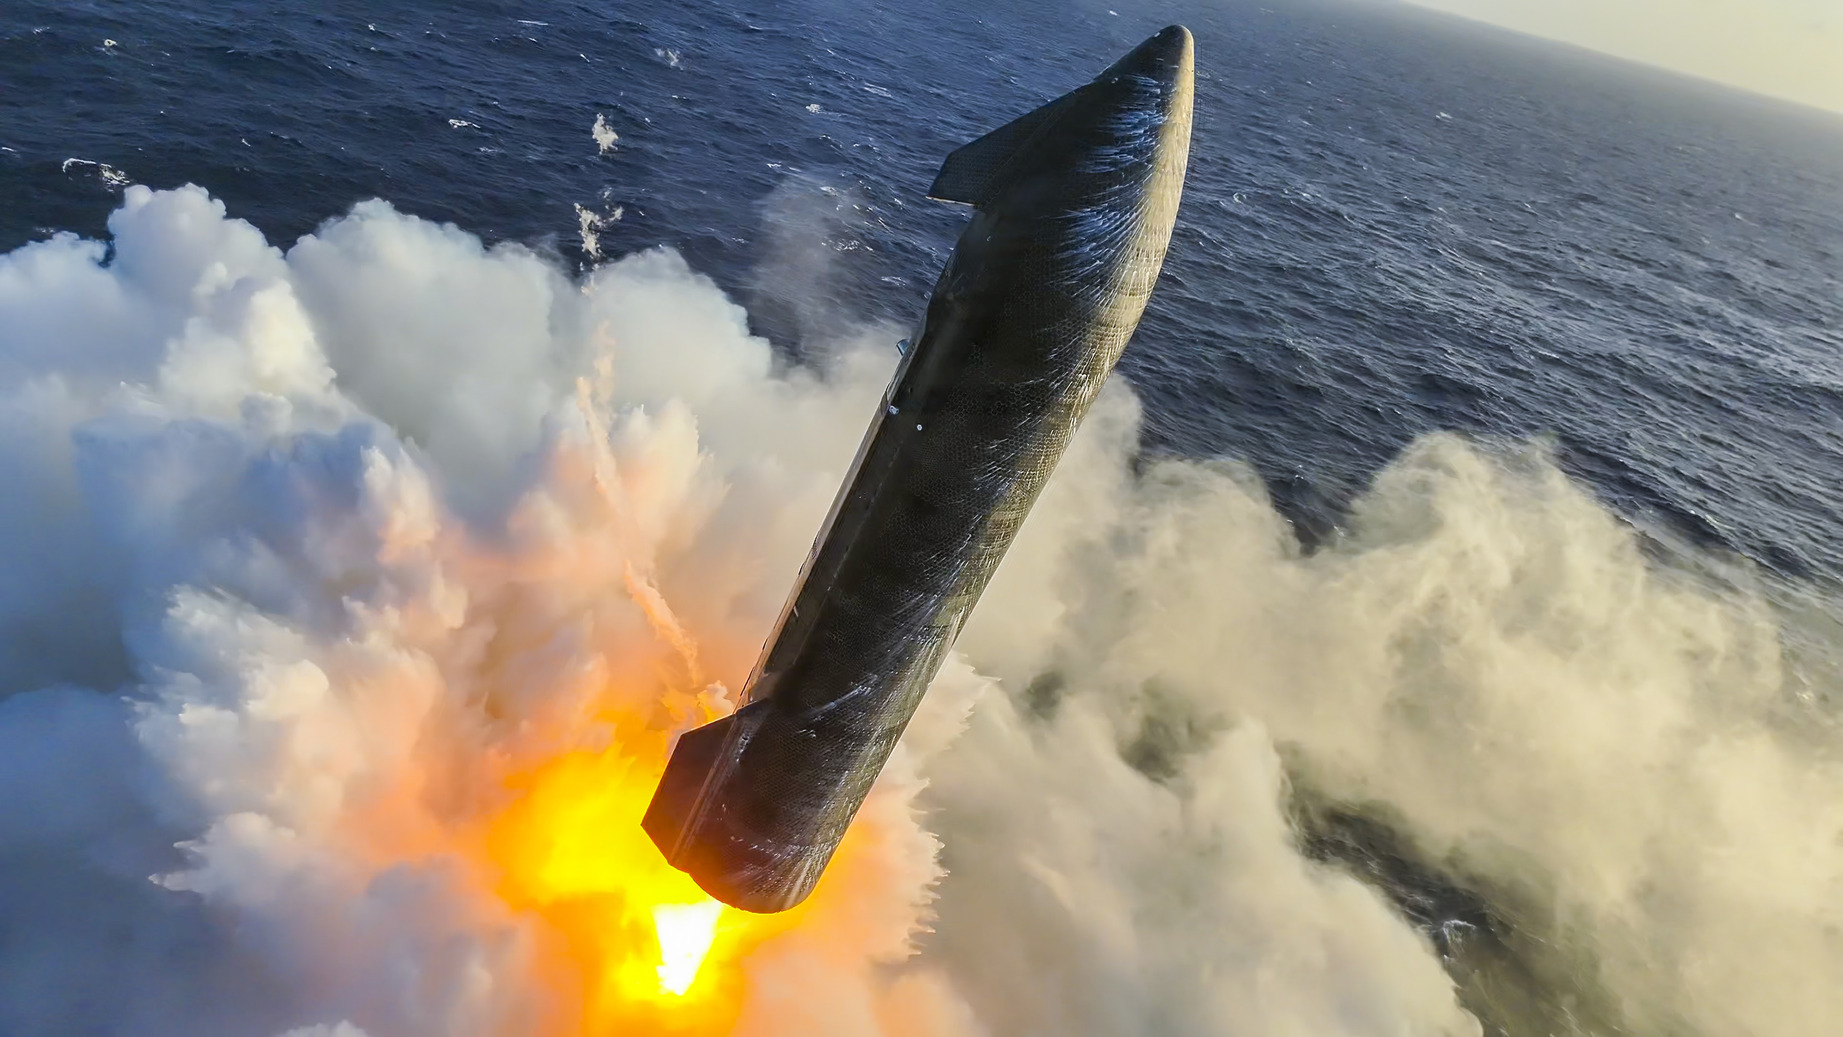
SpaceX has set September 22 as the target date for Starship’s 14th test flight, and this one carries a different goal than any of the 13 that came before it. Every previous Starship mission has intentionally flown a suborbital arc, reentering the atmosphere within the same hour it launched. Flight 14 is designed to send the craft into a genuine orbit around Earth for the first time.
The launch window opens at 7:15 a.m. Central time at Starbase in South Texas and runs for 75 minutes, pending regulatory approval, according to SpaceX’s mission description published Tuesday. If the flight goes as planned, Starship will circle the planet roughly six times at an altitude near 275 kilometers over about ten hours before a deorbit burn sends it toward a splashdown in the Pacific Ocean west of Chile, a departure from the Indian Ocean recoveries used on the last several flights.
The mission also marks the first attempt to put a working batch of Starlink V3 satellites into actual service. Flight 13 carried 20 of the new satellites in July, but because that mission never left a suborbital trajectory, the payload reentered along with the ship instead of separating into orbit.
SpaceX tells the FCC that Starship Flight 14 is going to orbit
Each V3 satellite is rated for roughly one terabit per second of downlink capacity, so a successful deployment on Flight 14 would be SpaceX’s largest single jump in network bandwidth since Starlink began flying on Falcon 9.
Flight 13 still did the heavier lifting on the technical side. That July mission flew a deliberately more stressful reentry profile to test Starship’s heat shield, and the ship survived its softest splashdown yet, intact enough for drone inspections shortly after landing. Elon Musk said the flight delivered “all the heat shield data we needed and then some,” a result Teslarati covered in detail when he later said SpaceX had solved the vehicle’s biggest reusability challenge. Flight 14 is where SpaceX starts spending that confidence on an actual orbital insertion rather than another controlled fall back to Earth.
One thing Flight 14 will not attempt is a tower catch of the ship. Musk floated the idea right after Flight 13, but walked the timeline back in August, saying a catch attempt was more likely “in a few months.” The Super Heavy booster will still aim for its own recovery, targeting an offshore landing point in the Gulf of America, the same approach used on recent flights.
September 22 is SpaceX’s own target, not a locked date. Starship’s schedule has slipped before over hardware readiness and FAA sign off, and the company has said as much in its own mission notes. But the plan itself represents the clearest marker yet that Starship is moving from a suborbital test program into something meant to carry paying payloads and, eventually, people.

NHTSA just escalated its Tesla Cybercab investigation in a big way

Tesla uber bull Ron Baron says ‘the time to buy the stock is now’


