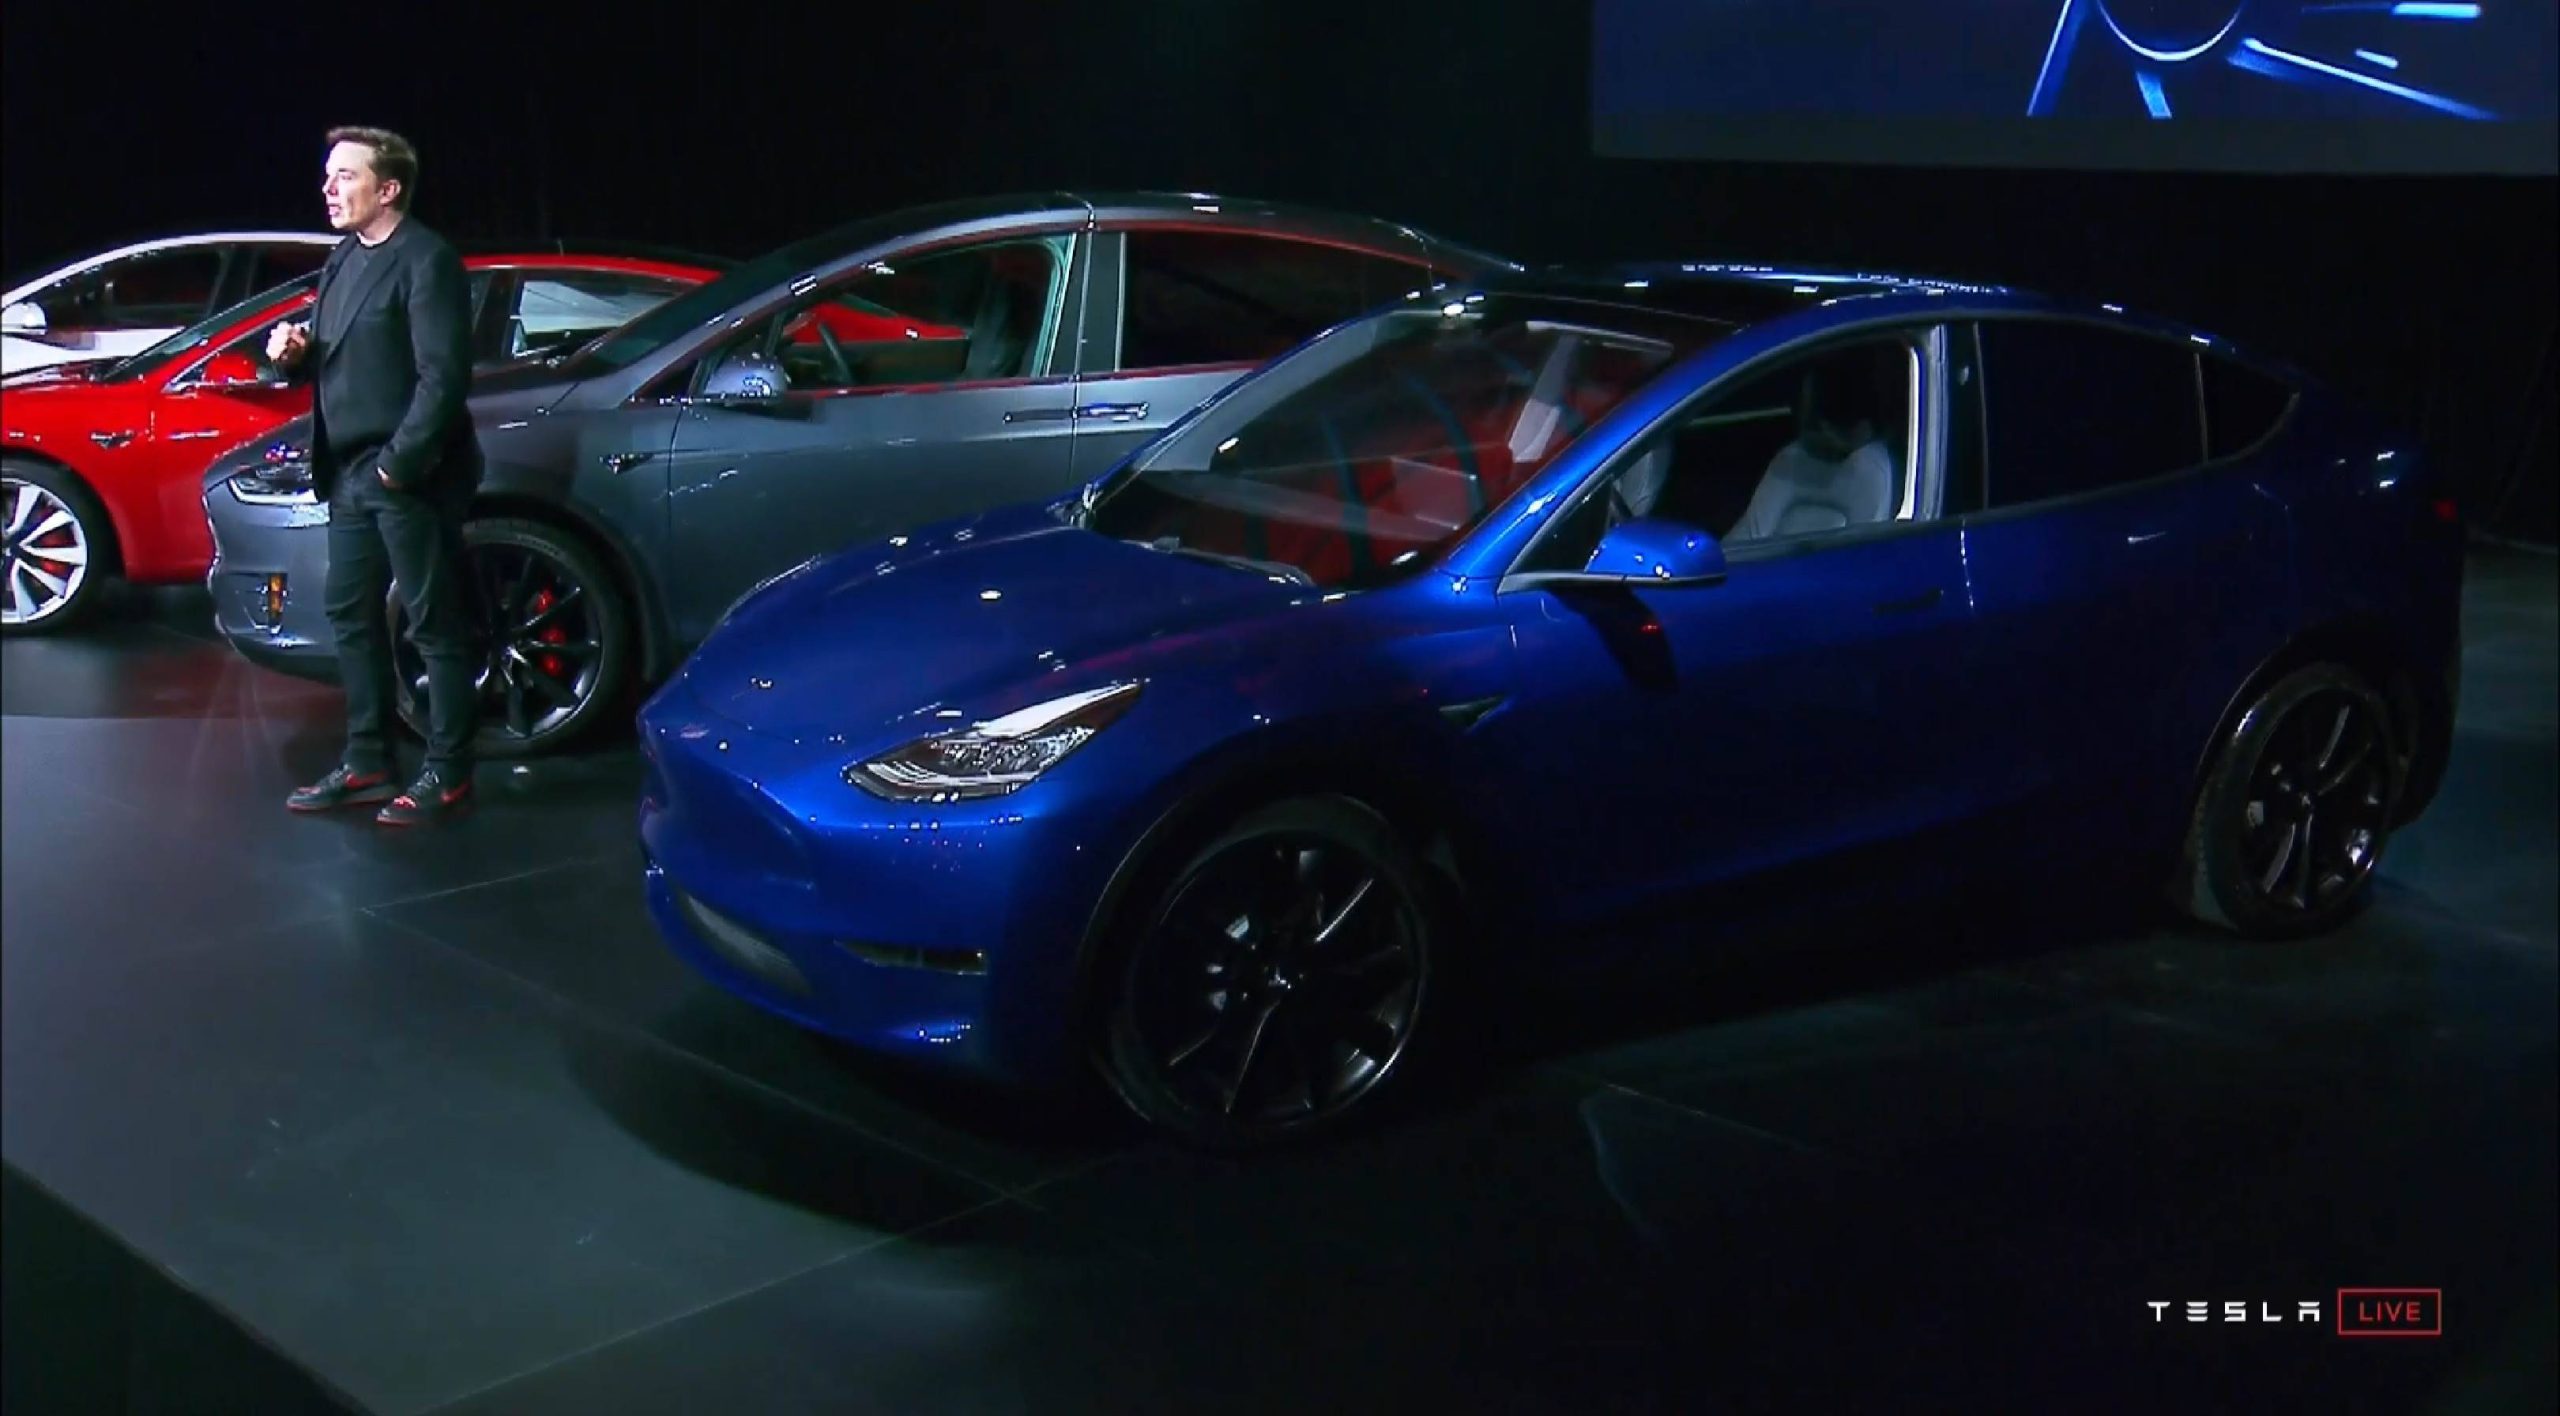

Tesla (NASDAQ:TSLA) is heading into what could be its most important earnings results yet, with the company riding a momentum that has built up since the dip that resulted from the results of its Q3 vehicle production and delivery reports. With Q3 2019’s earnings call just around the corner, here are Wall Street’s current expectations for the Silicon Valley-based electric car maker.
Earnings
Thirty-three analysts polled by FactSet expect Tesla to report an adjusted loss of $0.46 a share for the third quarter of 2019. This contrasts with an adjusted profit of $2.90 per share that Tesla exhibited in Q3 2018, a period that surprised critics with its GAAP and adjusted per-share profits.
On the other hand, Estimize, a crowdsourcing platform that aggregates estimates from Wall Street analysts, buy-side analysts, company executives, academics, fund managers, and the like, expects Tesla to show an adjusted loss of $0.29 per share.
Revenue
FactSet analysts expect the electric car maker to report sales of $6.45 billion, down from $6.82 billion from Q3 2018. This is partly due to the majority of the company’s deliveries now being focused on the much more affordable Model 3 sedan, which is shipping in higher volumes compared to the flagship Model S and X. Compared to the flagship sedan and SUV, the Model 3 is yet to prove that it can be a fully profitable vehicle for Tesla. Q3 2019 could thus be a pivotal point for the all-electric sedan.
Estimize, on the other hand, expects Tesla to show a revenue of $6.60 billion.
The stock so far
Tesla shares have experienced a steep fall in 2019, losing around 22% of its value and down less than 1% in the past 12 months. This compares unfavorably to the S&P 500, which has gains of 20% and 16%, respectively; as well as the Dow Jones Industrial Average, which has shown an advance of 9% and 7% for the 12-month period.
Analysts polled by FactSet have an average price target of $269.67 for TSLA stock. That’s an upside of about 4% from the electric car maker’s current levels.
Analysts’ Take
David Whiston, an analyst with Morningstar, is optimistic about the electric car maker’s chances for Q3 2019. Despite the declining numbers for the lower-volume but profitable Model S and X, Whiston believes that he remains “cautiously optimistic” about the electric car maker.
“With Tesla young and trying to scale up, I’m always interested in their free cash flow or burn for a quarter. That’s the most important thing to me because it’s a measure of health and ultimately of its ability to service its debt. The shift to the Model 3 while Model S and Model X sales are declining, plus increased costs with a raft of planned new vehicles and investments in driverless-car technologies “always create the question of: ‘Is volume sufficient enough to make up for reinvesting in the business?’ Tesla is a long-term story, and one quarter is unlikely to make or break the company,” he said.
Bill Selesky, an analyst with Argus Research, is also convinced that demand for Tesla’s vehicles remain robust despite the stock’s headwinds this year. “Tesla still enjoys strong demand for its vehicles, especially for the Model 3, and from people who did not put down deposits. That’s a good sign for me, telling me that things continue to get better on the demand side. They just need to get production issues corrected and focus on cost controls,” he said.
Tesla will be posting its financial results for Q3 2019 after the market closes on Wednesday, October 23, 2019. The company would be issuing a brief advisory with a link to its Q3 2019 Update Letter, which will be accessible from Tesla’s Investor Relations website. A live Q&A session is set for 3:30 p.m. Pacific Time (6:30 p.m. Eastern Time) to discuss the electric car and energy company’s financial results and outlook.
As of writing, TSLA stock is trading +0.55% at $254.90 per share.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.

Elon Musk
Elon Musk breaks his silence on the Starlink impact to Ukraine drones
Musk says the US military and president set Starshield limits, not SpaceX, amid Ukraine complaints.

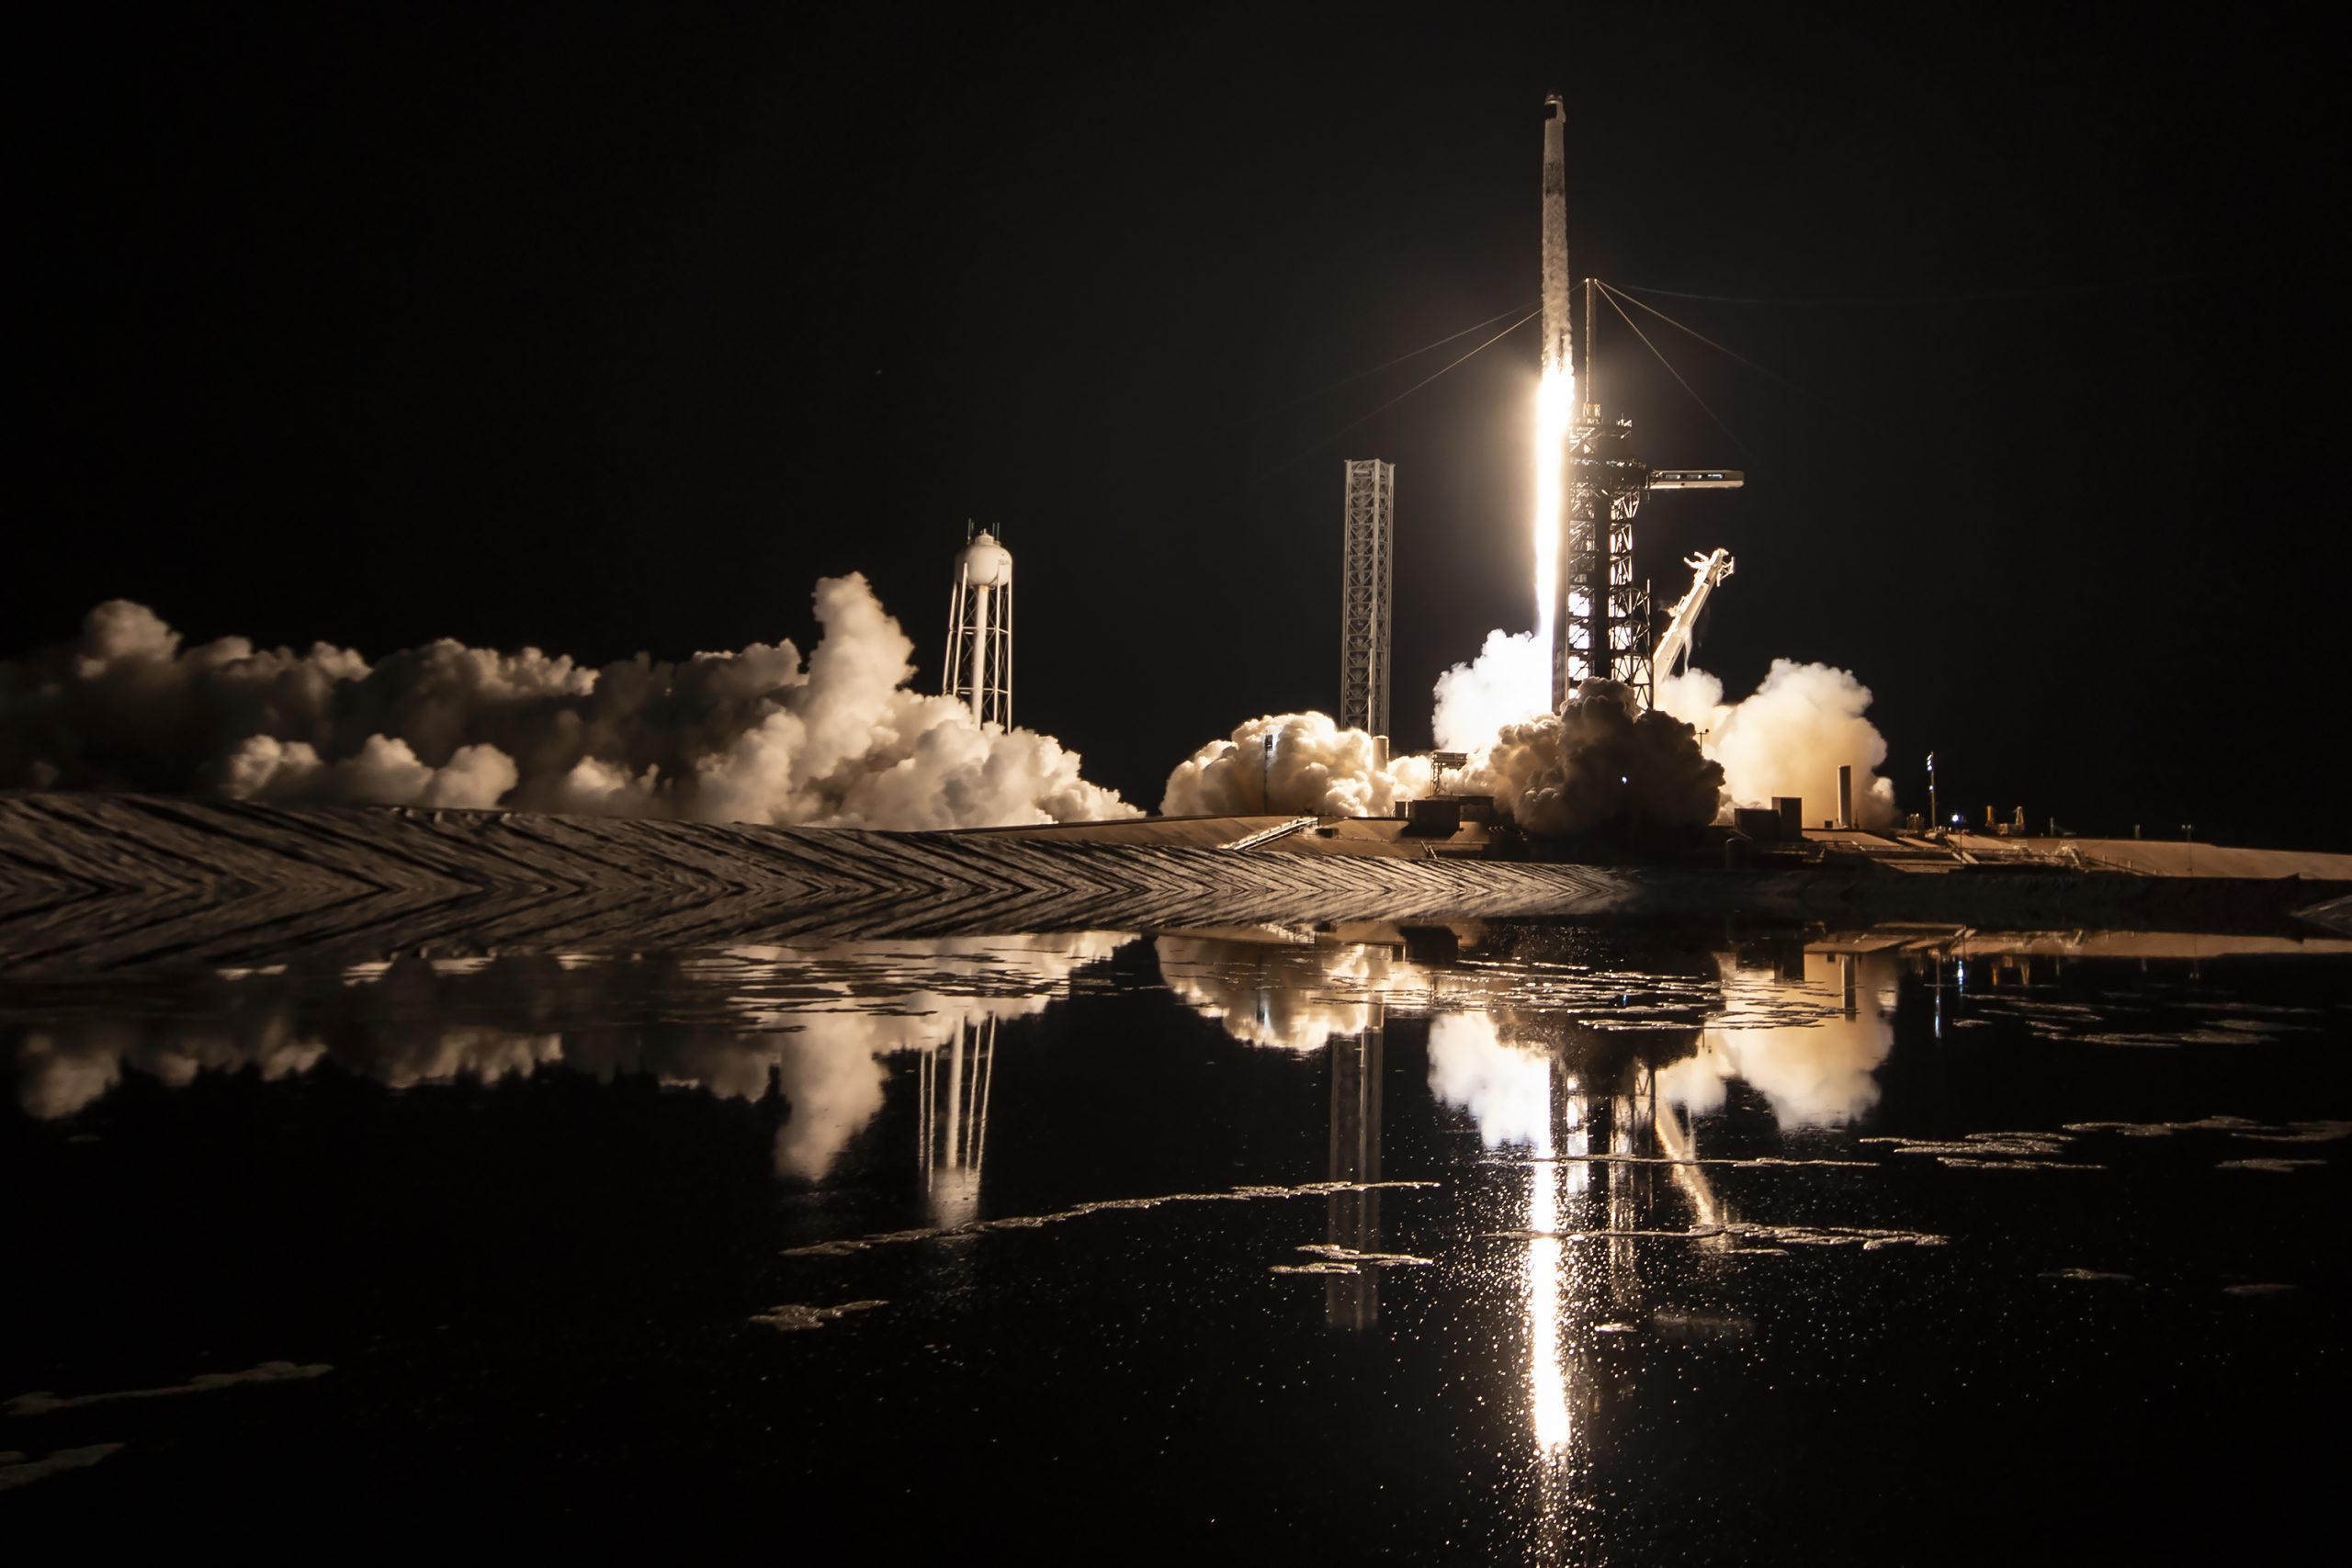
Elon Musk says the speed limit cutting out Ukraine’s military Starlink terminals is not SpaceX’s decision. In a post on X Wednesday, Musk wrote that “Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.” He added that Starlink is a commercial service limited to civilian or defensive activities and “cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.”
He was replying to Mykhailo Fedorov, Ukraine’s former defense minister, who had thanked Musk for restoring connectivity at speeds up to 160 km/h and said removing the Starshield limit entirely is “now critical for Ukraine’s defense.”
Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.
Starlink is a commercial service owned and controlled by SpaceX. Usage of Starlink is limited to civilian or defensive activities and cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.
— Elon Musk (@elonmusk) October 14, 2026
The complaint started Tuesday night, when Ukrainian officials said military terminals began losing service above roughly 100 mph. Presidential adviser Serhiy Beskrestnov said the defense forces got no warning and several missions were disrupted, as Teslarati reported earlier Wednesday. The 7th Rapid Reaction Corps told Reuters connections dropped for 10 to 20 seconds at speeds well below the limit, which made drones harder to control. Poland’s foreign minister, Radoslaw Sikorski, asked Musk on X whether he is “playing politics with your products again.”
That is why the Starlink and Starshield distinction matters. SpaceX introduced Starshield in 2022 as the government version of Starlink, with an initial focus on Earth observation, communications and hosted payloads. It won a Space Force contract in 2023 with a $70 million ceiling. In December 2024, the Pentagon moved Ukraine’s terminals onto Starshield, covering about 3,000 units across two contracts. Ukraine’s military connections therefore run through a service that Musk now says sits under Washington’s control.
While Musk’s post describes who holds authority, it does not infer that anyone ordered the limit, and neither SpaceX nor the US government has confirmed who set it. Ukrainian officials have pointed to the timing, which follows President Trump’s push for an energy ceasefire and Musk’s Saturday post that “Zelensky has gone too far.” The BBC noted Trump denied threatening to restrict intelligence sharing with Kyiv, and no evidence has been presented that Washington requested the cap.
The episode also revives a promise from 2025. After Poland accused him of threatening Ukraine’s access, Musk said Starlink “will never turn off its terminals” and would not be used as a bargaining chip. Poland has since supplied more than 29,000 terminals to Ukraine. Teslarati also covered Kyiv’s search for Starlink alternatives in 2025, and the latest dispute gives that search new urgency.
Investor's Corner
Tesla opens the Q&A for its biggest earnings call yet
Tesla opens its Q3 earnings Q&A, and Cybercab, Robotaxi, Optimus and regulators loom over October 21.
Tesla has opened its shareholder question portal for the Q3 2026 earnings call, with the Say Q&A page already listing questions. Investors have until 4:00 p.m. EDT on October 20 to submit and vote on what management should answer.
The call is set for Wednesday, October 21. Tesla will post results after the market closes, with a live webcast at 4:30 p.m. CT, or 5:30 p.m. ET, through its investor relations site.
Say ranks questions by the number of shares behind the votes, which gives institutional holders extra weight over the retail crowd.
Ahead of Q2, retail investors asked why Robotaxi growth had stalled, when Cybercab would start customer rides, and where the Optimus Gen 3 ramp stood, while an institutional holder asked how Tesla and SpaceX would split Terafab duties. Cybercab has since answered one of those. Tesla said last week it has 300 plus Cybercabs serving Austin, up eightfold in 30 days, with Dallas named as the next city. The questions now are likely to move from when to how fast.
There is also a regulatory question hanging over the call. NHTSA has demanded sworn answers on how the pedal free Cybercab was certified against federal safety standards, with responses due October 30, nine days after the call. Whether an analyst raises it live is unknown, but it is the kind of exposure that tends to find its way into a Q&A.
The numbers will not be the main draw. Tesla already reported 486,532 deliveries and 13.7 GWh of storage for the quarter. Consensus sits around 43 to 45 cents per share on roughly $27.8 billion in revenue, according to Zacks, after a Q2 report that missed on EPS. Goldman Sachs, which holds a Neutral rating and a $360 target, argues the outlook for Robotaxi, FSD and Optimus will matter more to the stock than the quarter itself.
The call also lands six days after the rescheduled Roadster event, which Tesla will stream on X on Thursday, October 15, at 7:55 p.m. CT. If the Roadster shows up with a production date or a SpaceX thruster package, expect it to climb the voting list before the deadline.
Elon Musk
FAA kicks off review of SpaceX’s bid to fly Starship nearly every day
FAA is reviewing SpaceX’s plan for 456 Starship launches a year, up from 25 today.
The FAA said Tuesday that it will prepare an environmental impact statement on SpaceX’s proposal to run as many as 456 Starship launches and 912 landings a year from Starbase, Texas. SpaceX is currently authorized for 25 launches and 50 landings annually, which makes the request roughly 18 times the existing ceiling. The notice of intent is set to publish in the Federal Register on Wednesday.
The plan comes in two phases. Phase 1 would allow up to 100 launches and 200 landings a year, on any day and at any hour. Phase 2, which the FAA says could arrive within several years, would raise the limit to the full 456 launches, still at any hour but only on weekdays. The agency noted that 912 landings is the upper limit for the Texas facility no matter where a given mission begins, and that Starship and Super Heavy could come down at the launch site or in the Gulf and open ocean.
A draft statement will be released for public comment at a later date, and the FAA has not said when. According to the Federal Registar, written comments are due November 30 on regulations.gov under docket FAA-2026-12808, with in person scoping meetings on November 17 in Brownsville and November 19 in Port Isabel, plus a virtual session on November 18. The review will weigh air quality, wildlife, coastal resources, water, noise, and aviation, and the FAA said any increase beyond this proposal would need its own separate review.
The numbers look large next to what Starbase has actually done. Starship has flown three times from Texas this year, including Flight 14 on September 28, the first orbital flight, which deployed 26 Starlink V3 satellites. Bloomberg reported that Starbase has never launched more than five times in a calendar year. The current cap of 25 comes from an FAA approval in May 2025. In February, the agency also approved up to 44 Starship launches a year from Launch Complex 39A in Florida, so Phase 1 in Texas alone would more than double that allowance.
Musk has said Starship could eventually fly more than once per hour within less than a decade, per Bloomberg. The nearer term target is Flight 15. Musk said on October 10 that it is hopefully four to six weeks away and will try to catch the ship with the tower, as Teslarati covered. That flight still runs under the existing 25 launch limit, and so would every Starbase launch for as long as the new review takes.
As of mid morning Pacific time on Tuesday, SpaceX had not posted about the filing on its own account.

Elon Musk breaks his silence on the Starlink impact to Ukraine drones

Tesla opens the Q&A for its biggest earnings call yet

Ukraine says Starlink is cutting out its military drones as Poland calls out Elon Musk

The Pentagon taps Elon Musk to design the battlefield of the future

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions


