News
SpaceX is in no rush for a Starlink IPO and that should terrify competitors

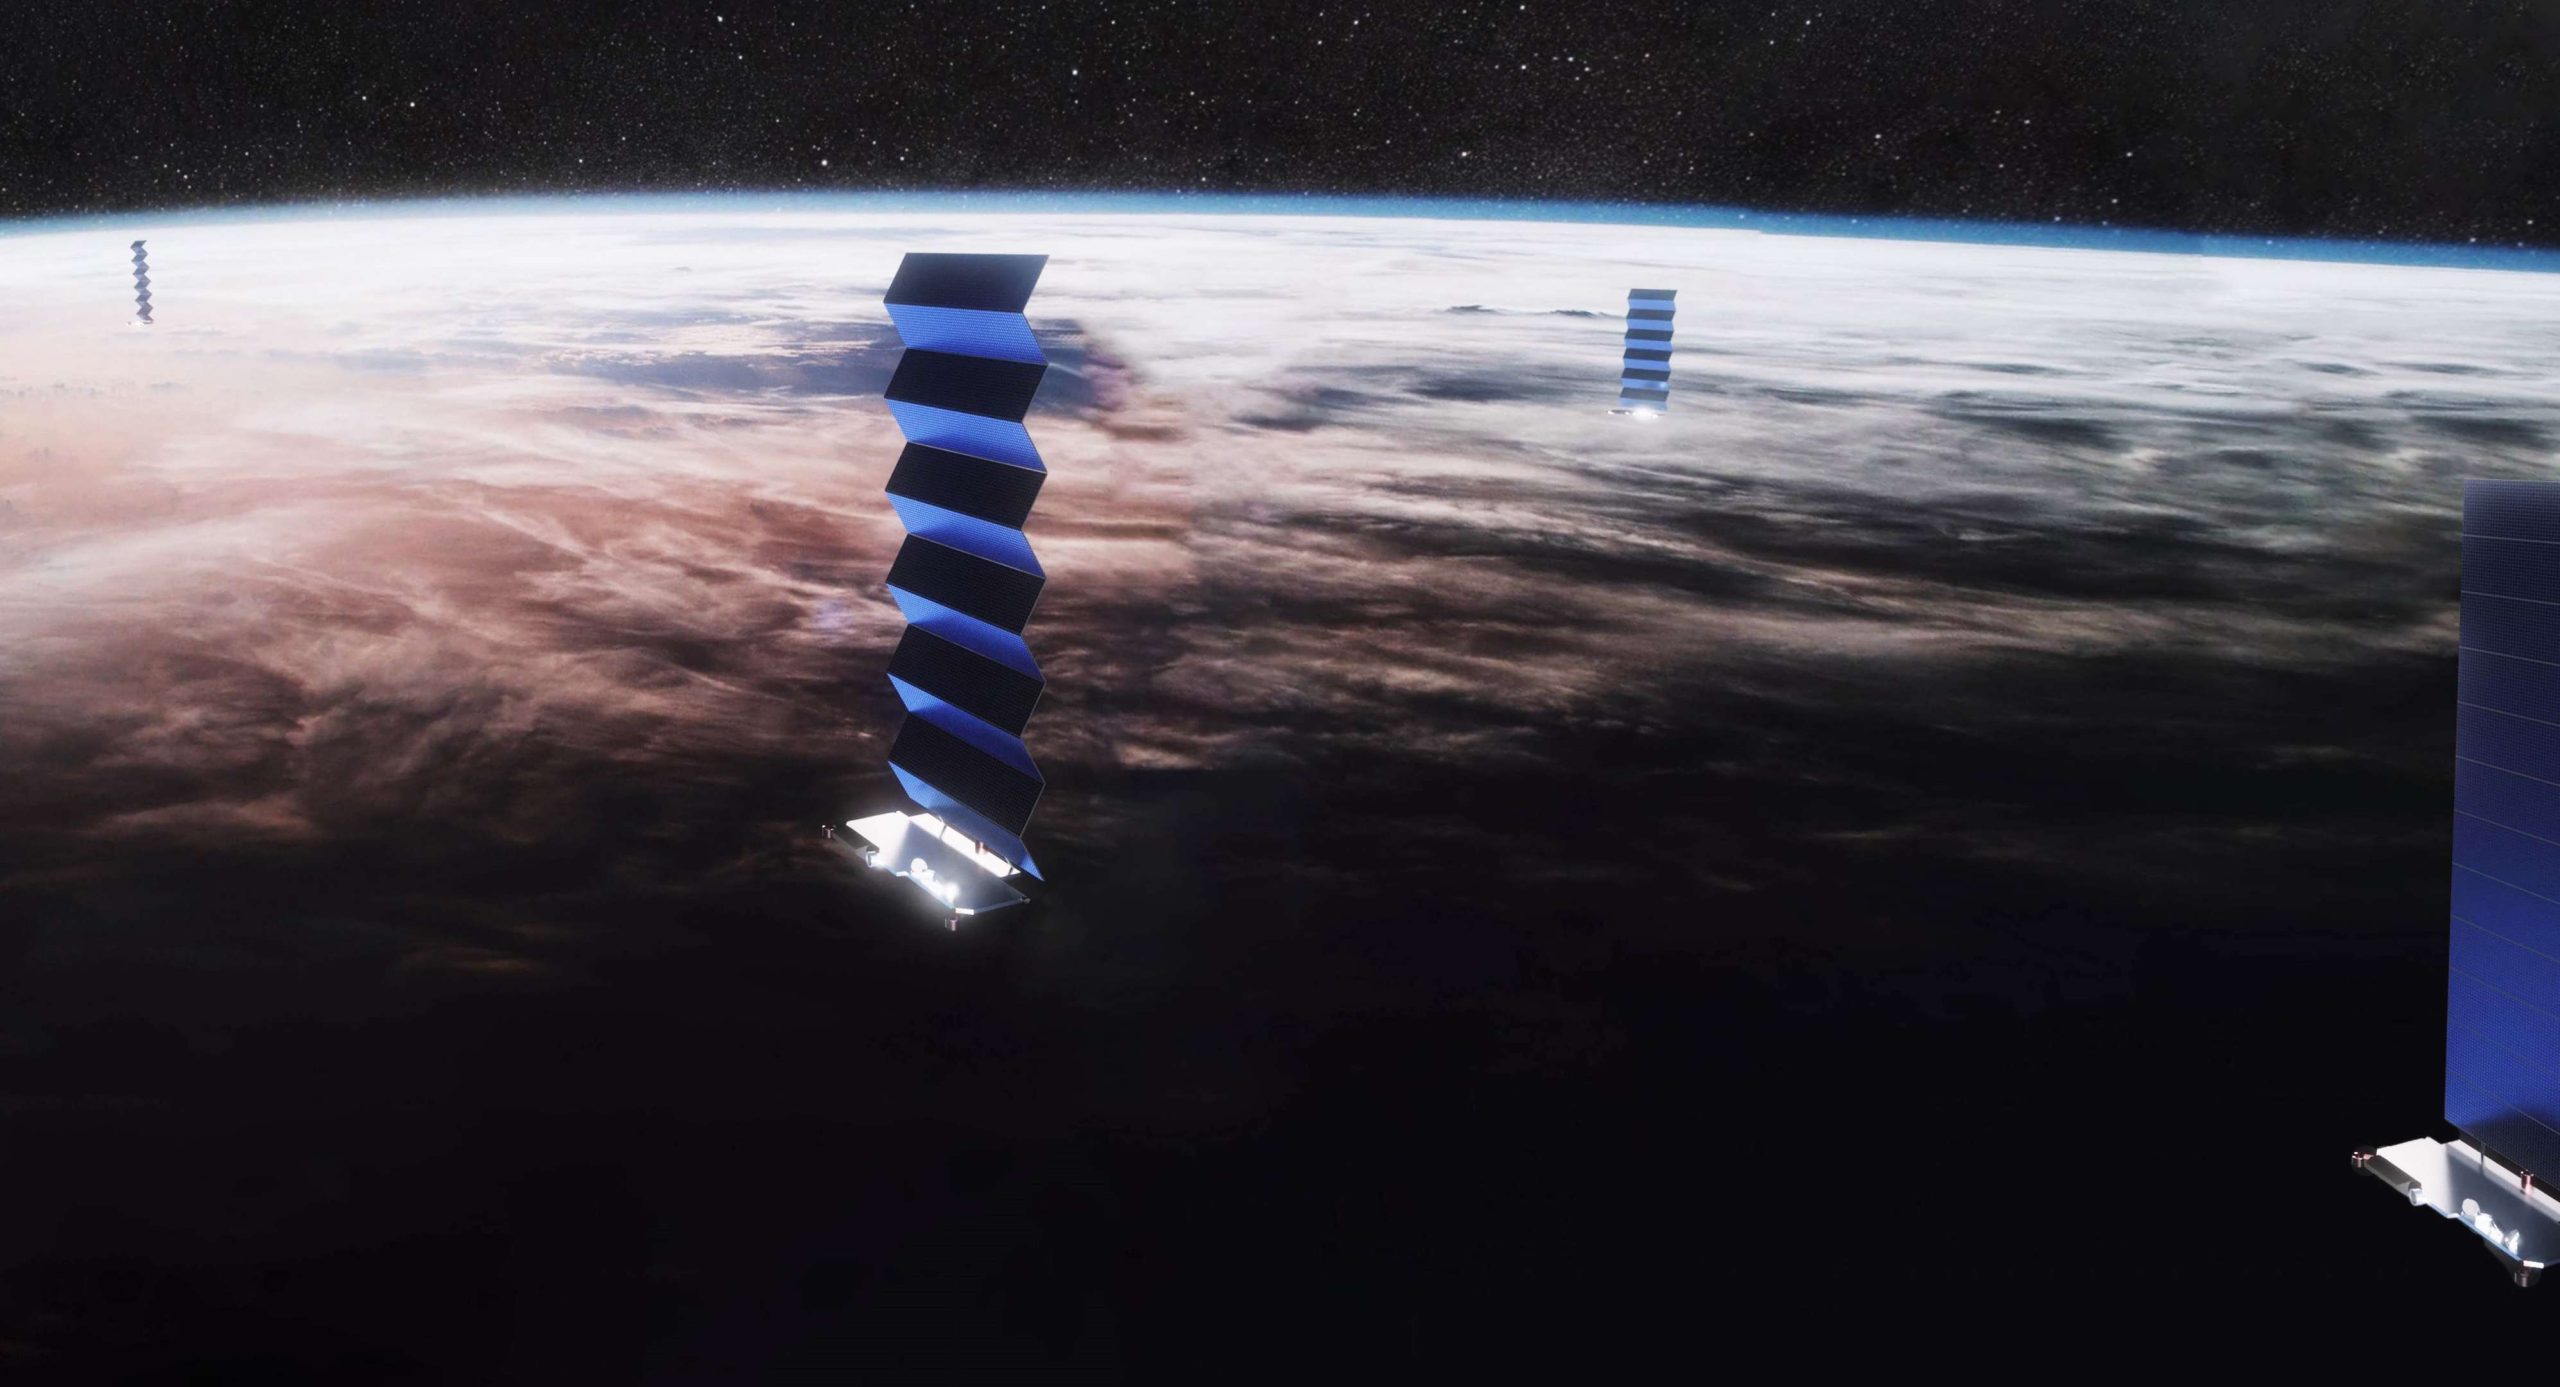
SpaceX President Gwynne Shotwell says that the Starlink satellite internet business is in no rush to become a separate company and pursue an IPO, and that relaxed demeanor should terrify competitor constellations and ISPs like OneWeb and Comcast.
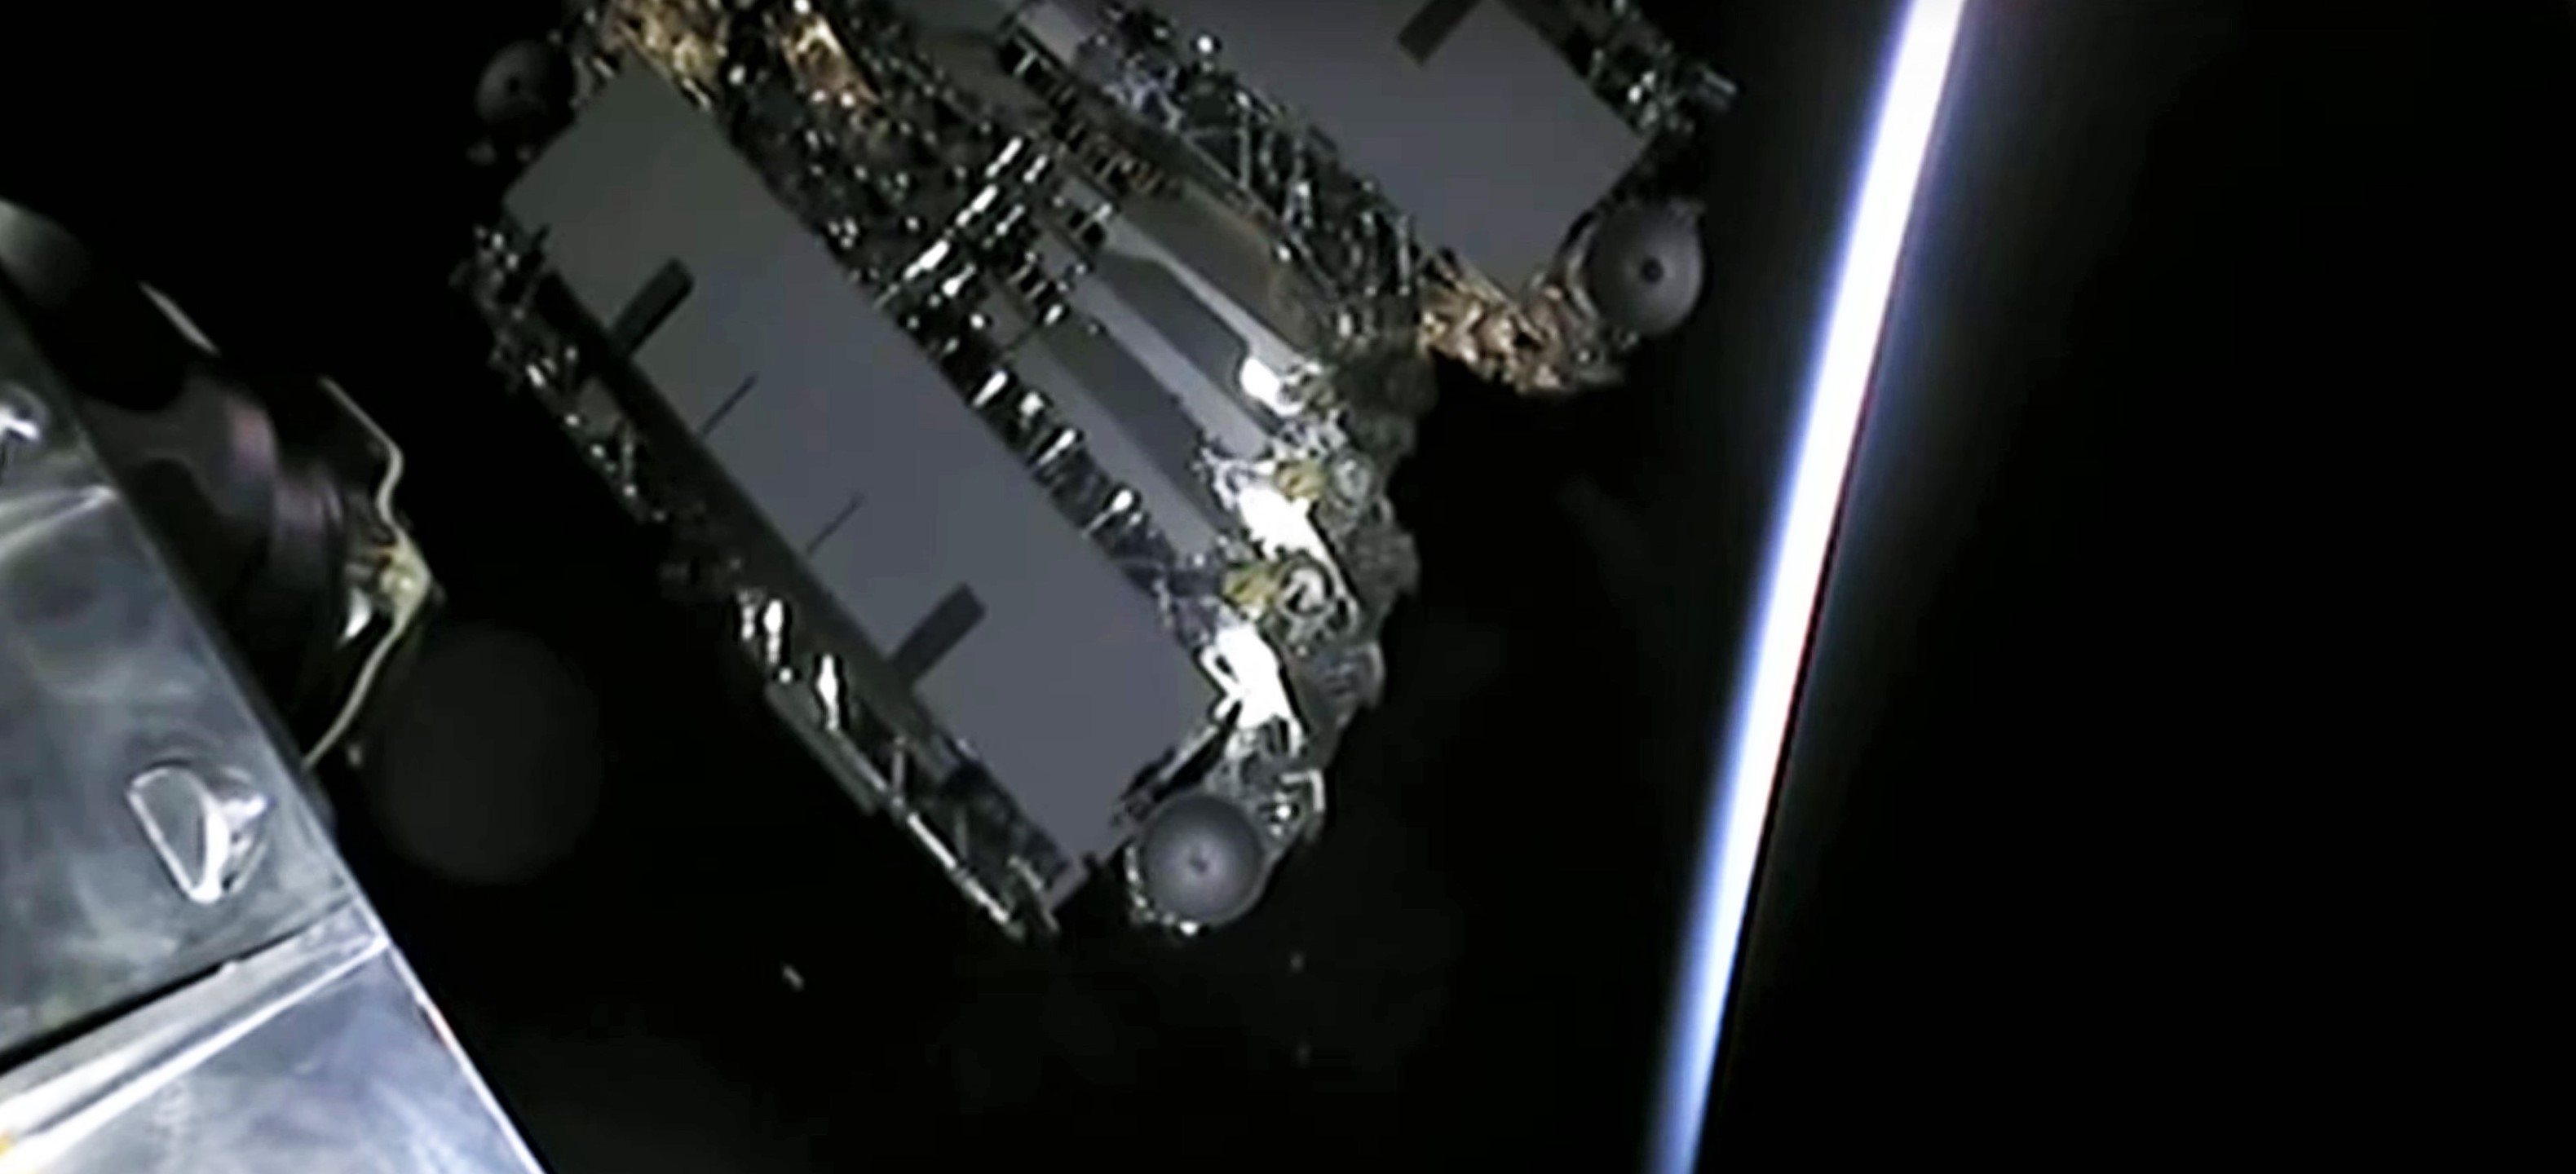
Announced in January 2015, SpaceX has been developing a massive constellation of satellites capable of delivering high-quality broadband internet anywhere on Earth for half a decade. Known as Starlink, SpaceX launched its first dedicated satellite prototypes – known as Tintin A and B – in February 2018, serving as a very successful alpha test for the myriad technologies the company would need to master to realize the constellation’s goals. 15 months later, SpaceX launched its first batch of 60 radically-redesigned Starlink satellites – packed flat to fit in an unmodified Falcon 9 payload fairing.
Less than nine months after that first ‘v0.9’ mission, SpaceX has completed another three dedicated launches and made Starlink – now some 235 operational satellites strong – the world’s largest private satellite constellation by a huge margin. Now just two days away from its fifth Starlink launch, SpaceX’s second-in-command has revealed that the company will likely split Starlink off into its own separate company, enabling an IPO without sacrificing SpaceX’s broader freedom. However, Shotwell also made it clear that SpaceX is in no rush to do so, and that fact should strike fear into the hearts of Starlink’s many potential competitors.
Bloomberg first broke the news with a snippet revealing that SpaceX COO and President Gwynne Shotwell had told a private investor event that Starlink could eventually IPO as an independent company. While undeniably important, a SpaceX source – after confirming the news – also told Reuters reporter Joey Roulette that it would be “several years” before the company might kick off the process of a Starlink IPO.
While a seemingly small piece of information at face value, the fact that SpaceX is years away from a potential Starlink IPO implies that the company is incredibly confident in where it stands today. Given that SpaceX only started ramping up its Starlink production rates and launch cadence a handful of months ago, that apparent confidence – assuming SpaceX’s respected President and COO isn’t lying to the faces of prospective investors – is no small feat.
Thanks to that production and launch cadence ramp, SpaceX is likely in the midst of one of the most capital-straining periods its Starlink program will ever experience. As a private company, SpaceX’s balance sheets are a black box to the public, but it’s safe to say that the it’s going through – or has already gone through – a phase of “production hell” similar to what Tesla experienced when it began building Roadsters, Model S/Xs, and Model 3s.
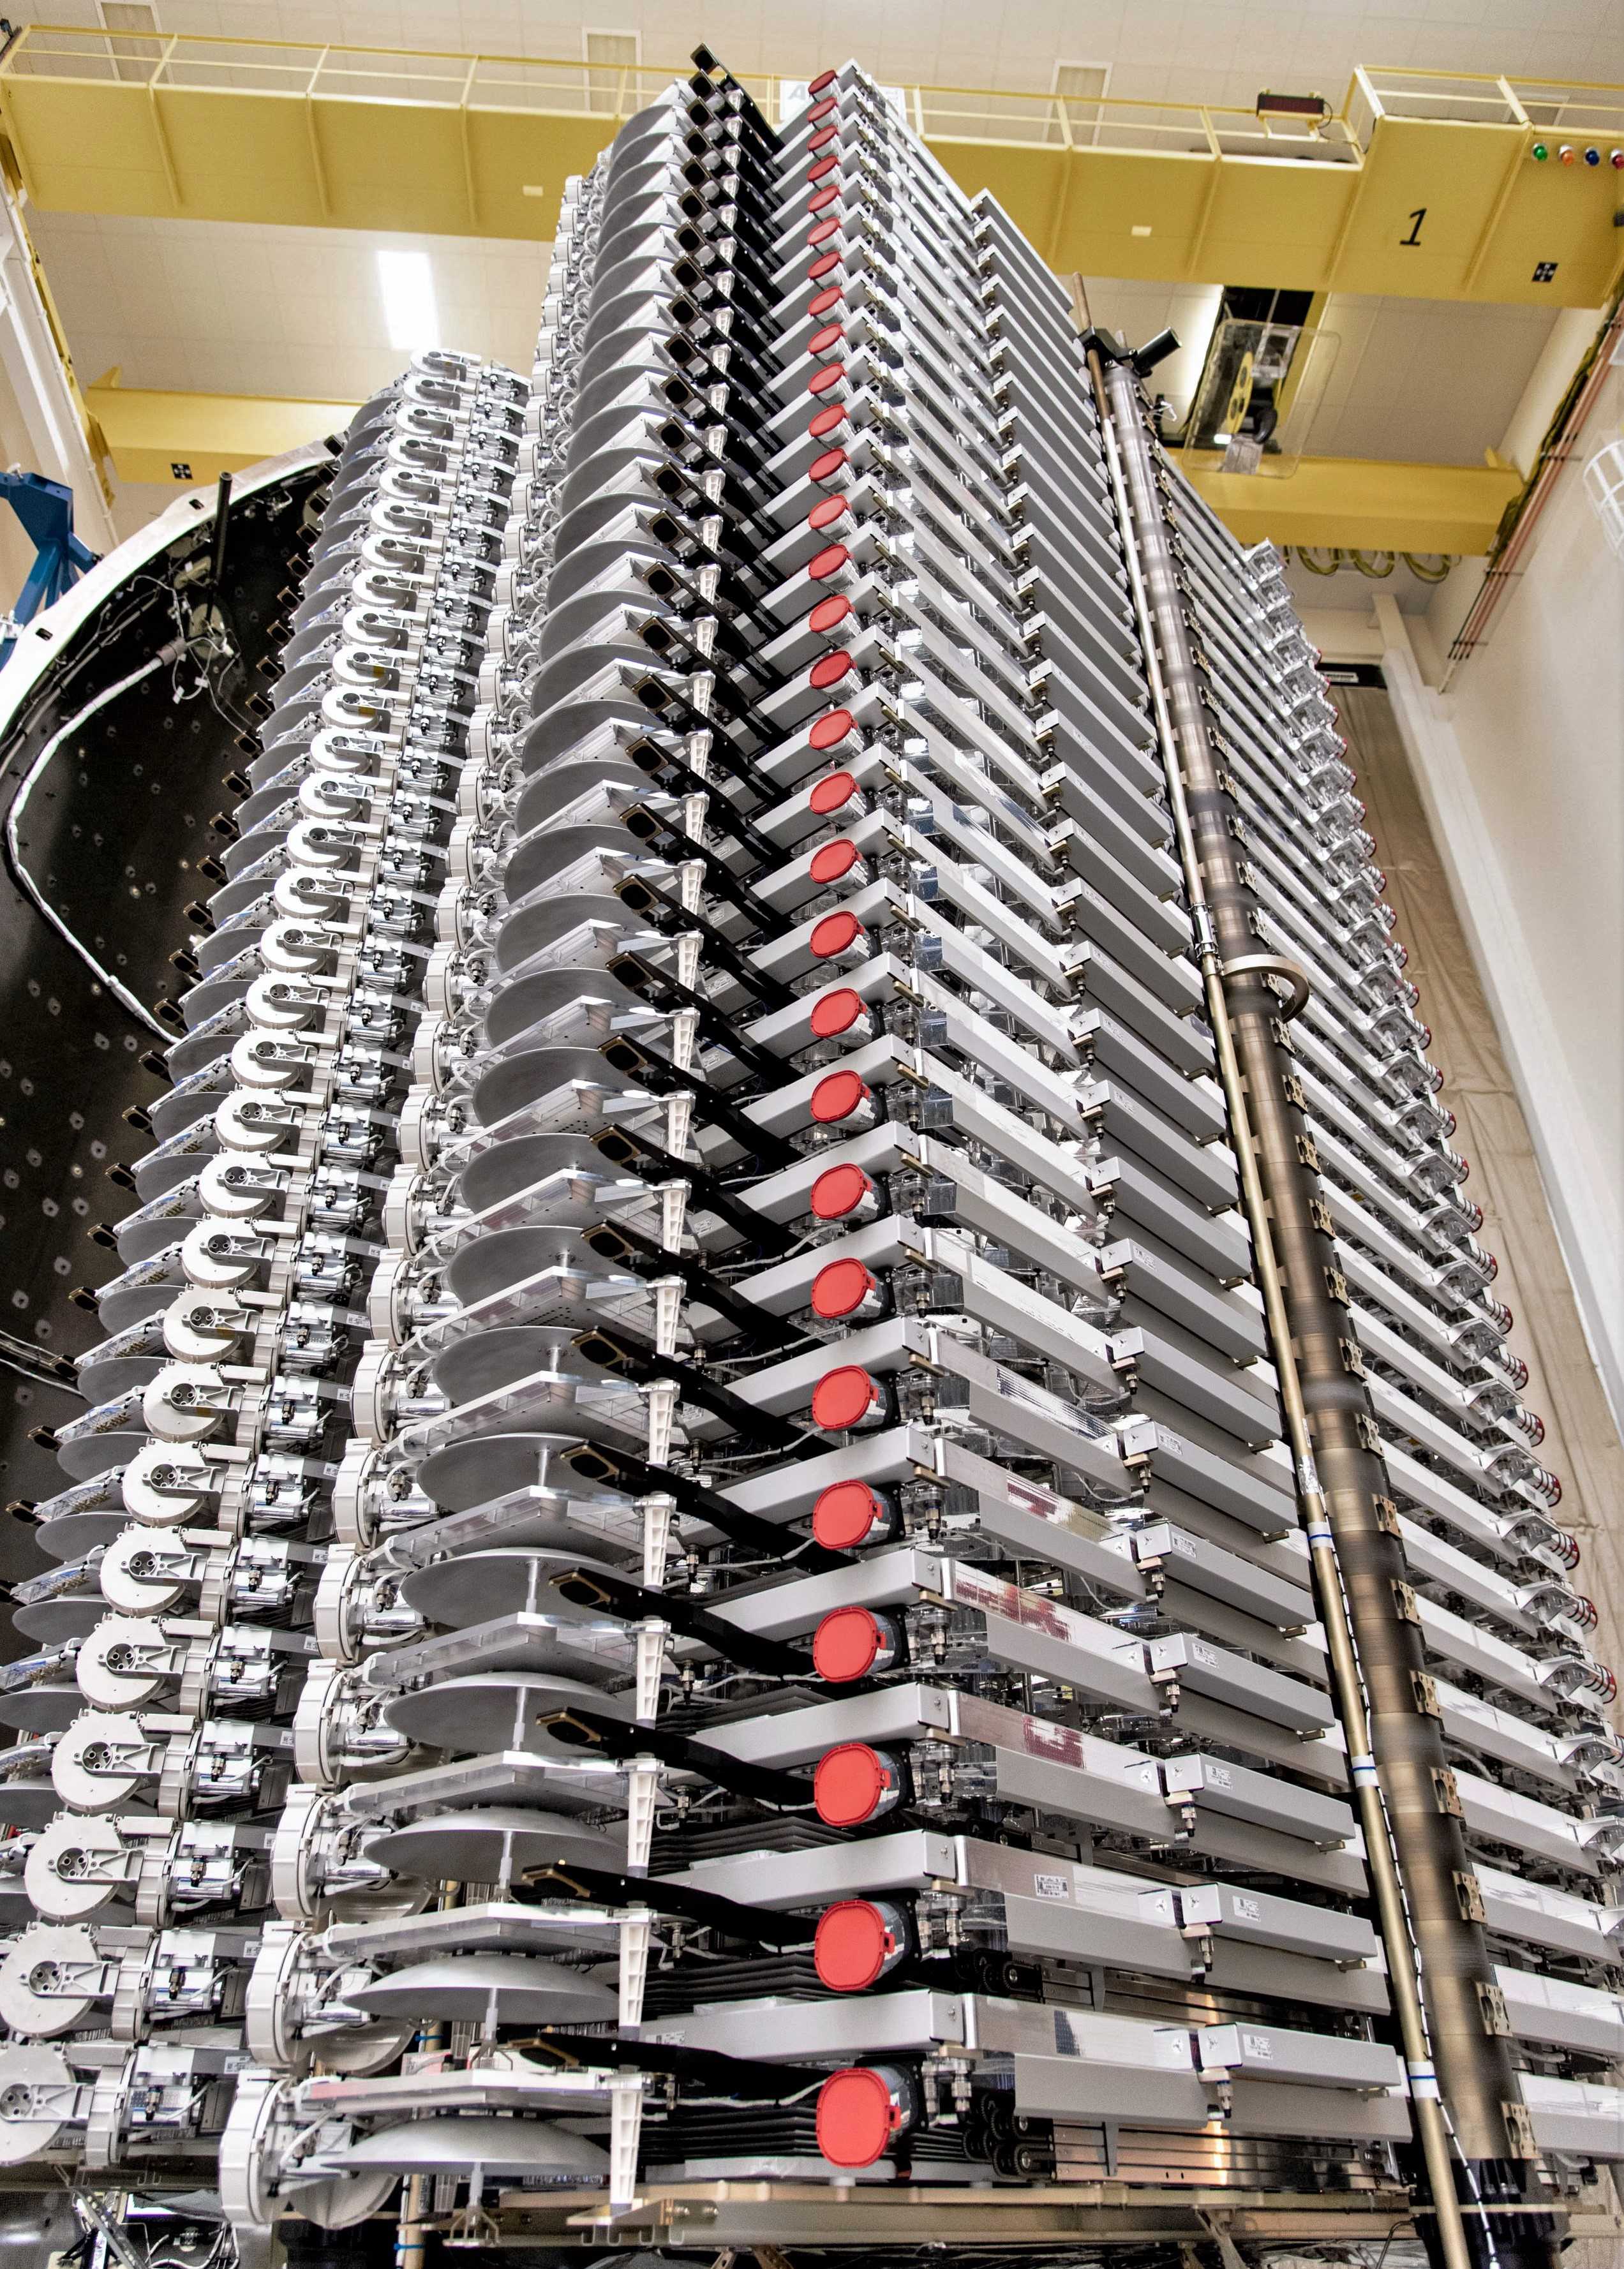
Building satellites like cars
In less than 12 months, SpaceX has effectively gone from manufacturing zero satellites to mass-producing something like 2-4 Starlink spacecraft every single day, almost without a doubt smashing any records previously held in the industry. It’s possible that companies like Planet (now the owner of the second-largest private constellation) or Spire have built more spacecraft in a given period, but SpaceX’s satellites are at least an order of magnitude larger, on average.
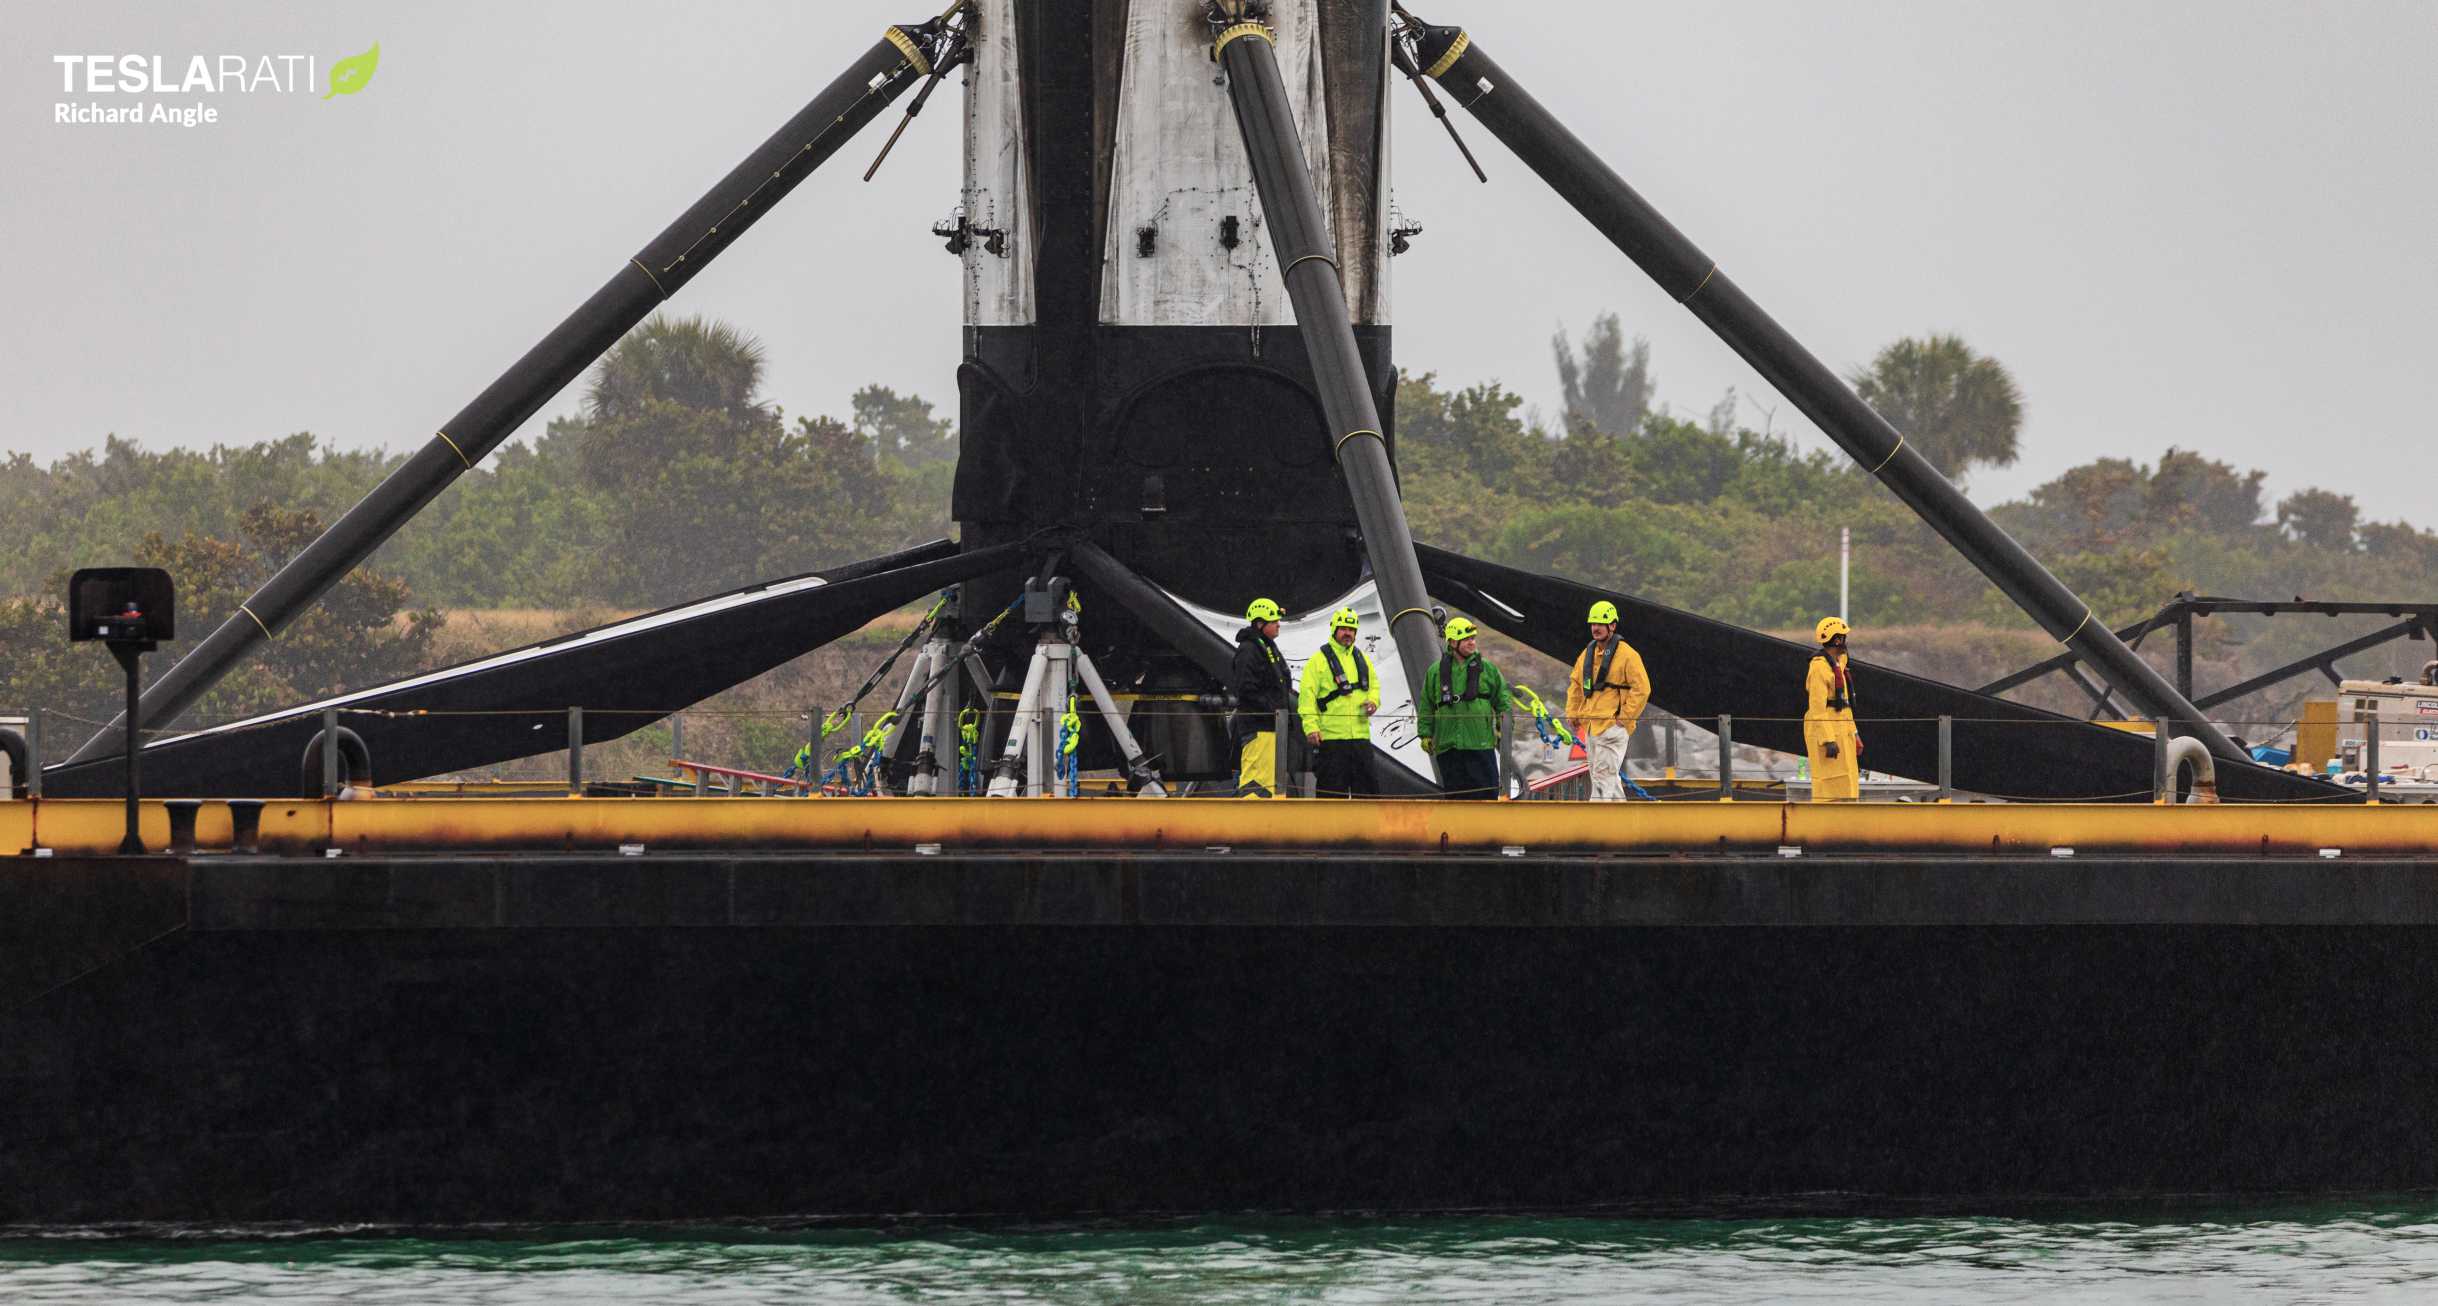
Around 260 kg (570 lb) apiece, SpaceX has built and launched a total of 240 spacecraft – together weighing more than 60 metric tons (135,000 lb) – in less than nine months. Furthermore, the company not only intends to crush that average but wants (if not needs) to do so for several years without interruption.
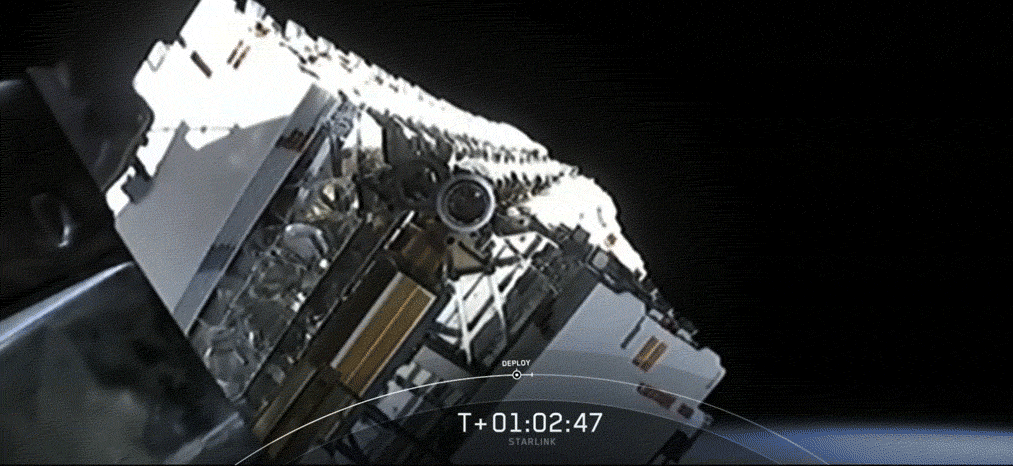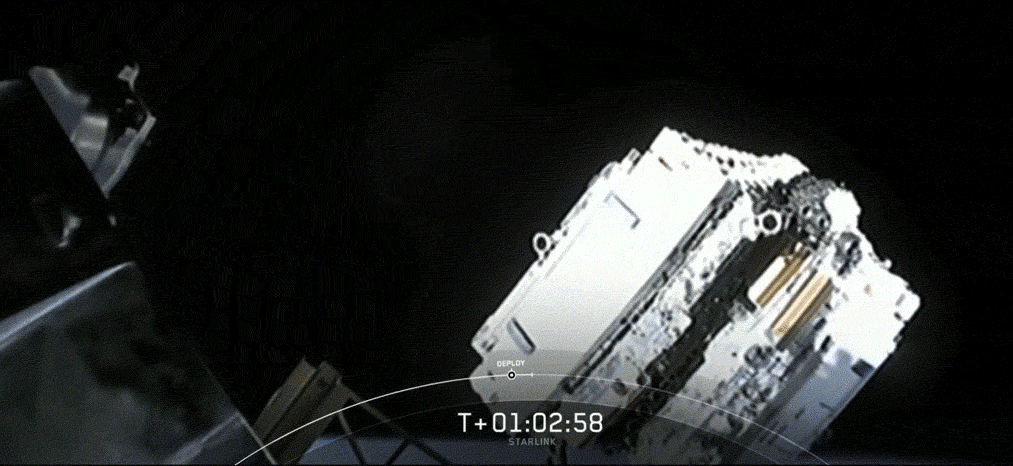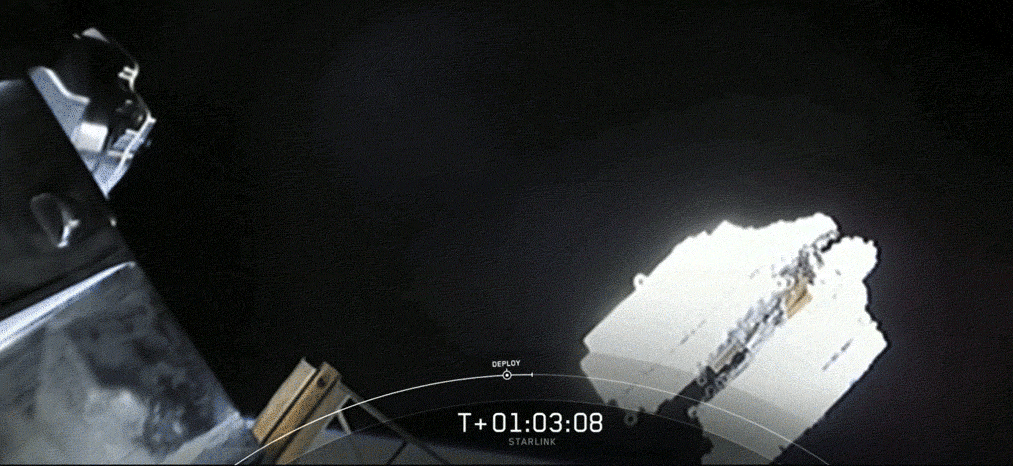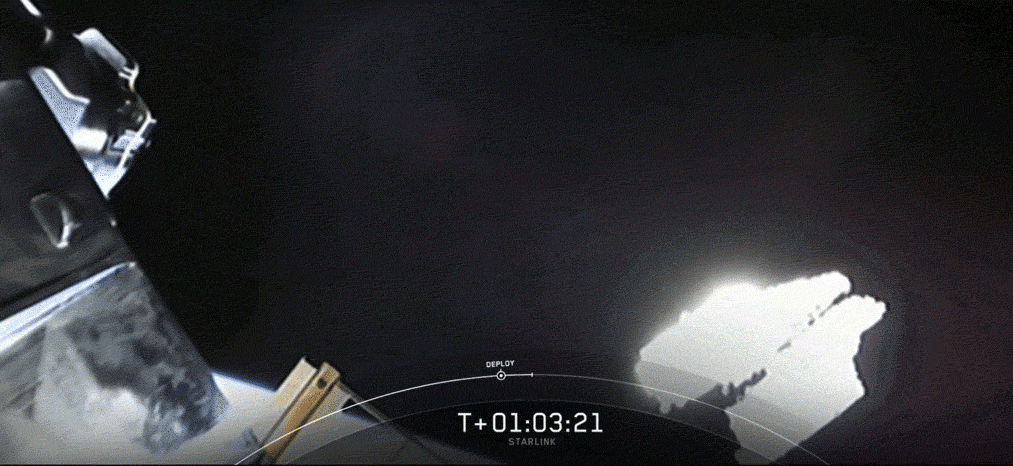
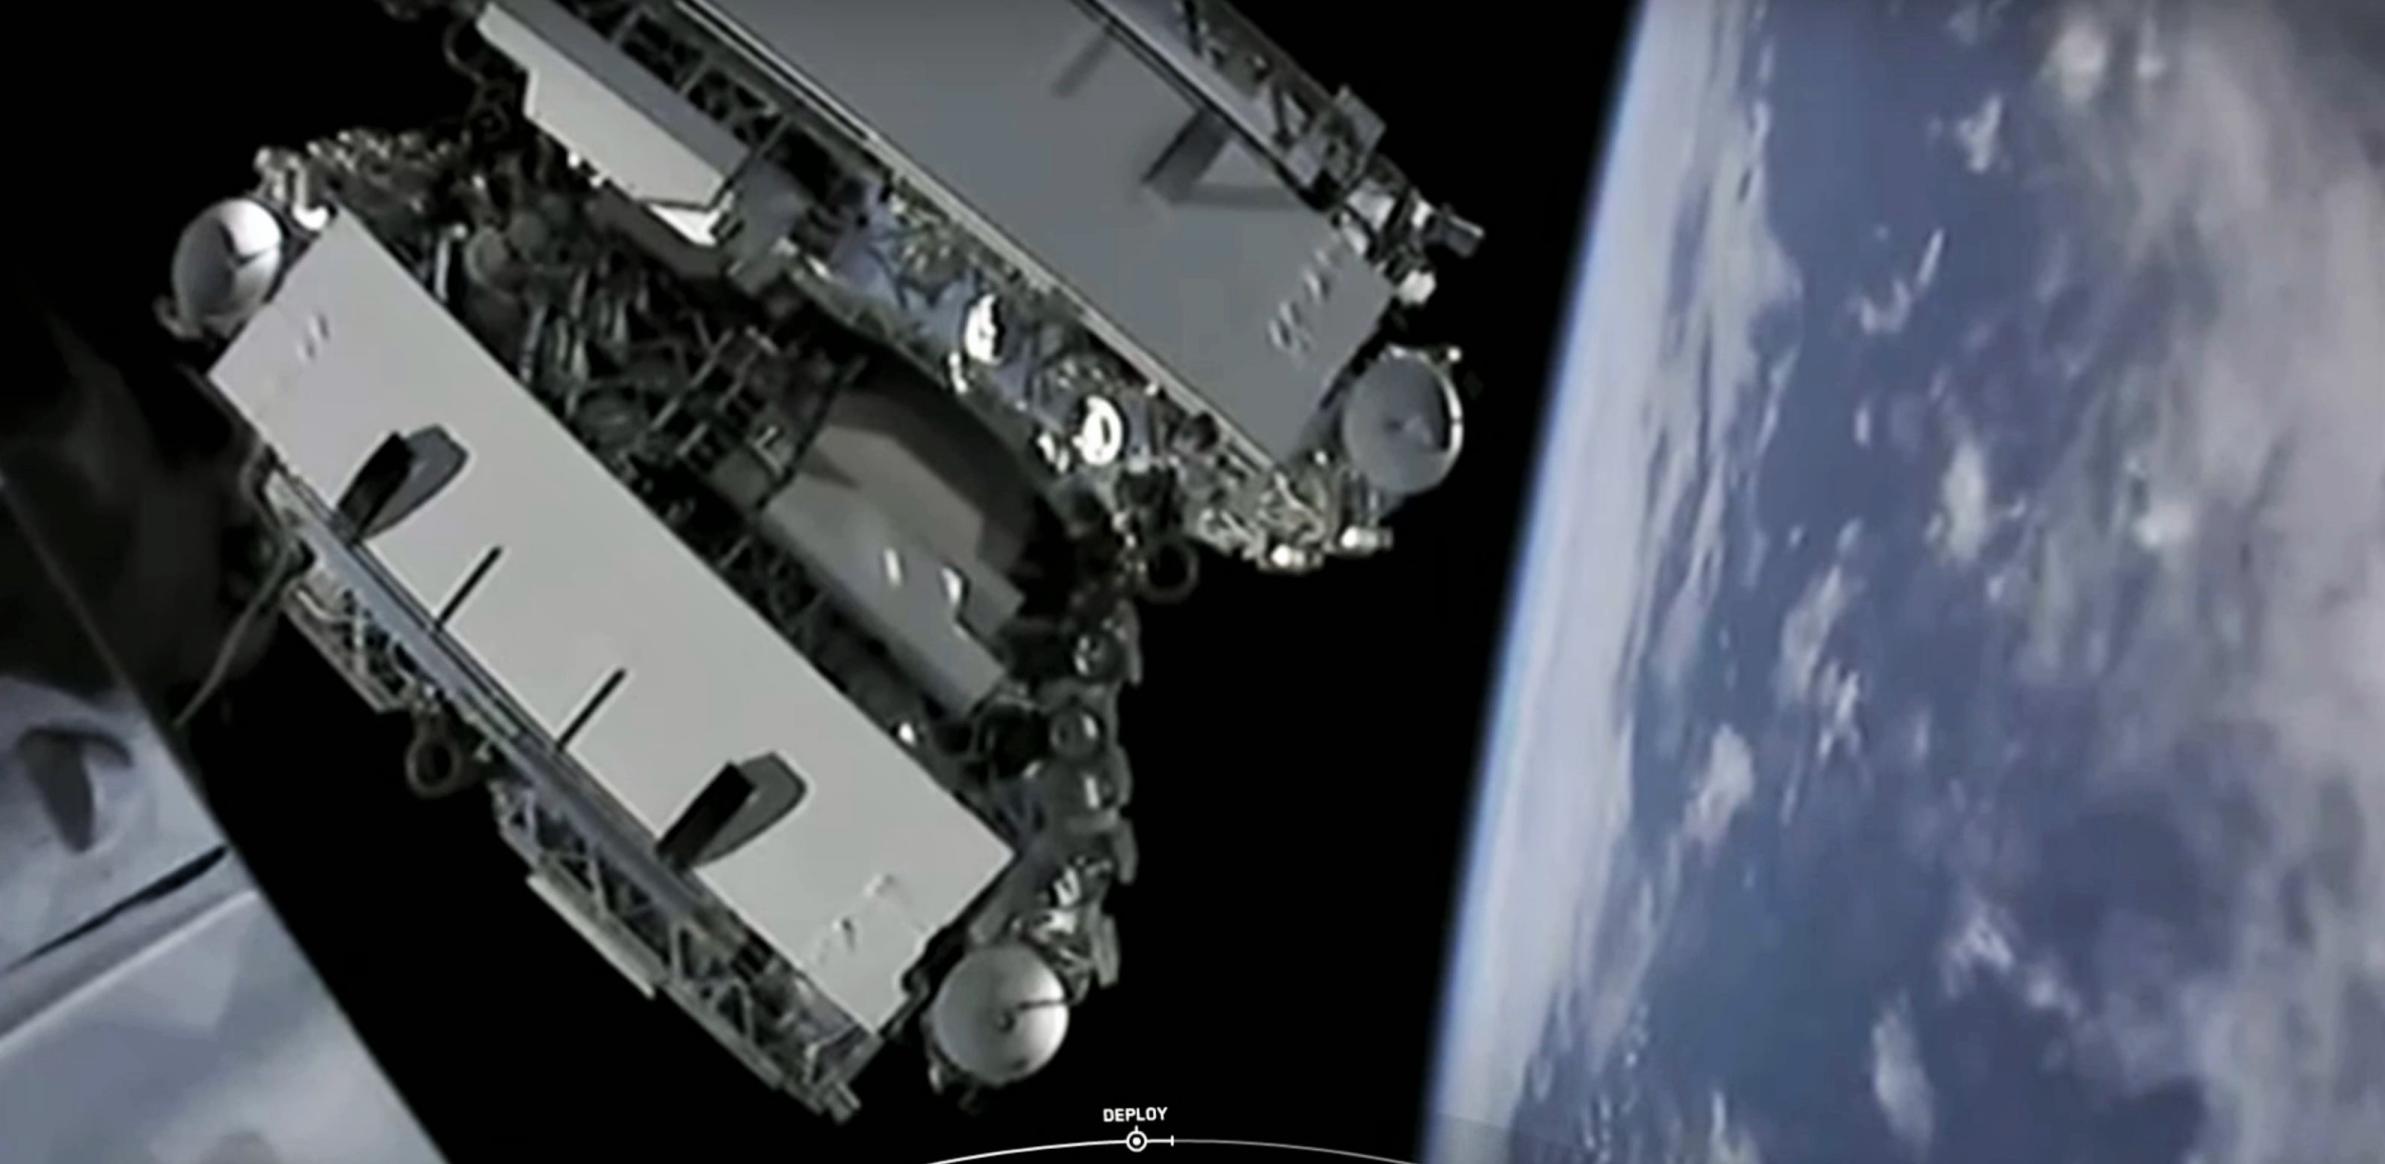
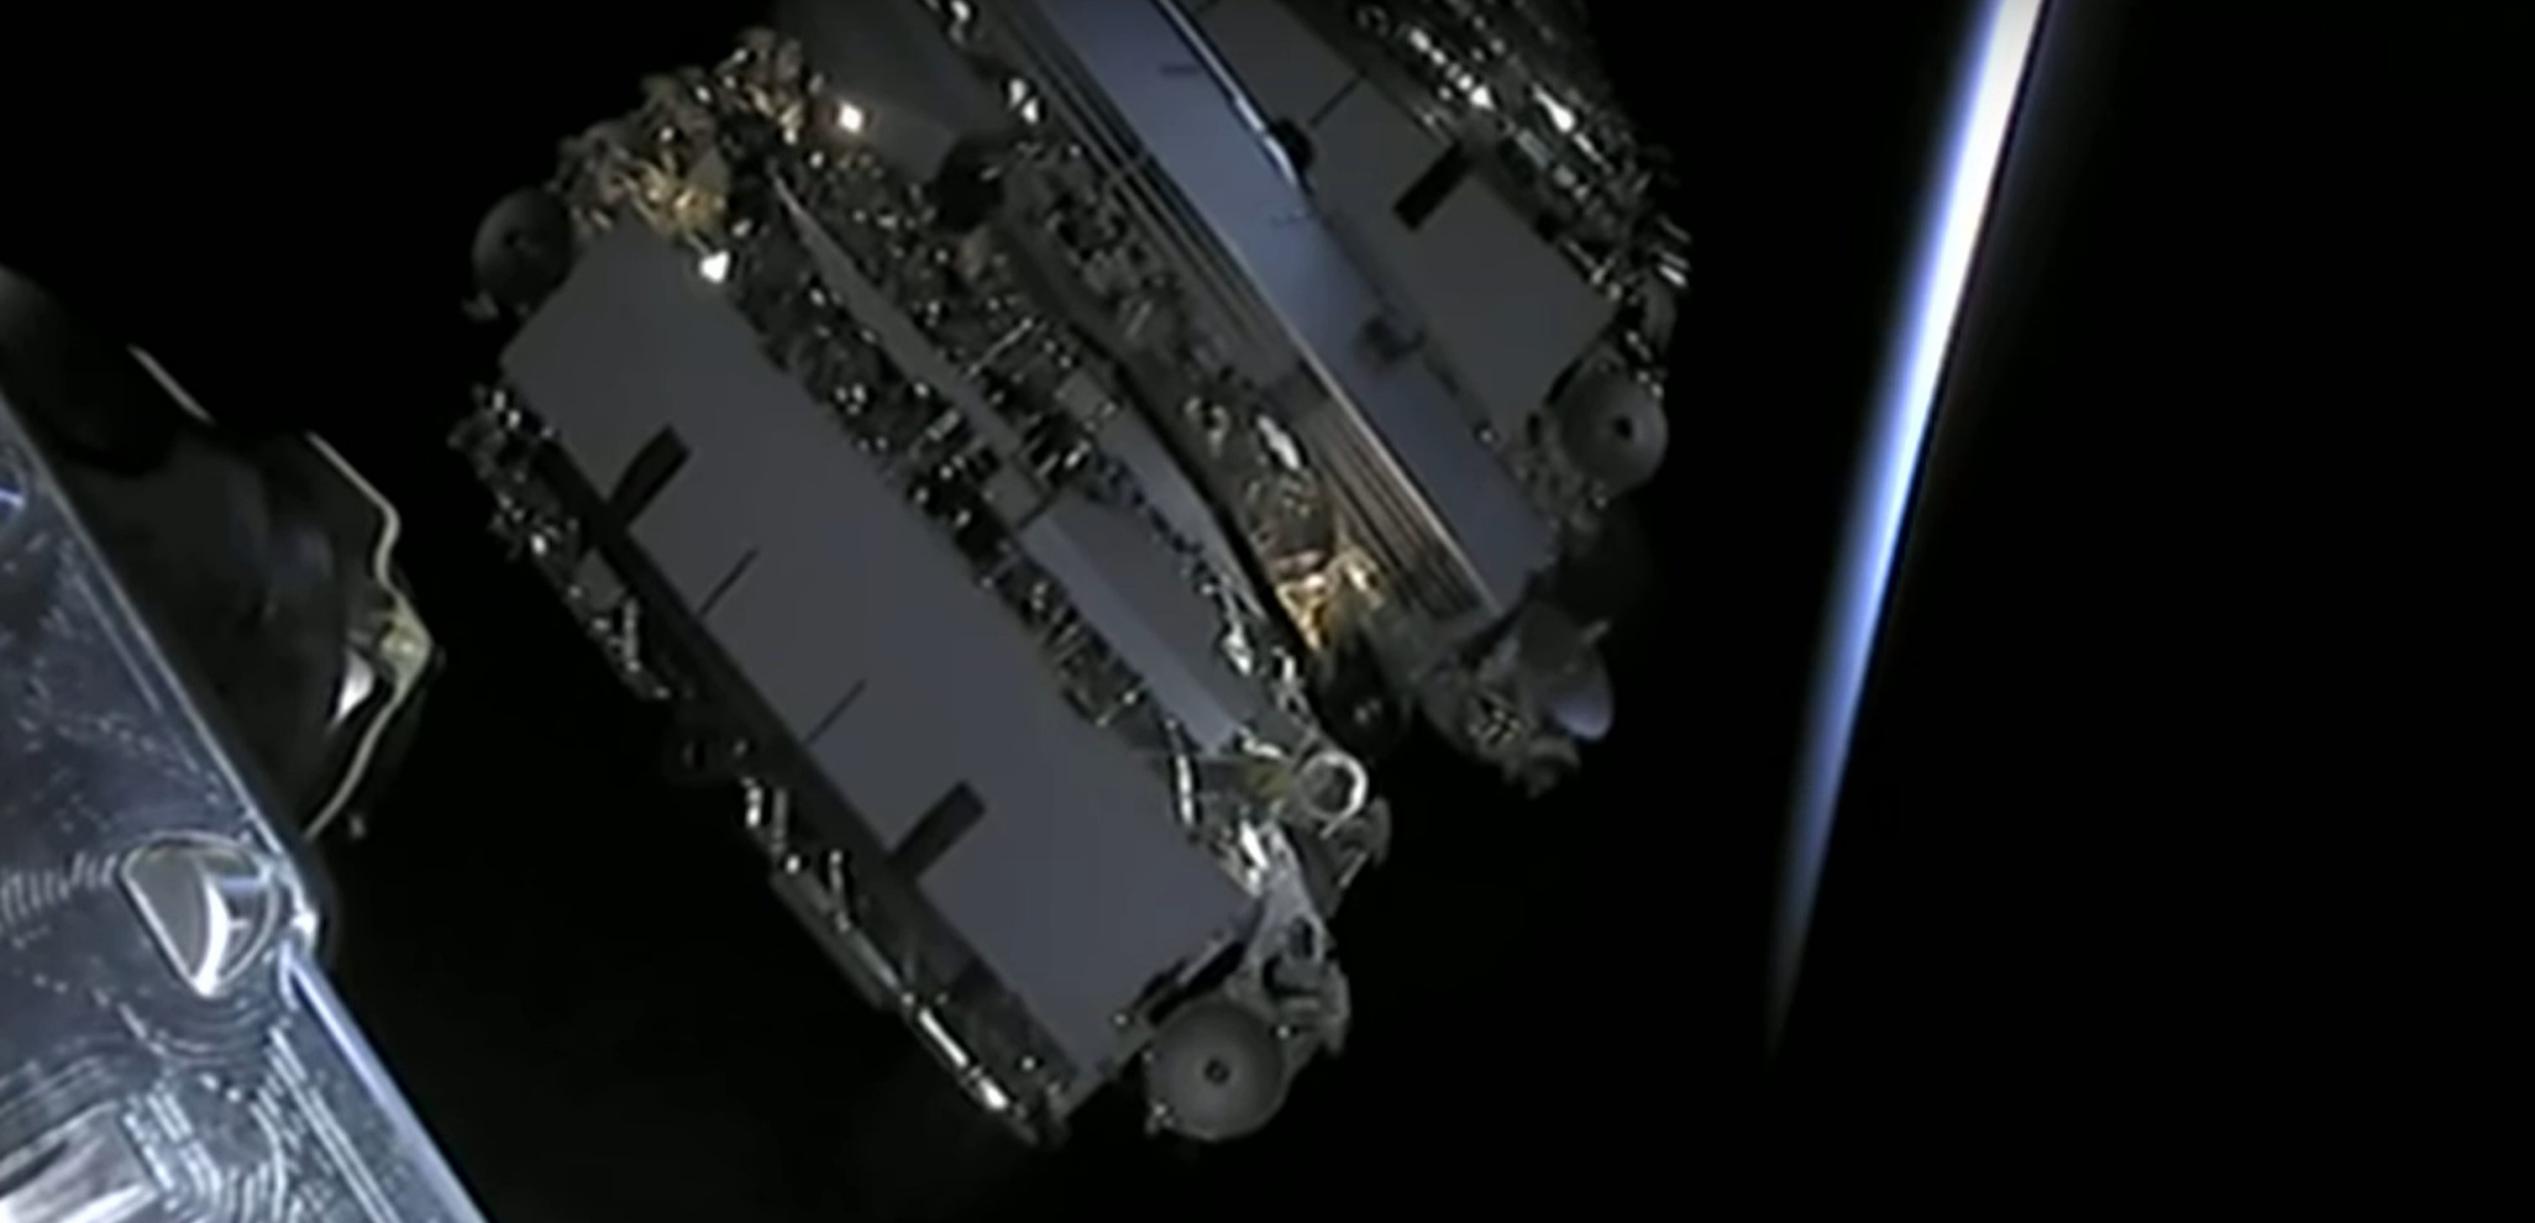
Back in May 2019, CEO Elon Musk confidently stated that he believes SpaceX already has all the capital it needs “to build an operational [Starlink] constellation”, likely referring to at least ~1500 operational communications satellites – launches included. This is why competitors should be moderately terrified that SpaceX isn’t even privately pushing for an IPO sooner than later. Perhaps the single biggest reason modern companies pursue IPOs is to raise substantial capital – usually far more than can be practically (or quickly) raised while private when executed successfully.
A step further, “several years” should mean titanic changes for SpaceX’s Starlink constellation if everything goes as planned. In 2020, SpaceX has publicly stated that it will attempt as many as 20-24 dedicated Starlink launches, an achievement that would translate to a constellation more than 1600 satellites strong by the end of the year. SpaceX says that 24 launches (20 if the first four missions are subtracted) is enough to offer global coverage and plans to begin serving customers in the northern US and Canada as early as this summer.
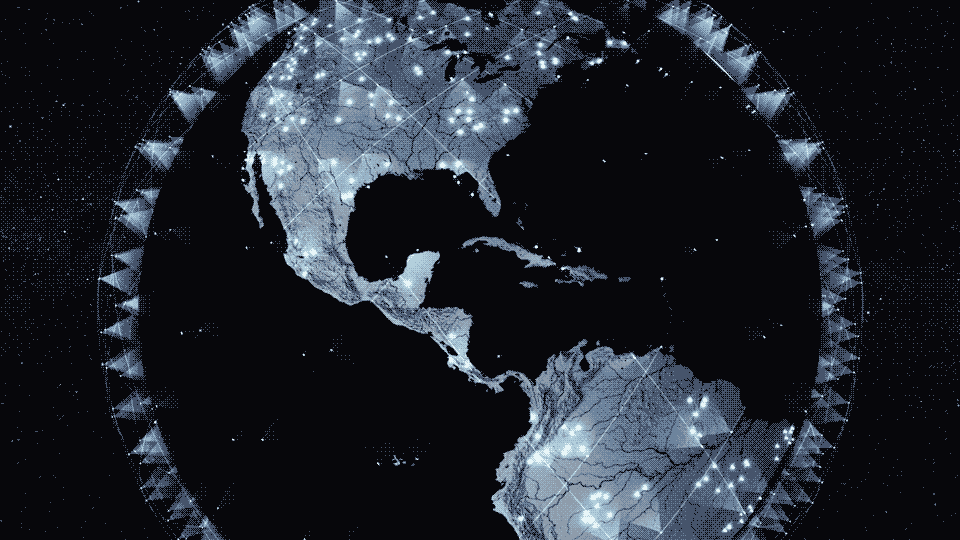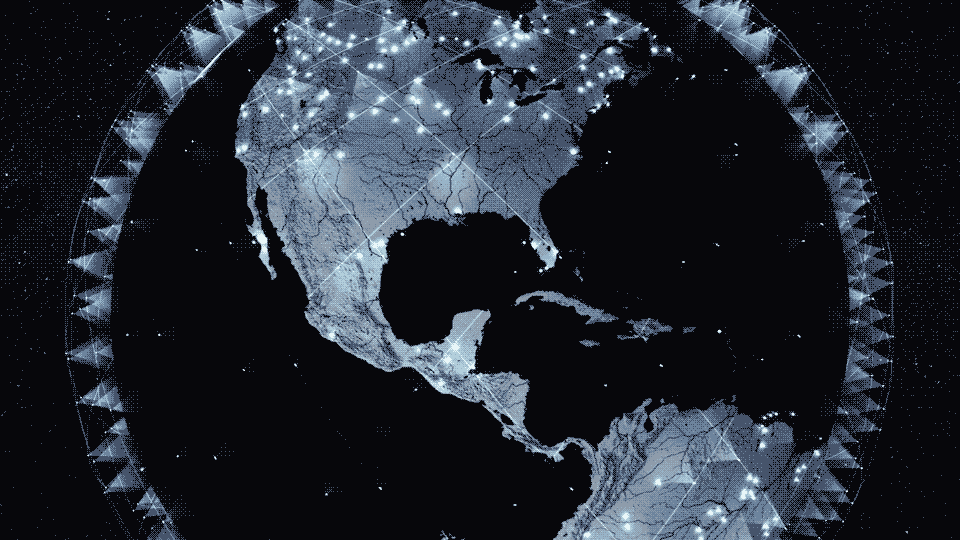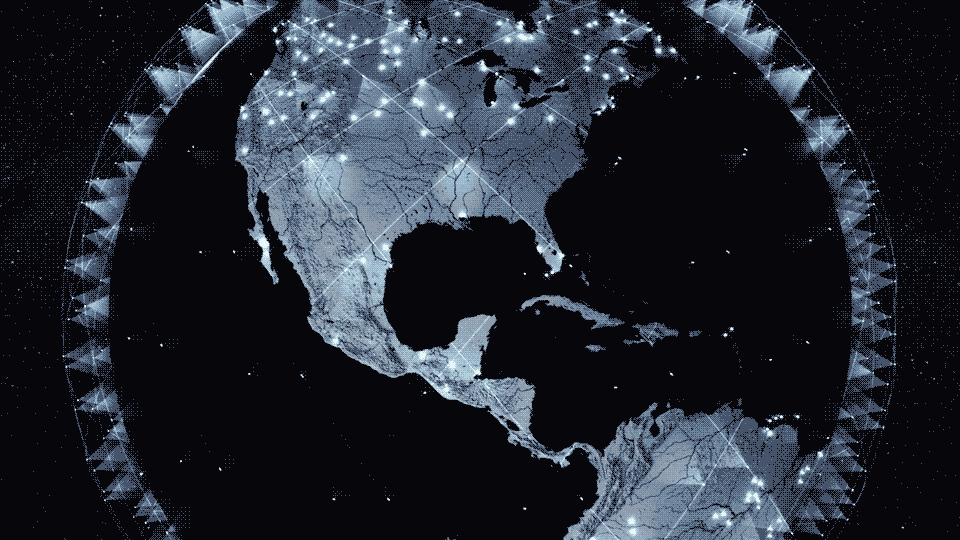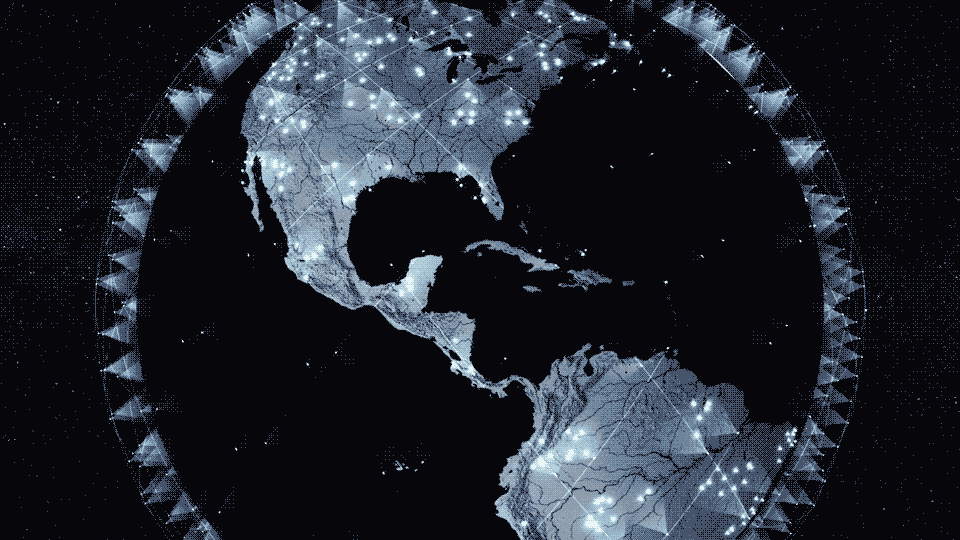
As of now, SpaceX has performed three 60-satellite Starlink launches total in the last three months – two in January 2020 alone – and Starlink V1 L4 (the fourth v1.0 launch and fifth launch overall) is scheduled to lift off just two days from now on February 15th. If Musk and Shotwell are correct and SpaceX can launch at least one or two thousand satellites without raising any additional capital, the constellation – potentially reaching those numbers by early to mid-2021 – may already have hundreds of thousands of customers by the time more funding is needed. 2000 Starlink v1.0 satellites, for reference, would theoretically offer enough collective bandwidth for more than 500,000 users to simultaneously stream Netflix content in 1080p.
As of early 2019, SpaceX had raised a total of $2B in venture capital, investments, and debt. Thus, even in the unlikely event that 100% of that funding goes to Starlink, the company would ultimately have to spend $500-700M annually from 2018 to the end of 2021 to run that large pool of capital dry by the time 1000-2000 satellites are in orbit.
500,000 customers paying $50-100 per month by the end of 2021 would conservatively allow Starlink to generate $300-600M in annual revenue, excluding the likely possibility of even more lucrative government or commercial contracts. In other words, if SpaceX can accumulate an average of 20,000 paying subscribers per month between now and the end of 2021, Starlink could very well become self-sustaining at its current rate of growth – or close to it – by the time SpaceX is hurting for more funding. In a worst-case scenario, it thus appears all but certain that “several years” from now, SpaceX’s Starlink program will have at least a few thousand high-performance satellites in orbit, an extensive network of ground stations, and a large swath of alpha or beta customers by the time IPO proceedings begin.
Given that all that potential infrastructure would easily be worth at least $1-2B purely from a capital investment standpoint, Starlink’s ultimate IPO valuation – under Shotwell’s patient “maybe one day” approach – could be stratospheric.
Check out Teslarati’s Marketplace! We offer Tesla accessories, including for the Tesla Cybertruck and Tesla Model 3.



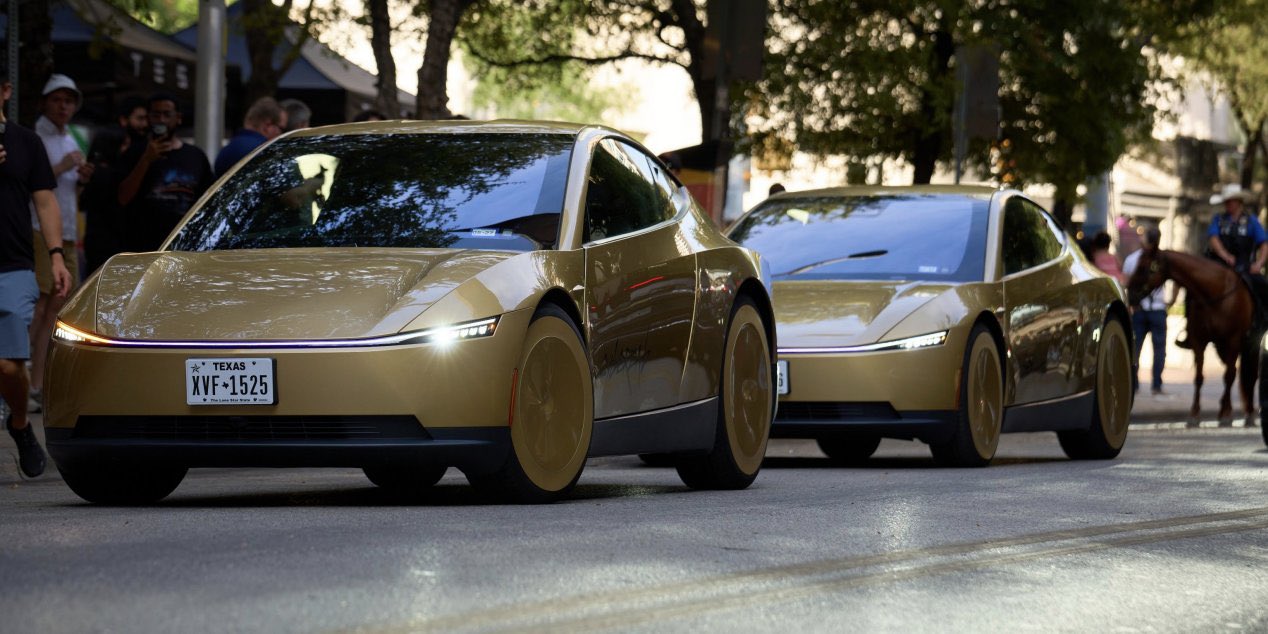
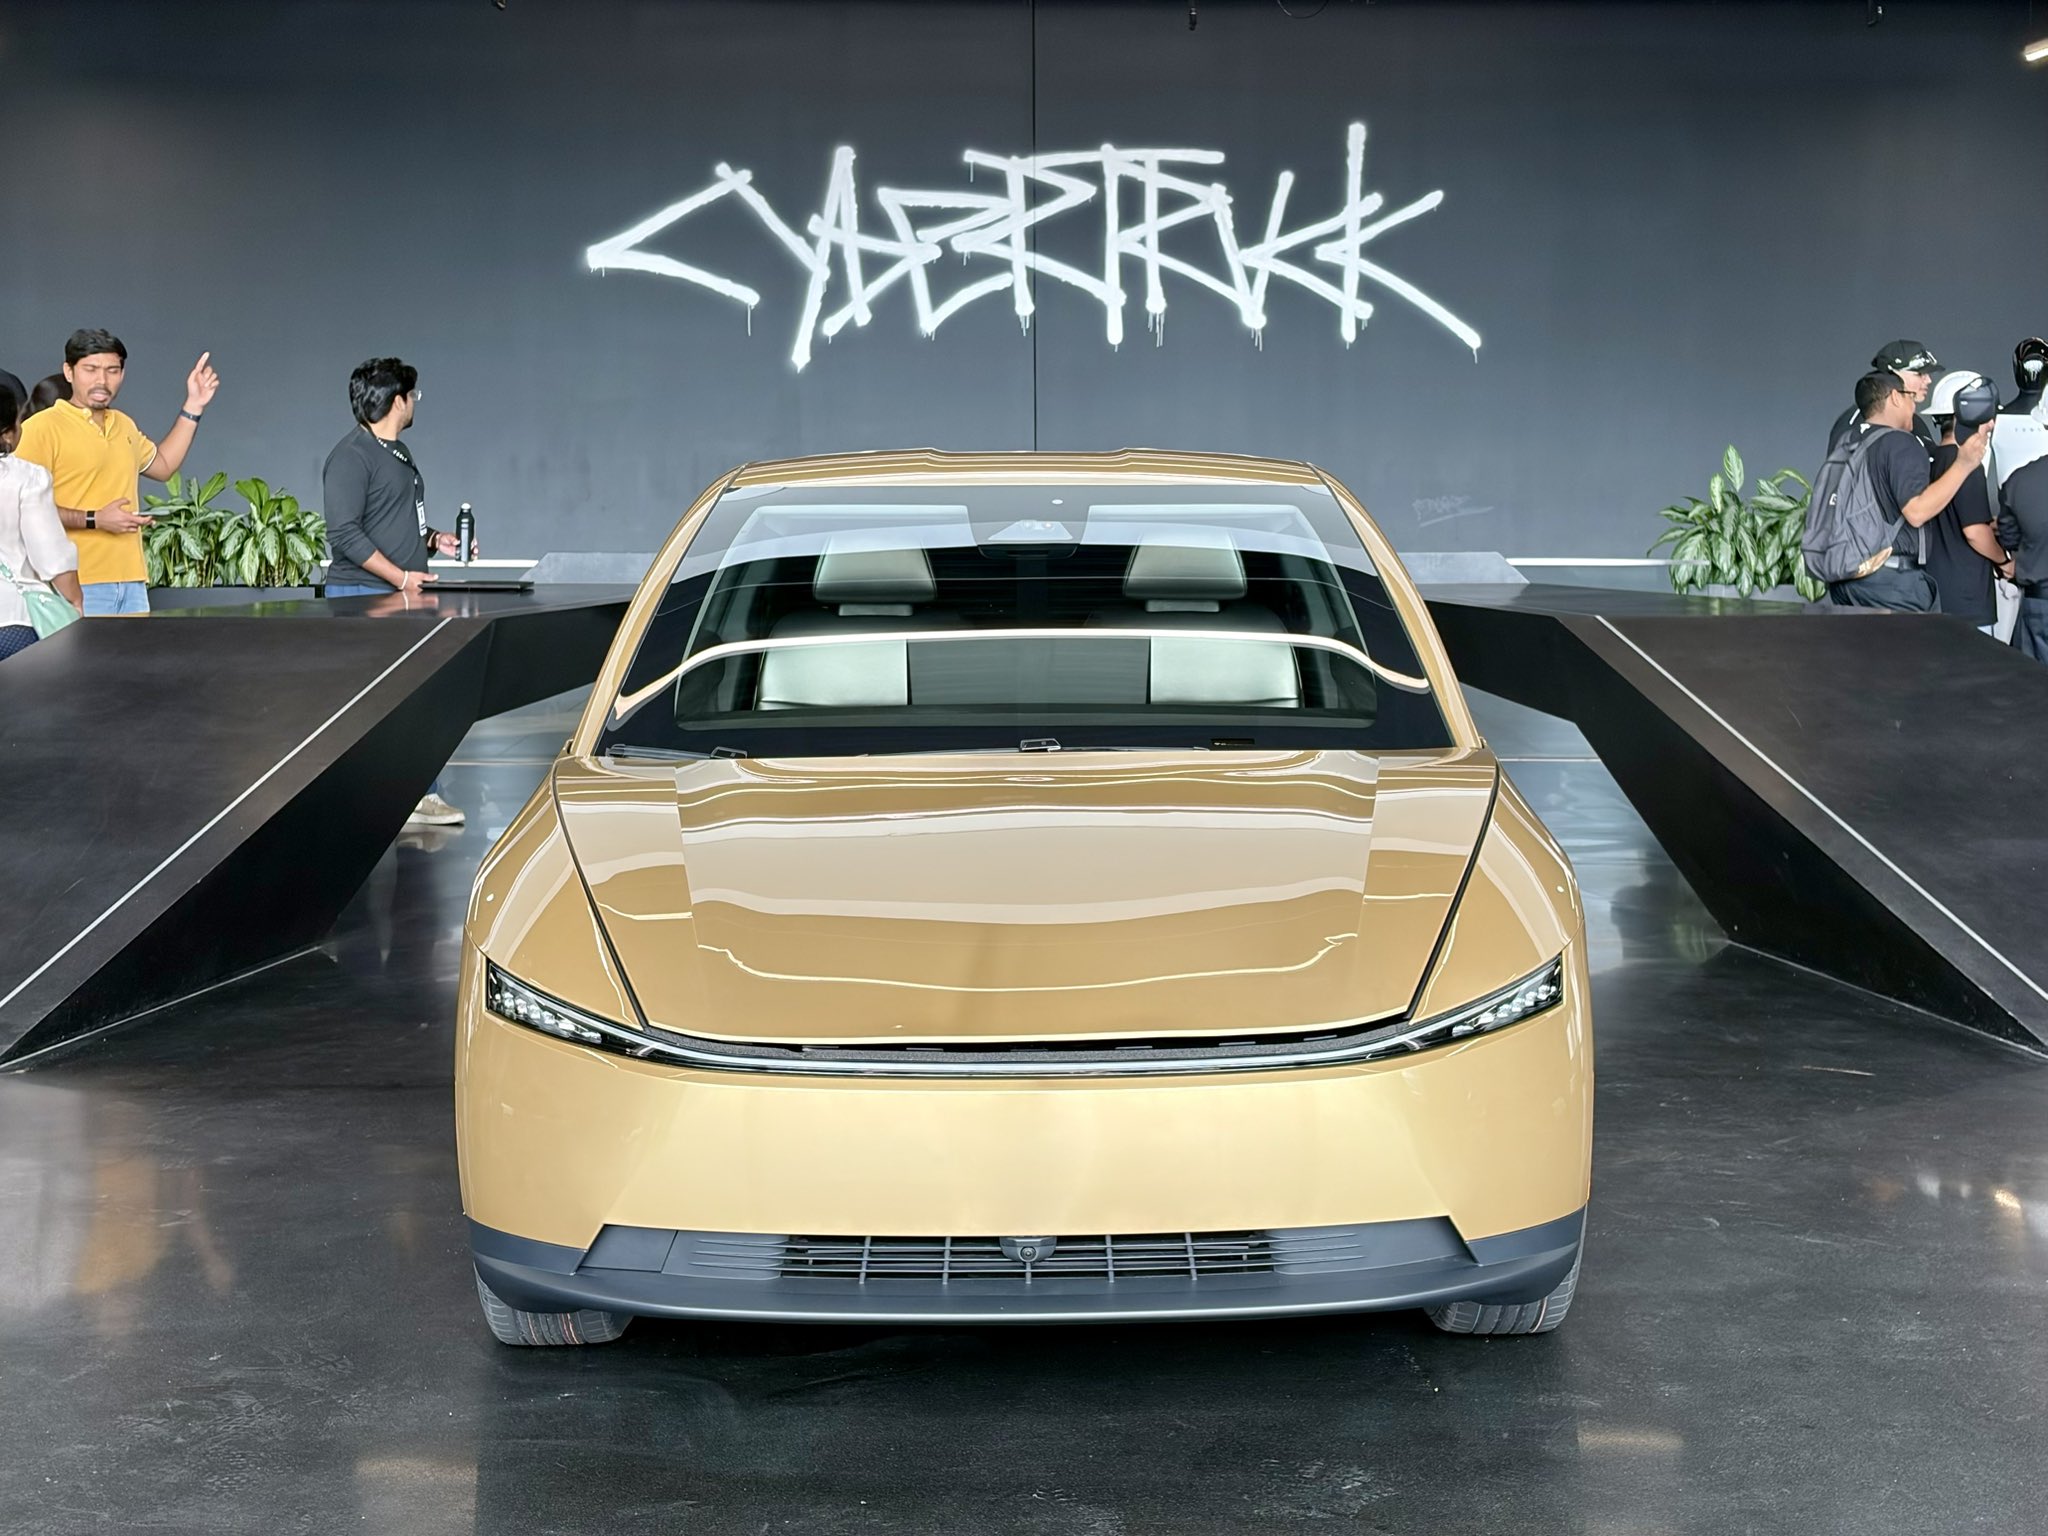
Tesla Cybercab units finally got a definitive date for when they will be able to be purchased by consumers, ending speculation regarding whether the fully autonomous vehicle would be available in the near term.
During Tesla’s third-quarter 2026 earnings call on October 21, Vice President of Engineering Lars Moravy said the company is aiming to begin delivering its purpose-built Cybercab robotaxi to customers before year-end.
🚨 In short, Cybercabs are slated to go to customers by end of the year. All units are going into Robotaxi fleet currently, per @larsmoravy
Cybercab will be “transport-as-a-service,” but vast majority of Cybercab will be “Tesla-owned,” @elonmusk says https://t.co/R8Qu8QWdmp
— TESLARATI (@Teslarati) October 21, 2026
“We’re trying to get Cybercabs to customers by the end of this year, 2026,” Moravy said. He added that production is underway on the line at Gigafactory Texas, but “all of those are currently going to our own internal Robotaxi fleet.”
Moravy explained that as operations scale, Tesla will “mainly deliver fully designed autonomous vehicles to our customers,” with the Cybercab as the first such vehicle. Initial customer deliveries will start small while the company gains experience with delivery logistics, ownership models, fleet management, and operating autonomous vehicles outside its direct control.
CEO Elon Musk reinforced the limited nature of private sales, describing the Cybercab primarily as a “transport-as-a-service” offering rather than a personal ownership vehicle like the Model 3, Model Y, or upcoming Roadster. “The vast majority of the Cybercab stuff will be Tesla-owned and transport-as-a-service,” Musk said.
The Cybercab is a two-seater vehicle developed by Tesla without a steering wheel or pedals. It relies completely on Tesla’s Full Self-Driving suite and has been in production since February. Early units have been put in Tesla’s Robotaxi service as of early September, when the company launched rides to the public. Tesla previously indicated it would aim to sell Cybercabs for about $30,000.
Unsupervised Full Self-Driving is expected to ship to consumer cars during Q2 2027, Ashok Elluswamy, Tesla’s Head of AI, indicated during the call. Early buyers or fleet operators may receive vehicles whose autonomous operation remains geographically restricted due to lagging regulatory agencies. There are some hurdles that remain ahead of Cybercab deliveries.
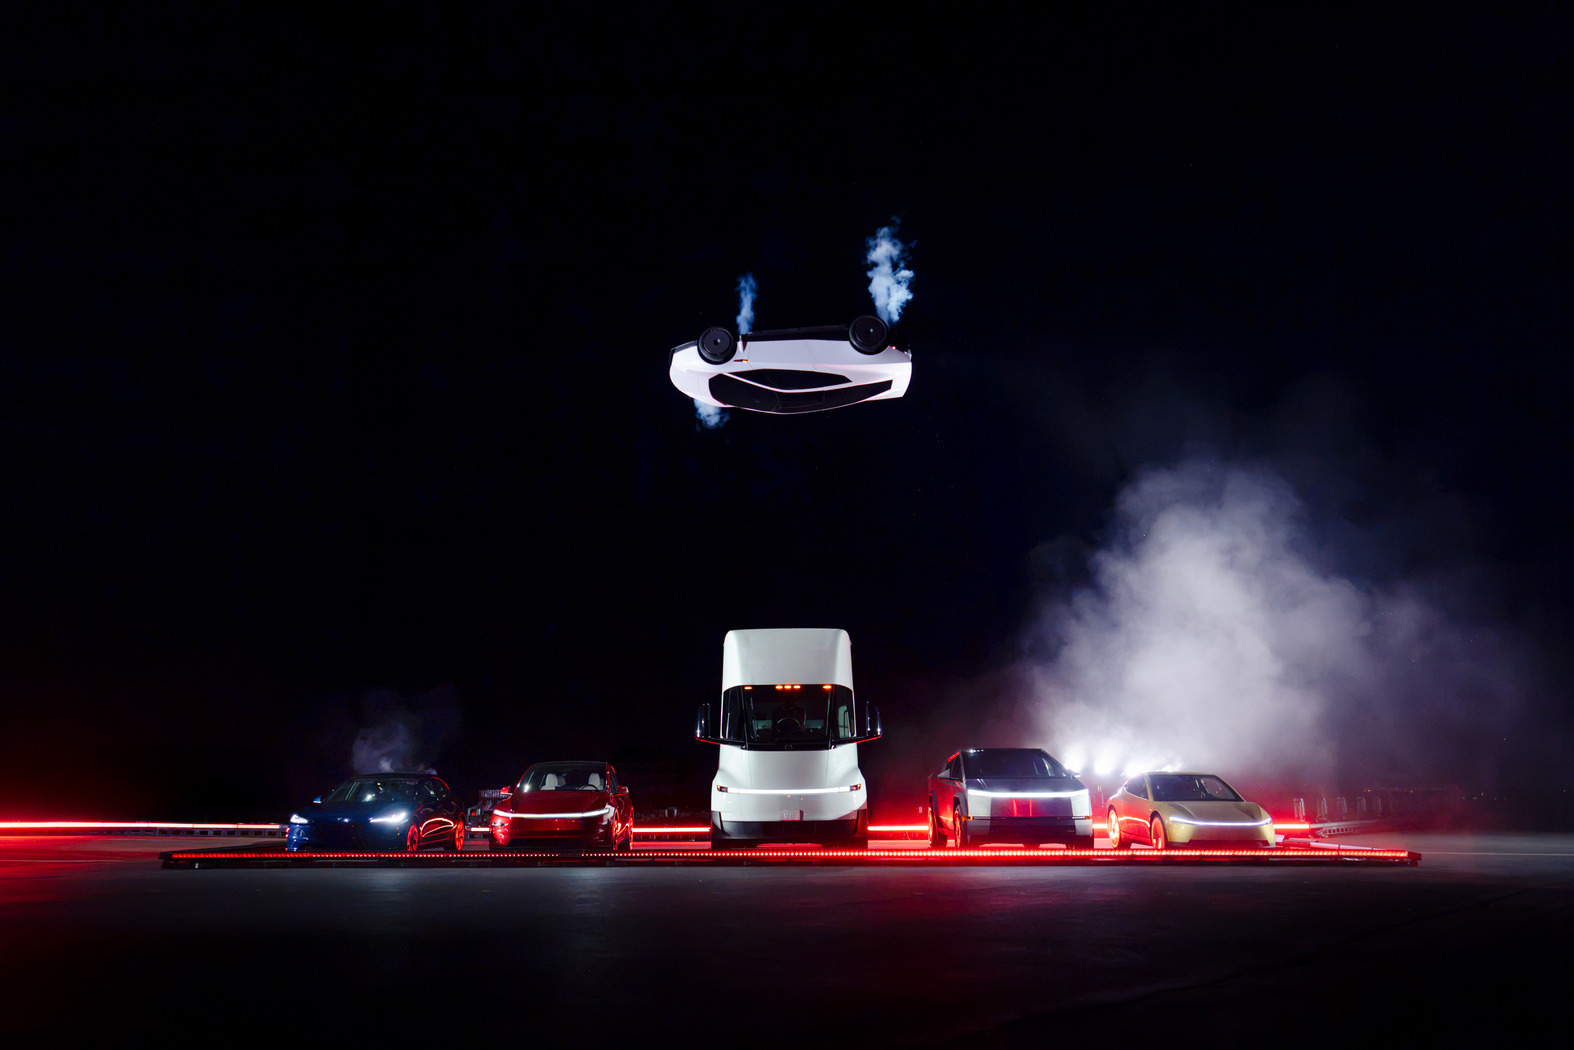
Tesla (NASDAQ: TSLA) reported its earnings for the third quarter of 2026, marking a reasonable performance on the various financial metrics. Tesla still plans to hold a call that will field investor questions at 5:30 p.m. ET, 4:30 p.m. CT.
Here’s where Earnings came in:
- Total Revenues: $28.046 reported vs. $28.34B expected
- Non-GAAP EPS: $0.48 reported vs. $0.45 expected
- Operating Margin: 2.6 % reported vs. 2.5% expected
- Operating Income: $718M reported vs. $721M expected
- Free Cash Flow: $1.531B reported vs. ~-$4.51B expected
Tesla $TSLA Earnings Results:
Revenues: $28.046B
Non-GAAP EPS: $0.48
Operating Margin: 2.6%
Operating Income: $718M
FCF: $1.531B— TESLARATI (@Teslarati) October 21, 2026
Major Takeaways
Full Self-Driving (Supervised)
“FSD (Supervised)⁴ attach rate continued to grow, reaching over 75% of new vehicle deliveries in North America – our most mature market – a nearly twenty percentage point sequential increase. We believe that FSD is driving demand in markets where it is available, and we continue to work with regulators to get it approved in other markets.”
Tesla Semi
“We began volume production of Tesla Semi, our Class 8 heavy-duty truck. The top variant can go 500 miles at full 82,000 lbs gross combination weight while achieving an efficiency of 1.7 kWh/mile. That efficiency allows the Tesla Semi to use a third of the energy used by a comparable diesel truck to haul the same payload. In a transportation market where energy is one of the largest components of total cost per mile, this will provide a meaningful advantage to Tesla Semi operators.”
SI Compute
“We plan to reach 400 MW of SI training compute by the end of the year, supporting the development of both vehicle and humanoid robot autonomy software. Additionally, we continued construction for the Austin Fab, where we plan to start commissioning equipment in 2027.”
Robotaxi
“We began deployment of Cybercab into our Robotaxi fleet in Austin. We reached nearly two million cumulative unsupervised miles for our Robotaxi service as of the end of the quarter. Operating hours in Austin are now 6am to midnight, and we expect to reduce wait times via increased fleet supply and improvement of Robotaxi orchestration algorithms. Grok is available in Cybercab with access to Grok Bot and Connectors, which allows users to manage their inbox, calendars, files, chats and tasks – all hands free via voice command – making Cybercab a mode of transport, a productivity space and, with our entertainment options, a second living room.”
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.

Tesla Cybercab gets a for sale date at last

Tesla Q3 2026 Earnings results: in-line revenues, slight beat on EPS


