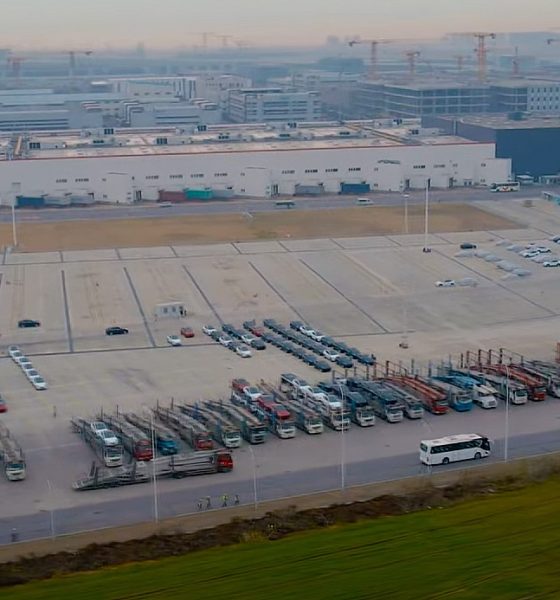

Tesla Giga Shanghai is resuming production at high-speed and preparing to ship cars to customers as the plant is being stormed by delivery trucks and haulers.
Rumors of production stoppages at Giga Shanghai circulated late last year, which caught many off guard with Tesla’s typical end-of-year production and delivery pushes. The automaker clarified the “stoppages,” indicating it was carrying out annual production line maintenance. Workers were able to rest while this maintenance was performed.
Following the line upgrades and optimizations, Tesla is resuming production at full speed, according to a new video from drone operator Wu Wa, who has followed Giga Shanghai’s progress for several years.
Evidently, Tesla is ramping up manufacturing and production to resume normal levels before it takes a reportedly scheduled hiatus for the Chinese New Year from January 20 to January 31. Giga Shanghai will be operational from January 3 to January 19, according to a report. Tesla has not confirmed these dates.
Tesla is planning to take full advantage of the operational days in January, and it is evident from Wu Wa‘s new video. While the plant is buzzing with activity as workers being manufacturing Model 3 and Model Y all-electric vehicles, what was more striking was the number of vehicle haulers placed outside the factory, awaiting completed vehicles to be loaded so they can be driven to their destination. As a drone operator at the Giga Shanghai plant since 2019, Wu Wa made interesting comments about the number of haulers present on the factory’s campus:
“I was impressed by the line of haulers waiting to enter the factory outside and the neatly arranged haulers in the factory parking area. I counted about 45 haulers parked on site, the most I’ve seen so far, and it was clear that Tesla has picked up the pace of logistics.”
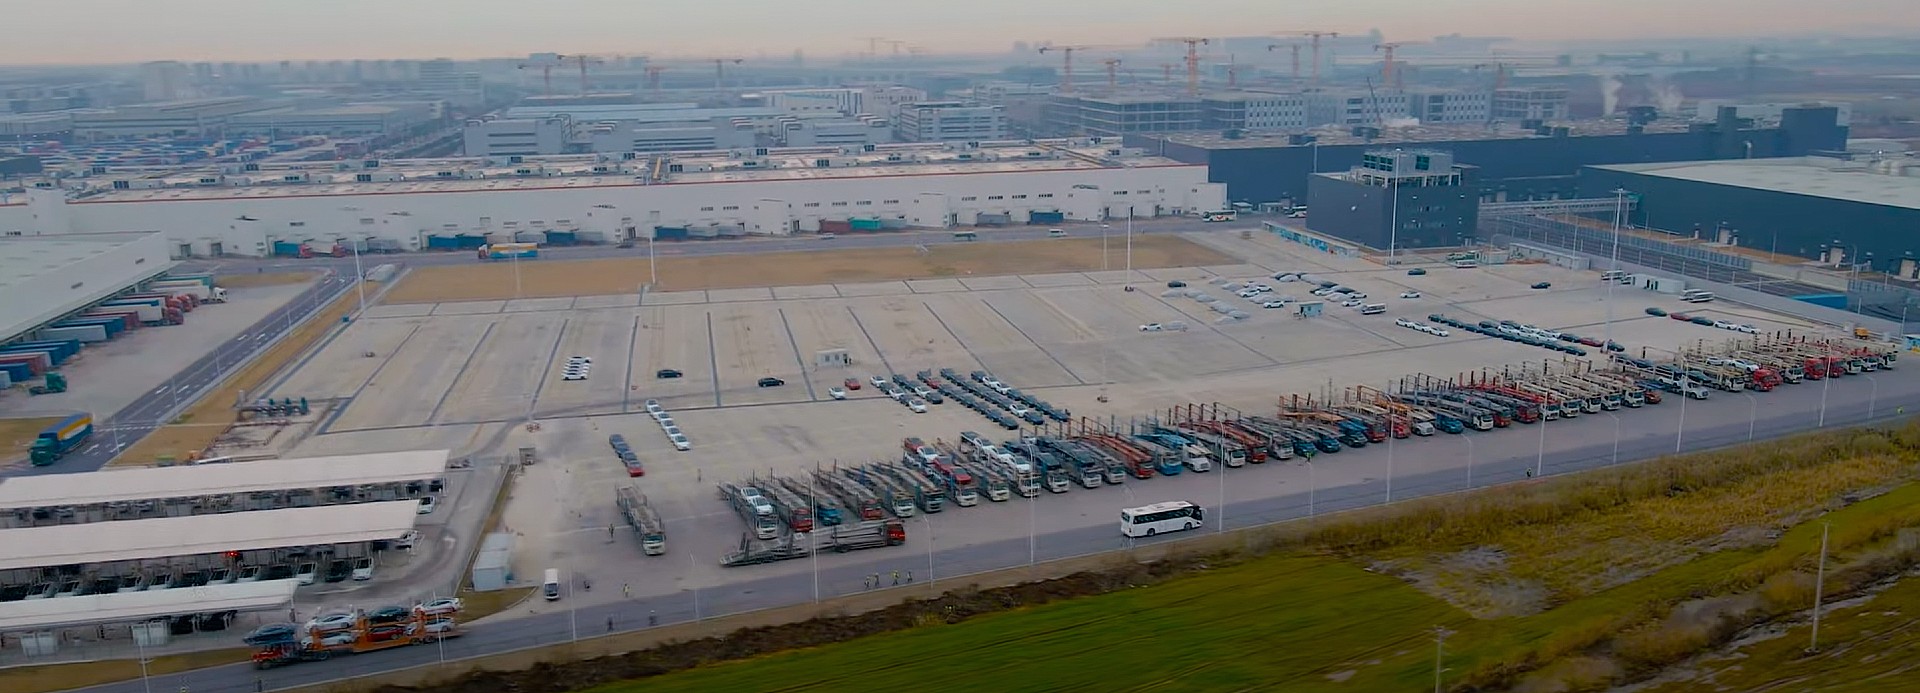
Credit: Wu Wa | YouTube
Giga Shanghai does not only provide Tesla vehicles for Chinese customers. The company has routinely used the plant as an output hub for several years, feeding Model 3 units to the European market, among others.
Although Tesla Giga Shanghai’s Q4 figures were strong, the automaker suffered a decrease in wholesale units in December. Tesla China sold just 55,796 vehicles to either domestic or foreign customers, a 44 percent decrease compared to November 2022.
Tesla will be looking for another solid year from Giga Shanghai and will be looked at as a supplemental piece to sales in Europe. The automaker experienced a step up in competition in the Chinese market in 2022, and with China boss Tom Zhu accepting a higher role within Europe and the United States, it will be an interesting year for the automaker’s Chinese plant.
https://www.youtube.com/watch?v=2kCt8M_lYYc
I’d love to hear from you! If you have any comments, concerns, or questions, please email me at joey@teslarati.com. You can also reach me on Twitter @KlenderJoey, or if you have news tips, you can email us at tips@teslarati.com.


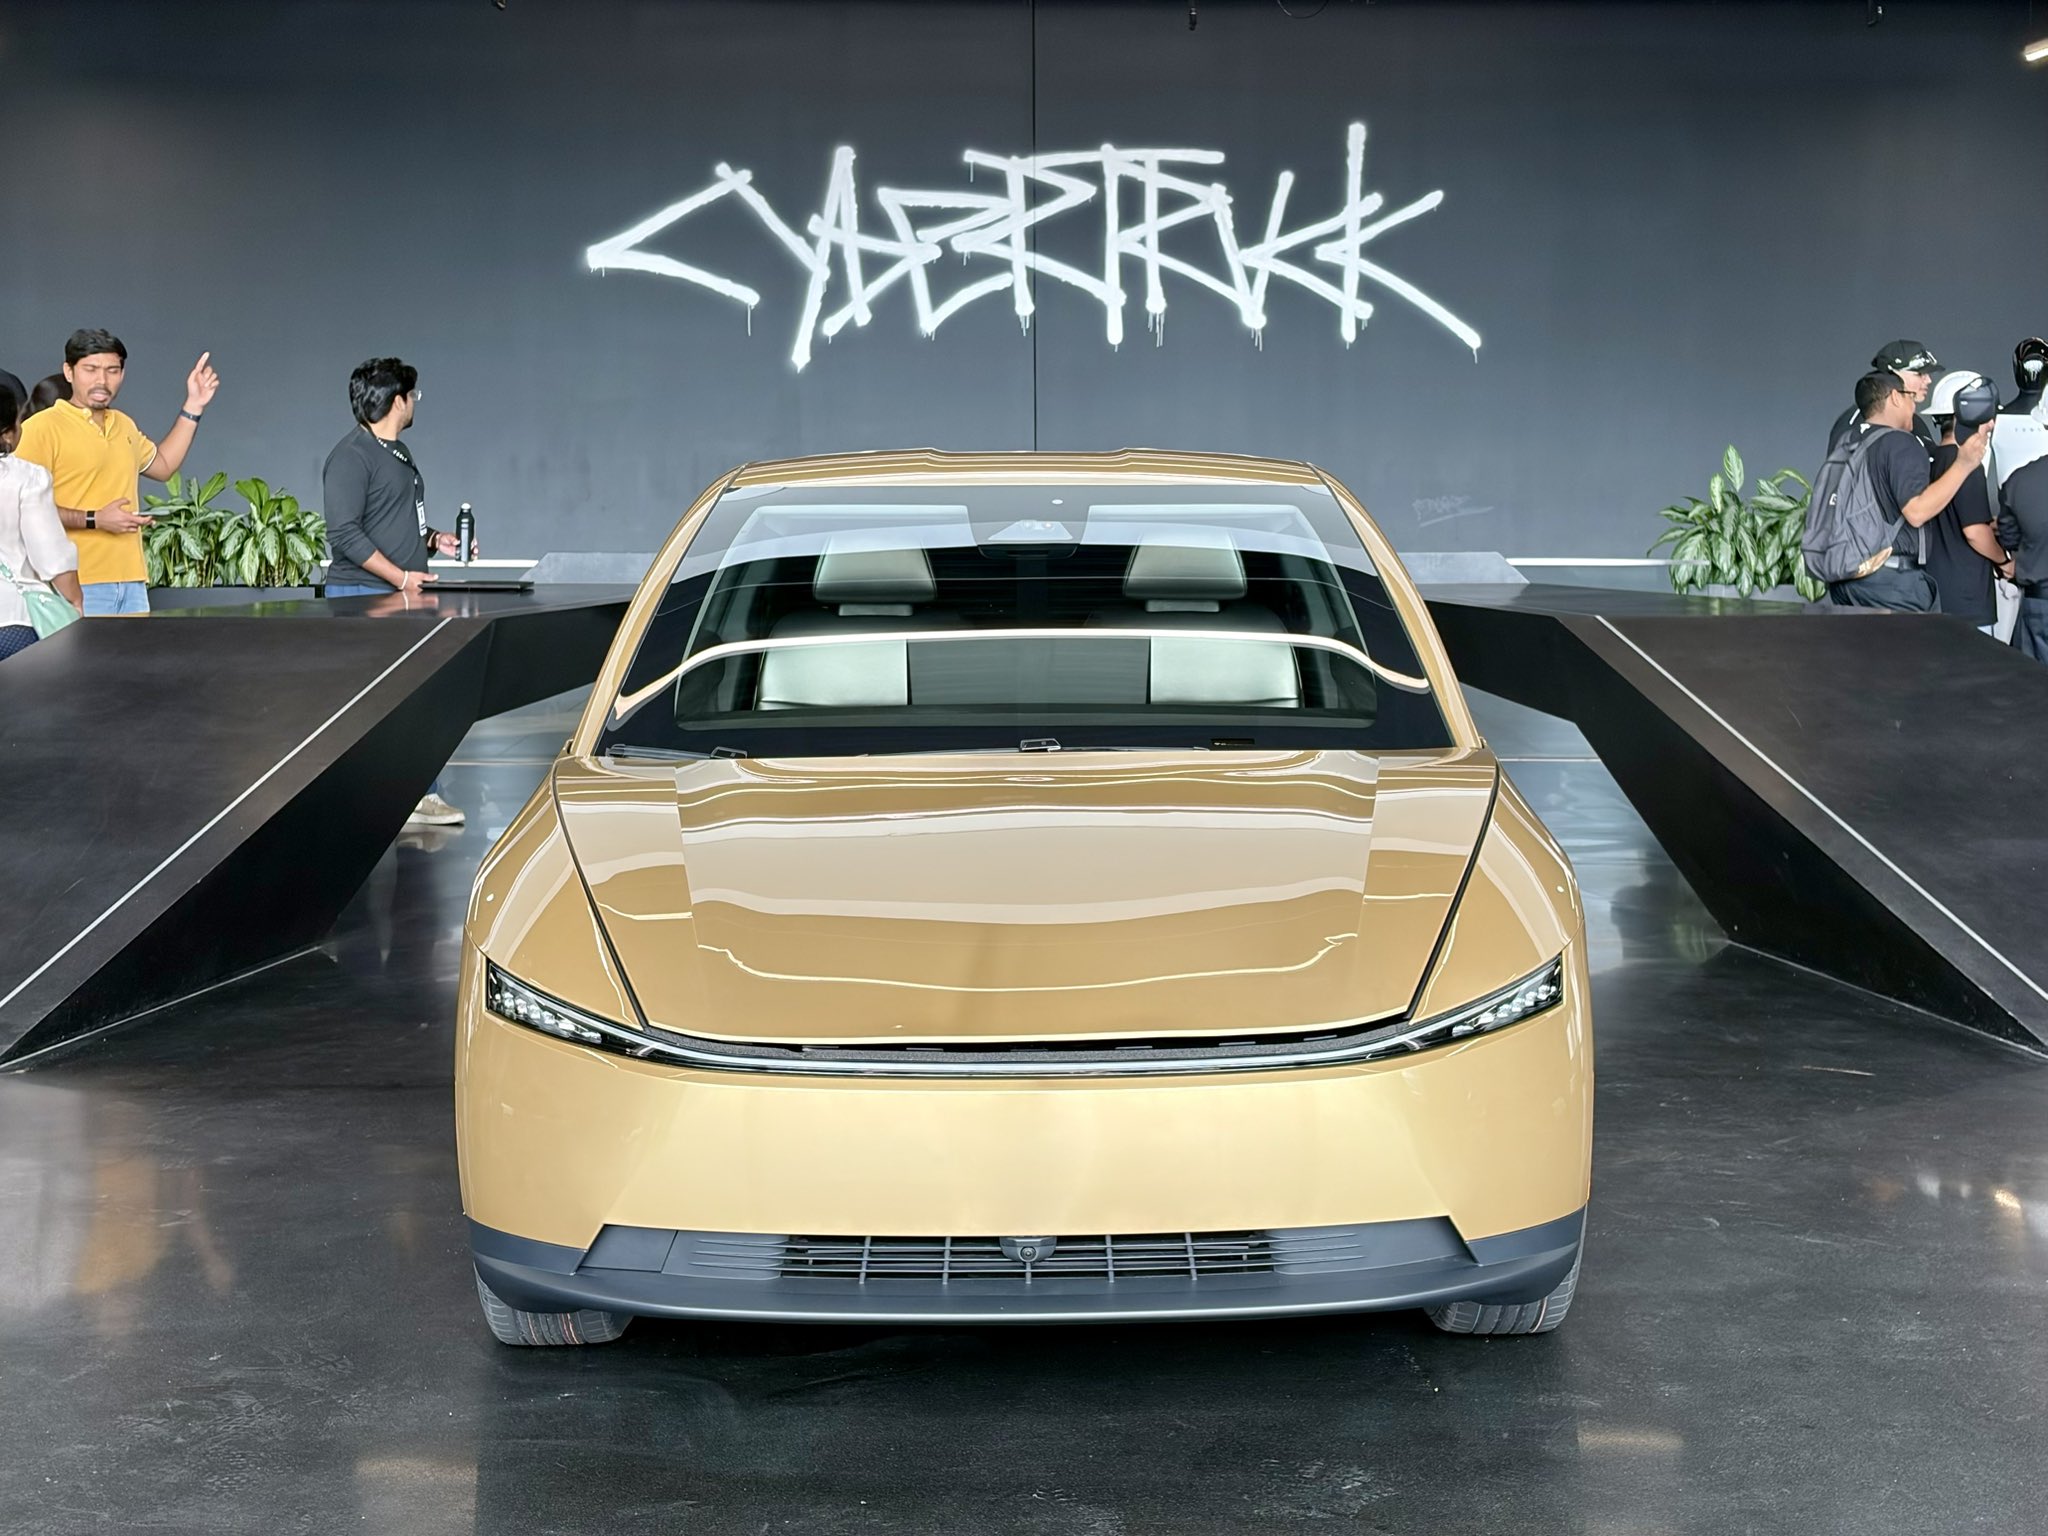
Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.
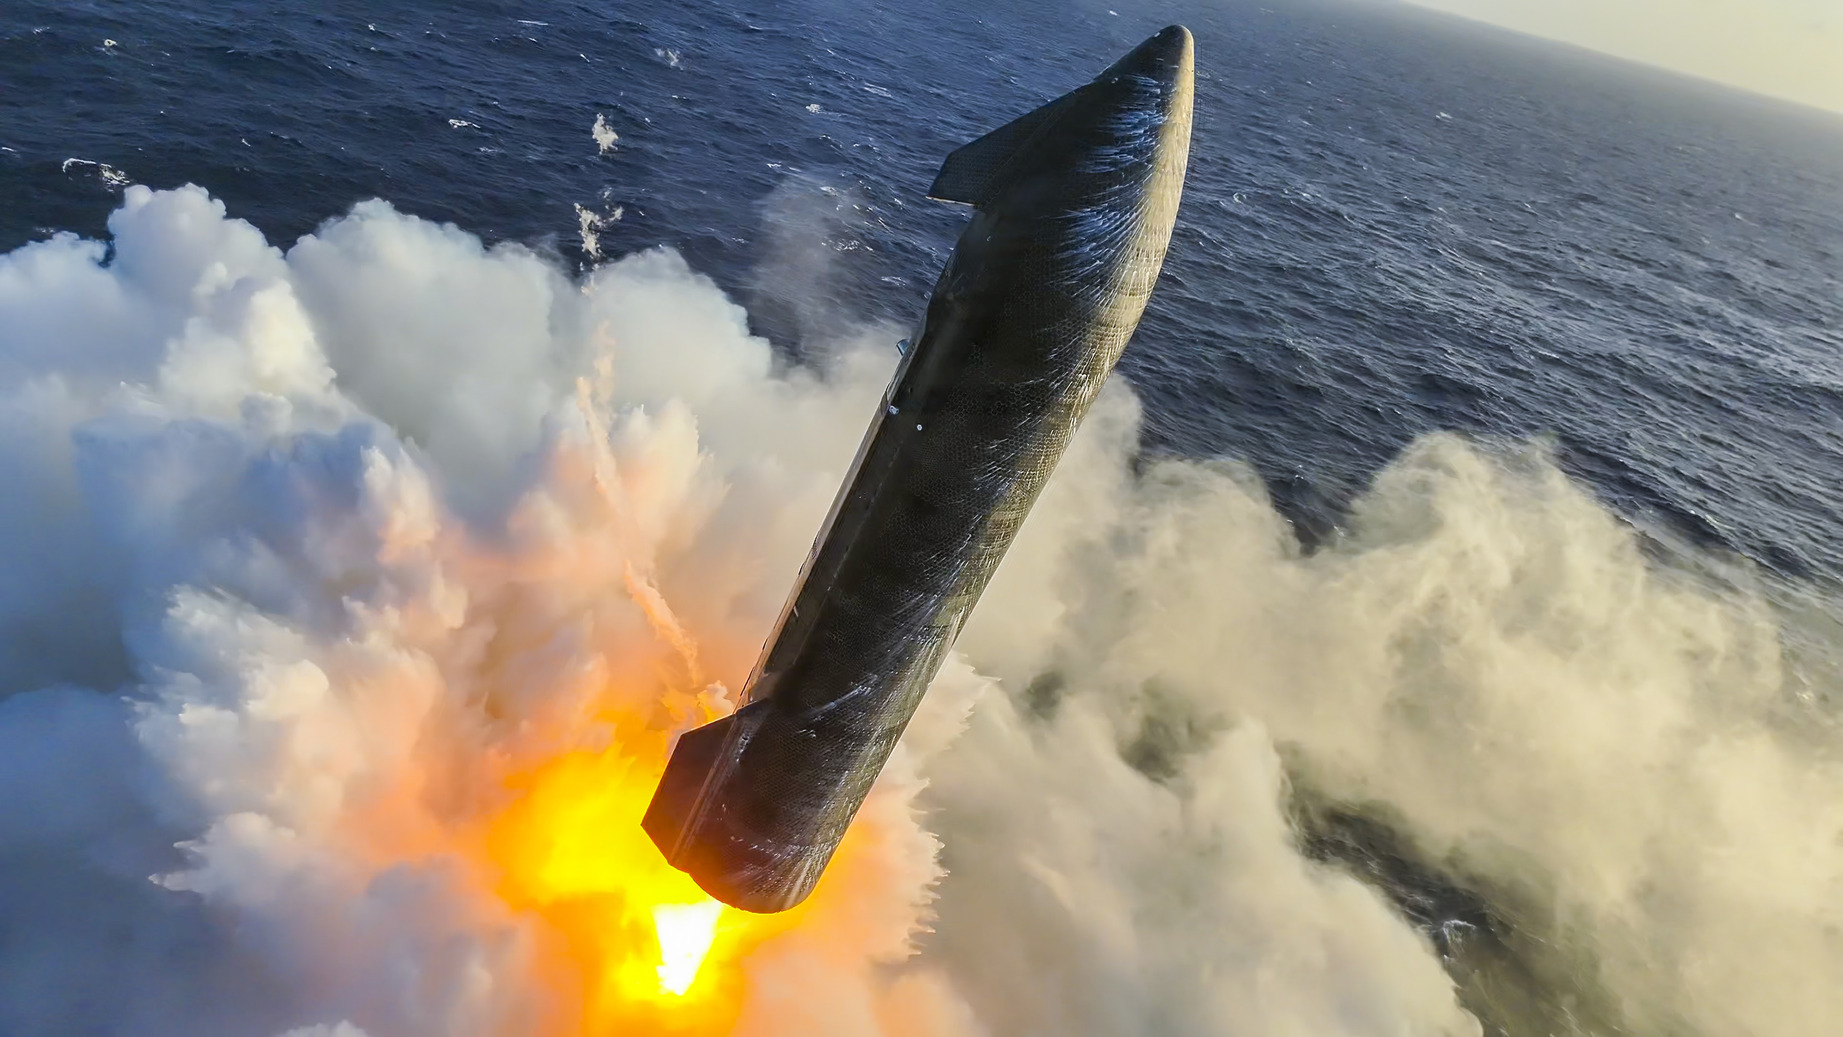
SpaceX confirmed the date of Starship’s 15th launch window with some massive ambitions for the mission, as it will attempt to catch Ship for the first time.
CEO Elon Musk confirmed during SpaceX’s Earnings Call last night on October 20 that it would launch Starship for its 15th test flight in November, and there are some incredible things the company wants to try, making it perhaps the most groundbreaking launch in the program’s history.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
The most major development of the call was SpaceX’s intention to catch Ship alongside catching the Super Heavy Booster, something that has happened in the past. SpaceX showed an animation of the Ship catch, which will be done on the launch tower’s chopsticks:
SpaceX has released a new Starship tower catch animation for the upcoming Flight 15! https://t.co/kStn01Da8u
— Truthful🛰️ (@Truthful_ast) October 20, 2026
This monumental goal is to catch both the Ship and Booster in a dual-catch scenario, an incredible feat since SpaceX has never been able to reuse a Ship after launch. Musk said it would be “the first time that an orbital launch vehicle has been fully recovered,” and said it would be a “profound technology milestone.”
Musk said the odds of success on this first Ship catch attempt are “more likely than not,” but SpaceX is ultimately prepared for more tries moving forward. The SpaceX frontman said that, starting next year, Starship would have a “steady stream” of flights through the end of the year.
The cadence will accelerate in 2027, with Musk stating the company plans to target weekly flights in the first half of 2027 and twice-weekly by year-end.
The Flight 15 attempt follows that of Flight 14, which took off in late September and was Starship’s first orbital mission. It deployed 26 Starlink V3 satellites, accomplished a controlled ocean splashdown of both stages, and shed more light on potential challenges for the program moving forward.
As of now, the Starship program is firing on all cylinders.
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
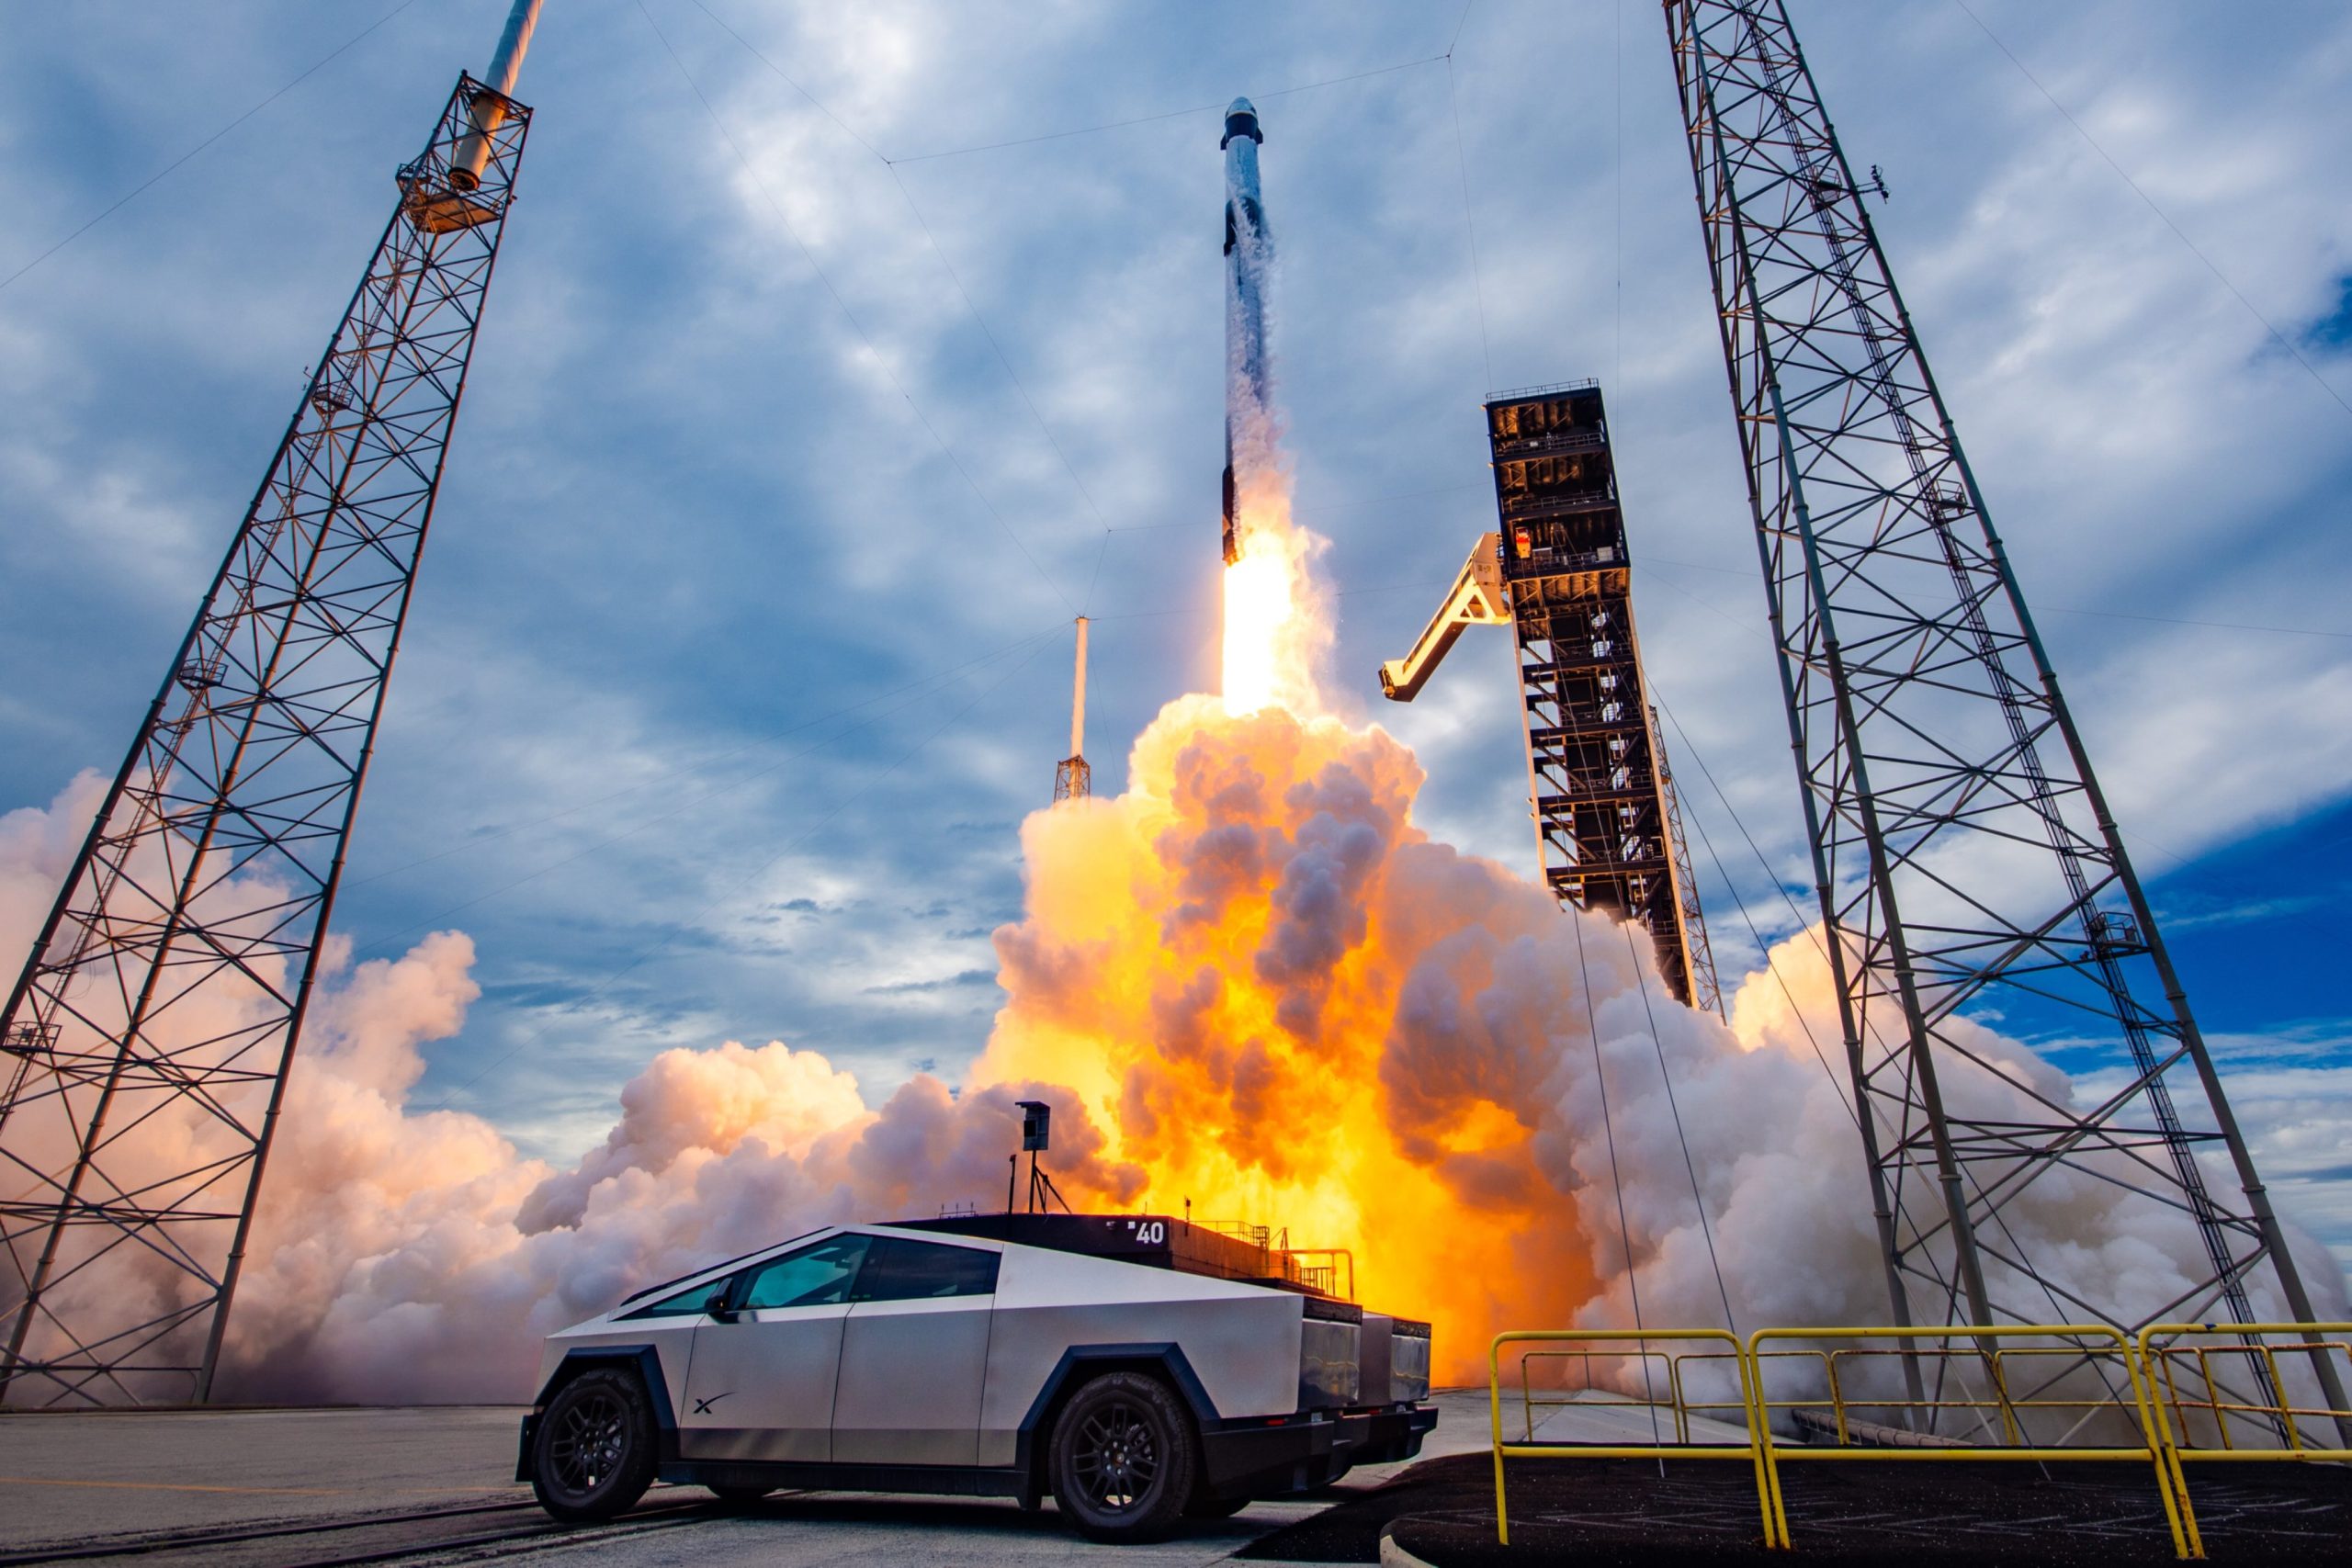
Wall Street analysts rapidly raised price targets on SpaceX (NASDAQ: SPCX) after the company reported a bullish third quarter for 2026 following the market close on October 20. Shares were sent sharply higher in after-hours and premarket trading.
SpaceX posted revenue of $14.6 billion, a 161 percent year-over-year increase that comfortably topped consensus estimates, which fell near $12.7 billion. The company also posted a net profit of $4.4 billion from a prior-year loss, with adjusted EBITDA reaching $8.8 billion.
More price target movement:
🚀 Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
🚀 Barclays raised its target to $300 from $254 (Overweight).
🚀 Citi increased its target to $240 from $200 (Buy),
🚀 UBS moved to $230 from $210 (Buy)
🚀TD Cowen raised its target to $224 from $200 (Buy).
🚀Morgan Stanley held an Overweight rating with a $300 target.
🚀Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.— TESLARATI (@Teslarati) October 21, 2026
Its Super Intelligence (AI) division generated roughly $7.6 billion and became the largest revenue contributor, growing nearly 830 percent year-over-year, while the Connectivity segment delivered $5.2 billion on strong subscriber additions that lifted the consumer base to 13.6 million for Starlink.
The Earnings Call proved especially catalytic, as CEO Elon Musk and CFO Bret Johnsen outlined Q1 2027 revenue guidance of $33 billion to $37 billion, which was far above the roughly $22 billion analysts had modeled, alongside fourth-quarter capital-expenditure plans of $35 billion to $40 billion focused on AI compute infrastructure at sites including Memphis and Southaven.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
Management targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end and discussed pathways to 13 gigawatts or more by the end of 2027. Musk described relentless demand from hyperscalers and other customers, with compute pricing supporting payback periods of less than a year and potentially as short as six months.
Additional highlights included Starship’s recent orbital success and V3 satellite deployment, Starlink pricing and enterprise momentum, rapid Grok Bot adoption, spectrum expansion plans, and the formation of special committees to explore a possible combination with Tesla.
These elements prompted a wave of price-target increases:
- JPMorgan more than doubled its target to $500 from $240 while maintaining an Overweight rating.
- Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
- Barclays raised its target to $300 from $254 (Overweight).
- Citi increased its target to $240 from $200 (Buy),
- UBS moved to $230 from $210 (Buy), and
- TD Cowen raised its target to $224 from $200 (Buy).
- Morgan Stanley held an Overweight rating with a $300 target.
- Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Shares, which closed at $147.79 on October 20, jumped roughly 8 percent in early premarket trading on October 21 as investors digested the results and the newly elevated Street targets.
The average analyst price target has moved higher, which reflects greater conviction in SpaceX’s trajectory across launch, connectivity, and the Super Intelligence business, even as elevated spending remains a point of focus.

Tesla reports Q3 Earnings today: here’s what to expect

SpaceX confirms Starship 15 launch window with massive ambitions


