Investor's Corner
Tesla price target cut by Morgan Stanley

Tesla’s (NASDAQ: TSLA) price target was cut by Morgan Stanley, a firm that has had a bullish outlook on the automaker’s stock for several years.
In a new note to investors released this morning, Morgan Stanley analyst Adam Jonas reduced the firm’s price target to $320 from $345, with the main thesis of the writing being concerned with EV demand.
“EV demand continues to decelerate despite continued price cuts,” Jonas wrote. “Fleets are dumping EVs and strong hybrid momentum is competing for the marginal EV buyer. Could Tesla lose money (sometime) this year?”
Jonas makes several points throughout the note, including Tesla’s aging product lineup, oversupply in key markets, and increasing demand for hybrids.
Tesla’s Aging Product Lineup
We have discussed this point of view in the past, and it’s hard to agree with it. While Tesla has had the same four vehicles in its lineup for several years now, the automaker has done nothing different than any other automaker in terms of refreshing and introducing new designs.
In the past, we’ve discussed how the Honda Civic has gone through generational changes every 4-7 years. Tesla has made routine changes to the Model S and Model X in that same timeframe, the Model Y is only a few years old and rumoredly in the process of a refresh with Project Juniper, and the Model 3 just received a complete overhaul via the Highland refresh.
Not to mention, the Cybertruck has been on the market for less than six months.
“Aging” is a tough word to use in order to describe this lineup correctly. It is hard to even consider it stale. While Tesla is working with a vehicle lineup that has been around for a few years, updates and refreshes are happening regularly.
Jonas mentions that Tesla’s lineup “may be the oldest of any major OEM,” but with the Cybertruck just launching and Model 3 just recently getting an in-depth overhaul, it is difficult to agree.
Oversupply in Key Markets
Jonas specifically mentions China here, and for good reason. Tesla is still very popular in China, but there are simply more affordable options, and consumers may not be able to justify spending three or four times the money.
In order to get back to its competitiveness, Tesla will need to launch a vehicle at this sort of price point, which would fall between $15,000 and $25,000.
What is going on in China is something Tesla could encounter in the United States in 5-10 years. Eventually, more companies will have EVs out there, and not everyone will want to pay a premium. Of course, Tesla plans to launch the next-gen platform sometime in 2025, so it is also a possibility that the company completely averts this situation in North America.
Hybrid Demand Increases
Hybrid sales increased five times faster than EVs last month, Jonas writes in the note. Some consumers may look at the best of both worlds for their next car, and hybrids may fit the bill of what they want. As someone who drove a Ford Escape Hybrid for seven years, it offered a lot of positives, including better fuel economy than the same model in an ICE version.
Jonas believes that Toyota will outpace any major automaker in the U.S. this year in terms of growth due to its focus on hybrid powertrains.
Price Target
Jonas reduced Tesla’s price target to $320 from $345.
“Our thesis on Tesla is that it is both an auto stock + an energy, AI/robotics company … Negative developments in the global EV market very much matter to Tesla and should reasonably have a negative near-term impact on the price of the stock. At the same time, however, we believe investors should not ignore the continued developments of tesla’s other plays,” Jonas writes.
While the firm reduced its price target to $320, it also believes that Tesla will not “get credit as an AI company as long as core auto earnings are being revised down.”
This makes it seem like the “$100 bear case may be in play,” Jonas said.
Disclosure: Joey Klender owns Tesla stock.
I’d love to hear from you! If you have any comments, concerns, or questions, please email me at joey@teslarati.com. You can also reach me on Twitter @KlenderJoey, or if you have news tips, you can email us at tips@teslarati.com.


Investor's Corner
Tesla’s flying Roadster just revealed something bigger than the car
Analysts say the Roadster demo puts a Tesla and SpaceX merger back on the table.

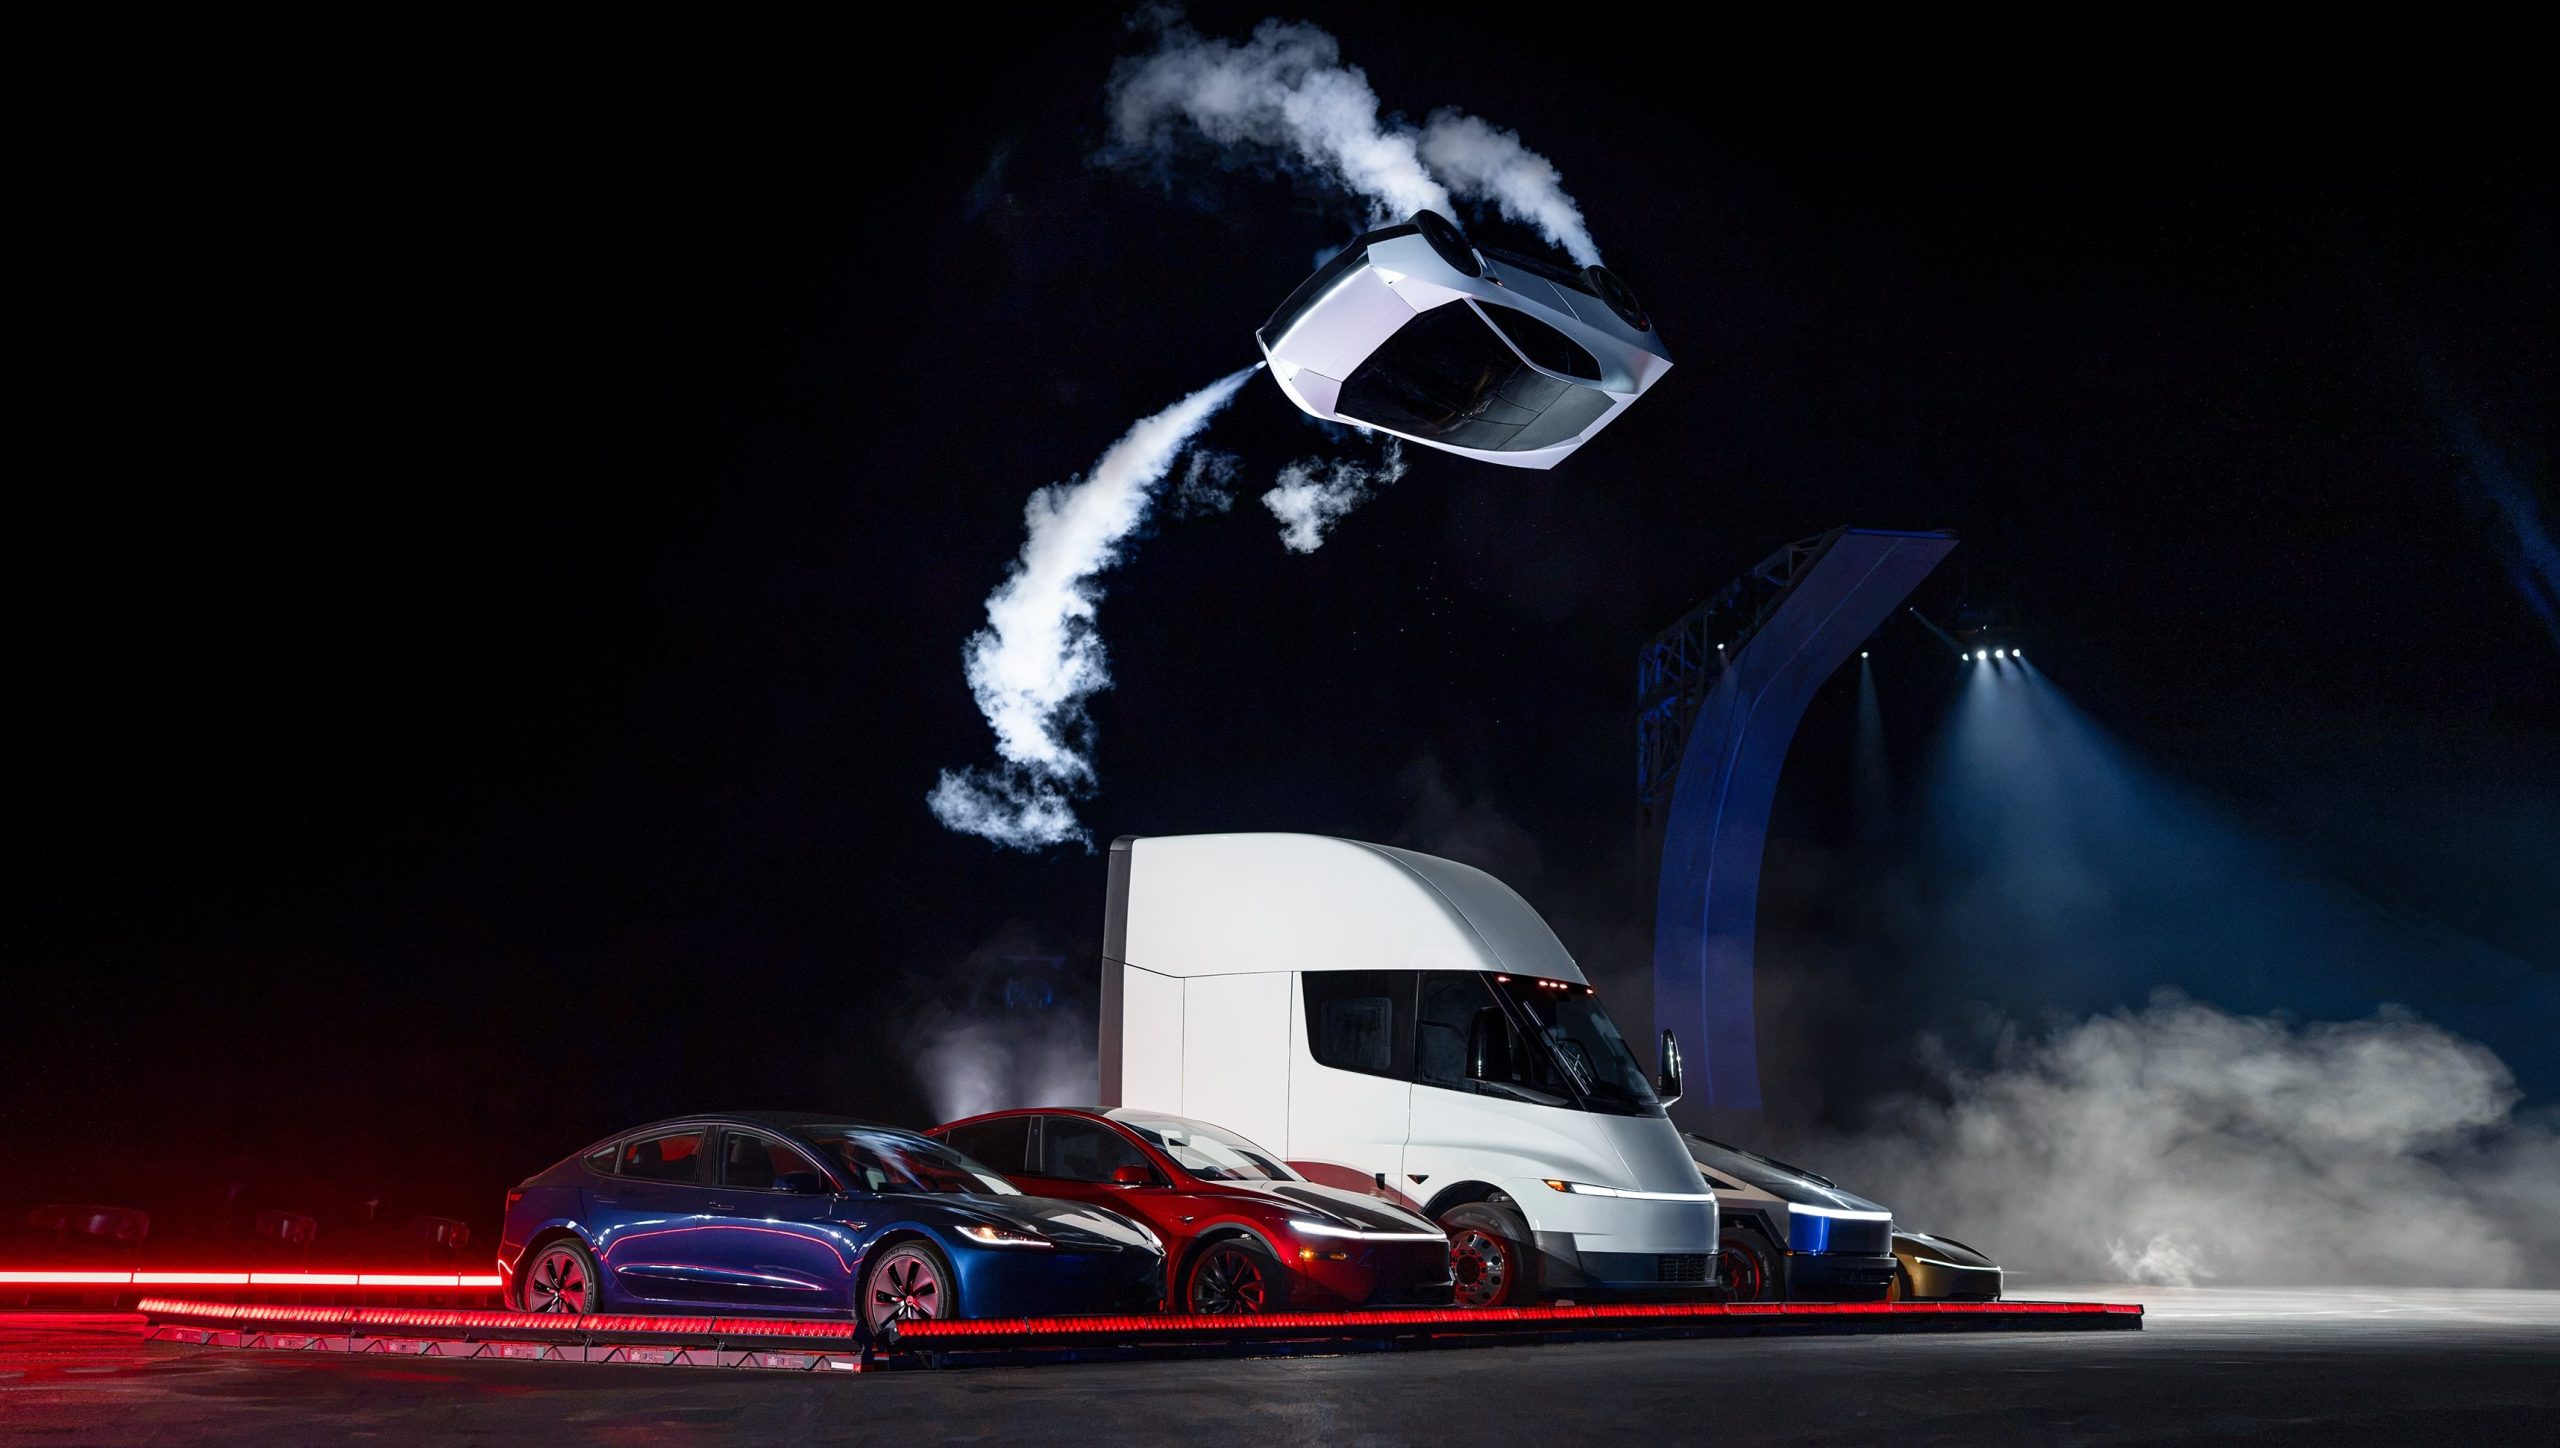
The Roadster unveiling near Waco ended Thursday night, and by Friday morning much of the investor reaction had less to do with the car than with who owns the rocket technology inside it.
Wedbush analyst Dan Ives said the event “puts the Tesla/SpaceX relationship on the table in a tangible way,” pointing to the propulsion, pressure vessel and control hardware sitting on a Tesla product. Gene Munster of Deepwater Asset Management called the demo “a ridiculous display of engineering” with “no commercial value” beyond embarrassing traditional automakers, though he said it showed Musk wants the two companies together.
The more specific forecast came a day earlier from Barclays. Analyst Dan Levy told clients a deal could be announced before Tesla’s annual meeting, which must happen by December 6, and that an announcement in late October or early November could make shareholder approval harder. Barclays expects SpaceX to be the buyer in an all stock deal, with Tesla holders receiving SpaceX shares at a premium, based on market values of roughly $2.1 trillion for SpaceX and $1.5 trillion for Tesla. If nothing lands around the meeting, the bank still sees an announcement within 6 to 12 months.
The Roadster demo just added more weight to merger speculations. Tesla’s demo used cold gas thrusters and pressure tanks of the kind SpaceX uses on Falcon 9, and Musk described the car as a collaboration between Tesla and SpaceX engineers, as we mentioned in our breakdown of the three Roadster configurations.
Musk has not publicly addressed a deal since the event, as far as we have seen. His most direct answer remains the one he gave at the All In Summit, when he said that with so much collaboration, “who can imagine what action one might take” without ruling anything out. Ives has held to a 2027 timeline since his March note, and Musk pushed back on the China piece of the speculation when ARK floated a year end announcement in August.
The next test is Tesla’s third quarter earnings call on October 21. However, we recall in July that Musk told analysts, “we can’t talk about combining companies and that kind of thing on an earnings call,” so a clear answer wouldn’t be expected.
Elon Musk
Elon Musk breaks his silence on the Starlink impact to Ukraine drones
Musk says the US military and president set Starshield limits, not SpaceX, amid Ukraine complaints.
Elon Musk says the speed limit cutting out Ukraine’s military Starlink terminals is not SpaceX’s decision. In a post on X Wednesday, Musk wrote that “Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.” He added that Starlink is a commercial service limited to civilian or defensive activities and “cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.”
He was replying to Mykhailo Fedorov, Ukraine’s former defense minister, who had thanked Musk for restoring connectivity at speeds up to 160 km/h and said removing the Starshield limit entirely is “now critical for Ukraine’s defense.”
Starshield systems are owned and controlled by the US government. Any limits on speed or usage are decided by the US military and ultimately POTUS.
Starlink is a commercial service owned and controlled by SpaceX. Usage of Starlink is limited to civilian or defensive activities and cannot be used for offensive military action, as doing so would be inappropriate for a commercial company.
— Elon Musk (@elonmusk) October 14, 2026
The complaint started Tuesday night, when Ukrainian officials said military terminals began losing service above roughly 100 mph. Presidential adviser Serhiy Beskrestnov said the defense forces got no warning and several missions were disrupted, as Teslarati reported earlier Wednesday. The 7th Rapid Reaction Corps told Reuters connections dropped for 10 to 20 seconds at speeds well below the limit, which made drones harder to control. Poland’s foreign minister, Radoslaw Sikorski, asked Musk on X whether he is “playing politics with your products again.”
That is why the Starlink and Starshield distinction matters. SpaceX introduced Starshield in 2022 as the government version of Starlink, with an initial focus on Earth observation, communications and hosted payloads. It won a Space Force contract in 2023 with a $70 million ceiling. In December 2024, the Pentagon moved Ukraine’s terminals onto Starshield, covering about 3,000 units across two contracts. Ukraine’s military connections therefore run through a service that Musk now says sits under Washington’s control.
While Musk’s post describes who holds authority, it does not infer that anyone ordered the limit, and neither SpaceX nor the US government has confirmed who set it. Ukrainian officials have pointed to the timing, which follows President Trump’s push for an energy ceasefire and Musk’s Saturday post that “Zelensky has gone too far.” The BBC noted Trump denied threatening to restrict intelligence sharing with Kyiv, and no evidence has been presented that Washington requested the cap.
The episode also revives a promise from 2025. After Poland accused him of threatening Ukraine’s access, Musk said Starlink “will never turn off its terminals” and would not be used as a bargaining chip. Poland has since supplied more than 29,000 terminals to Ukraine. Teslarati also covered Kyiv’s search for Starlink alternatives in 2025, and the latest dispute gives that search new urgency.
Investor's Corner
Tesla opens the Q&A for its biggest earnings call yet
Tesla opens its Q3 earnings Q&A, and Cybercab, Robotaxi, Optimus and regulators loom over October 21.
Tesla has opened its shareholder question portal for the Q3 2026 earnings call, with the Say Q&A page already listing questions. Investors have until 4:00 p.m. EDT on October 20 to submit and vote on what management should answer.
The call is set for Wednesday, October 21. Tesla will post results after the market closes, with a live webcast at 4:30 p.m. CT, or 5:30 p.m. ET, through its investor relations site.
Say ranks questions by the number of shares behind the votes, which gives institutional holders extra weight over the retail crowd.
Ahead of Q2, retail investors asked why Robotaxi growth had stalled, when Cybercab would start customer rides, and where the Optimus Gen 3 ramp stood, while an institutional holder asked how Tesla and SpaceX would split Terafab duties. Cybercab has since answered one of those. Tesla said last week it has 300 plus Cybercabs serving Austin, up eightfold in 30 days, with Dallas named as the next city. The questions now are likely to move from when to how fast.
There is also a regulatory question hanging over the call. NHTSA has demanded sworn answers on how the pedal free Cybercab was certified against federal safety standards, with responses due October 30, nine days after the call. Whether an analyst raises it live is unknown, but it is the kind of exposure that tends to find its way into a Q&A.
The numbers will not be the main draw. Tesla already reported 486,532 deliveries and 13.7 GWh of storage for the quarter. Consensus sits around 43 to 45 cents per share on roughly $27.8 billion in revenue, according to Zacks, after a Q2 report that missed on EPS. Goldman Sachs, which holds a Neutral rating and a $360 target, argues the outlook for Robotaxi, FSD and Optimus will matter more to the stock than the quarter itself.
The call also lands six days after the rescheduled Roadster event, which Tesla will stream on X on Thursday, October 15, at 7:55 p.m. CT. If the Roadster shows up with a production date or a SpaceX thruster package, expect it to climb the voting list before the deadline.

Tesla’s flying Roadster just revealed something bigger than the car

How Tesla’s Roadster fan system and thrusters are built to dominate the corners

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Elon Musk’s Boring Company lands a new Middle East deal, and Nashville is about to get faster


