Investor's Corner
Tesla (TSLA) drops in the aftermath of Q1 earnings: Here’s Wall St’s take

Tesla stock (NASDAQ:TSLA) experienced a 3% drop on Thursday’s intraday as the electric car maker felt the aftermath of its Q1 2019 earnings. The company posted a loss of $702 million or $4.10 a share in the first quarter, which is almost comparable to Q1 2018’s loss of $4.19 per share.
Tesla CEO Elon Musk and the company’s executives explained during the Q1 2019 earnings call that the company’s lower-than-expected performance was due to one-time items and circumstances such as delivery delays for the Model 3 in Europe and China. With Tesla back in the red, here is what Wall Street analysts are now saying.
Wedbush analyst Daniel Ives, a longtime TSLA bull, downgraded Tesla from “Outperform” to “Neutral” while adjusting his price target for the company from $365 per share to a far more conservative $275 per share. Ives also penned a scathing note on Thursday, calling Tesla’s Q1 results as one of the “top debacles” Wedbush has ever seen, and criticizing the company’s executives for their belief that demand and profitability will “magically” return in the coming quarters.
“In our 20 years of covering tech stocks on the Street, we view this quarter as one of the top debacles we have ever seen while Musk & Co. in an episode out of the Twilight Zone act as if demand and profitability will magically return to the Tesla story. Ultimately we believe the company’s guidance is aggressive and management/board is not taking aggressive enough cost-cutting actions and shutting down future endeavors to preserve capital and give a sustained path to profitability for the Street. We no longer can look investors in the eye and recommend buying this stock at current levels until Tesla starts to take its medicine and focus on the reality around demand issues which is the core focus of investors,” Ives wrote.
Ryan Brinkman of JP Morgan noted that a negative reaction was already expected considering Elon Musk’s previous comments about Tesla’s inability to turn a profit in Q1. Brinkman, who has an “Underweight” rating and a $200 price target on TSLA stock, also pointed out Tesla’s willingness to do a capital raise this year. “Management also seemed less opposed to an equity capital raise, acknowledging “some merit” to the idea, which in our view serves to highlight dilution risk that likely rises after 1Q cash flow and cash balance tracked weaker than JPM and consensus expectations. While 2Q deliveries guidance appears potentially aggressive, the full year outlook for 360-400K implies a further roughly +35% to +45% sequential increase from 1H19 to 2H19, further highlighting the execution risk entailed in meeting the figures that are implied needed to generate positive earnings and cash flow,” he wrote.
Joseph Spak from RBC noted that Tesla’s Q1 numbers were “uglier than expected,” while stating that a capital raise will likely be held this year. Similar to Brinkman, Spak reiterated his “Underweight” rating and $200 price target for Tesla stock. “Elon talked about putting Tesla on a ‘Spartan diet’ and while we don’t doubt the company spent inefficiently in the past, the low capex+R&D and of course the lower sales, are not hallmarks of a hyper-growth company, yet TSLA continues to be valued as one,” he wrote.
Evercore ISI analyst Arndt Ellinghorst also proved bearish on the company, expressing his reservations about Tesla in a segment of CNBC‘s Street Signs. The analyst was skeptical of the demand for Tesla’s vehicles, even noting that the Model S sedan and the Model X SUV are already starting to look “quite old.” “If you claim that demand is huge and unlimited then the key question is, why do you lower your mix? Why do you lower your pricing? I mean the S and the X are quite advanced in any normal life cycle of a product so they would really need a significant refresh in order to restore the pricing. The brand will be less exclusive than it has been in the past,” the Evercore ISI analyst said.
Not all analysts covering the company were bearish after Tesla’s release of its first-quarter results. In a note, Piper Jaffray analyst Alexander Potter opted to look into the coming quarters for a potential recovery, while pointing out that Tesla’s shortcomings in Q1 were the result of several factors. “Although logistical challenges—long with lower transaction prices—had an obvious impact on Q1 profitability, we think this was temporary,” analyst Alexander Potter wrote in a note. “Guidance implies a second-half recovery for both deliveries and margins, and this seems reasonable to us. The first quarter suffered from a particularly nasty combination of headwinds, including seasonality, a big buildup of non-US deliveries (negative for logistics costs and working capital), as well as the expiration of tax incentives in the United States,” Potter wrote.
As of writing, Tesla is trading down -3.35% at $250.00 per share.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.

Investor's Corner
Elon Musk drops a Thanksgiving hint about Starship’s biggest test yet
Elon Musk says Starship Flight 15 will try to catch the ship itself, a first.

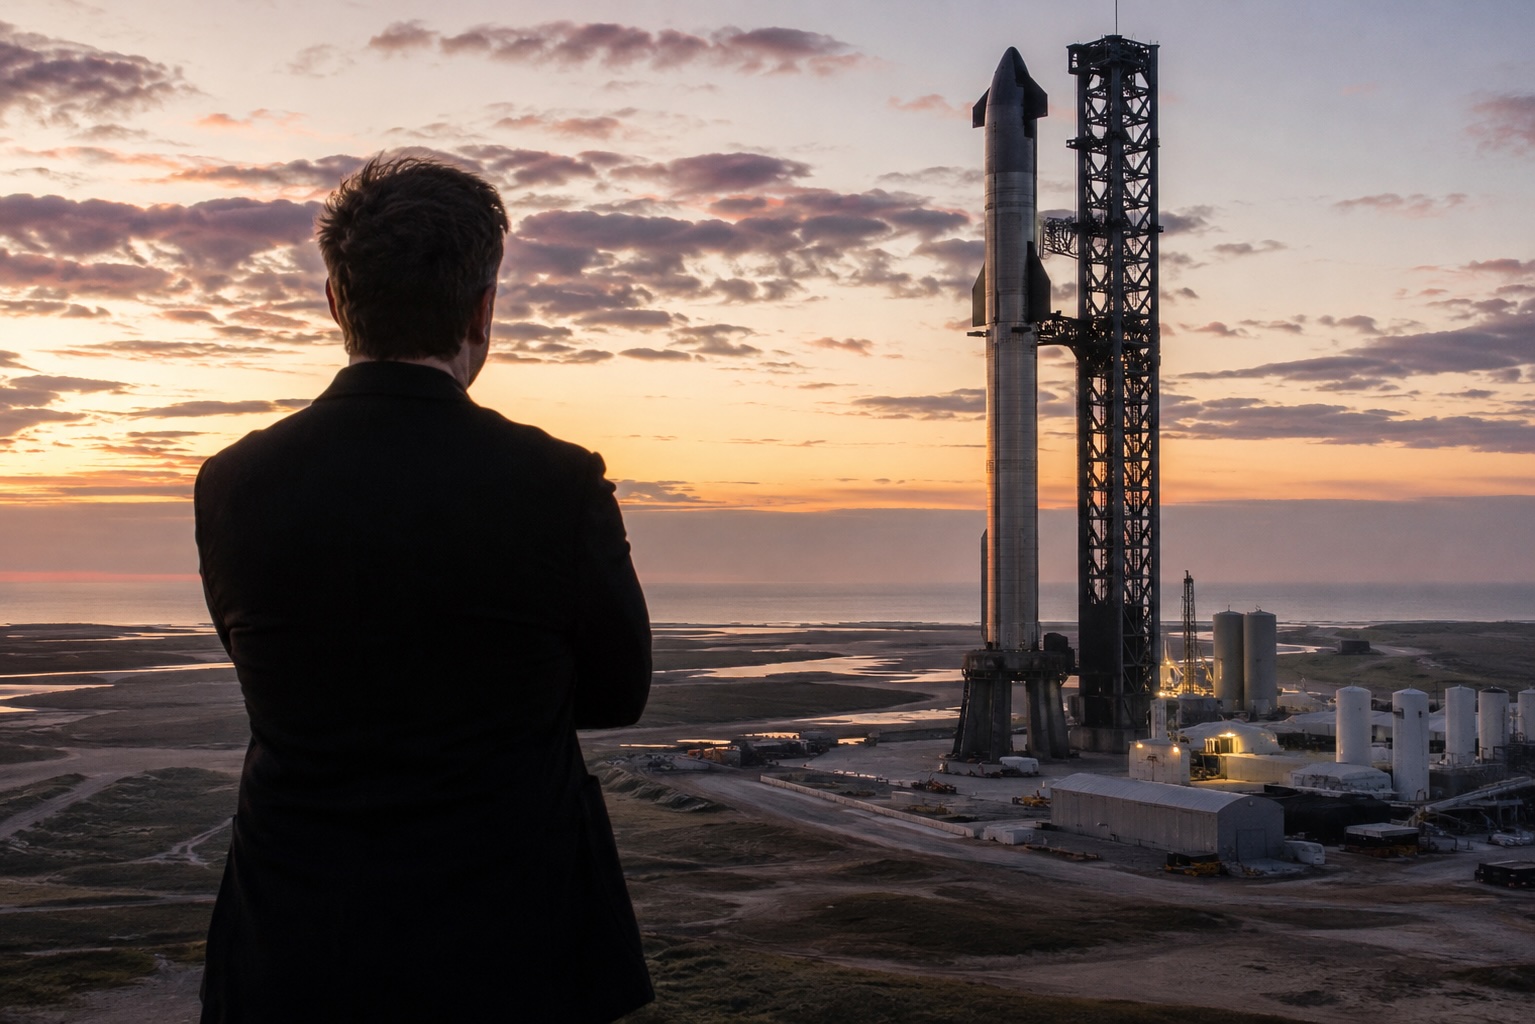
Elon Musk says SpaceX’s next Starship flight will try something nobody has done before, by catching the ship itself. Speaking to roughly 2,000 people at the X Takeover event at Giga Texas on Saturday, Musk said Flight 15 is about four to six weeks away and “probably launches a little bit before Thanksgiving, is my guess.”
That is a slip from earlier reporting, which had pointed to a launch as early as October 19. Musk explained why the date keeps moving. “We’re making a bunch of improvements to the rocket between every flight,” he said, adding that there are often hundreds, sometimes thousands, of small changes. This time the list is short, “but some of them take a fair bit of work and we’ve got to go inside the tank to make some of these changes.”
“We’re going to try to catch the ship, which is a super big deal,” Musk said. “If we do so, that’ll be the first time that there’s been full recovery of an orbital class rocket.” SpaceX has already caught the Super Heavy booster with the tower’s mechanical arms, and has talked about catching the ship since late 2025, but the upper stage has never been caught.
Musk also laid out what comes after. “The next big milestone would be to refly both the booster and the ship,” he said, describing a Flight 16 where “all parts of an orbital rocket are reflown.”
The reason SpaceX wants this comes down to cost and cadence. Every Starship ship so far has ended its flight in the ocean, and SpaceX expects most of those water landings to end in fireballs. A ship that returns to Starbase intact can be inspected and flown again. SpaceX’s IPO filing, says Starship V3 is designed to deliver 100 metric tons to orbit in a fully reusable configuration, that SpaceX aims to cut the cost to reach orbit by 99% or more versus the historical average, and that tower catches should allow “multiple launches per day.”
The payoff goes beyond cheaper launches. The next generation Starlink V3 satellites are too large for Falcon 9 and can only fly on Starship, which can carry up to 60 per flight. Flight 14 on September 28 deployed the first 26 of them after Starship reached orbit despite an early engine shutdown, as Teslarati reported. Musk blamed engine computer software, and said the heat shield “was extremely robust,” which he claimed in August had solved Starship’s biggest challenge.
NASA’s Moon plans depend on the same capability. NASA’s inspector general has described a lander mission that needs a propellant depot in low Earth orbit and more than 10 tanker flights, with SpaceX targeting one tanker launch every six days. That schedule only works if ships and boosters come back fast and fly again. Also, ship to ship propellant transfer has not been attempted yet.
One interesting hurdle yet to be explored is bringing the ship back to the launch site, with reentry over land, which will undoubtedly come with a lot of aviation safety reviews.
Investor's Corner
SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions
SpaceX reveals plans for one million Starmind AI satellites and calls out operators hiding maneuvers.
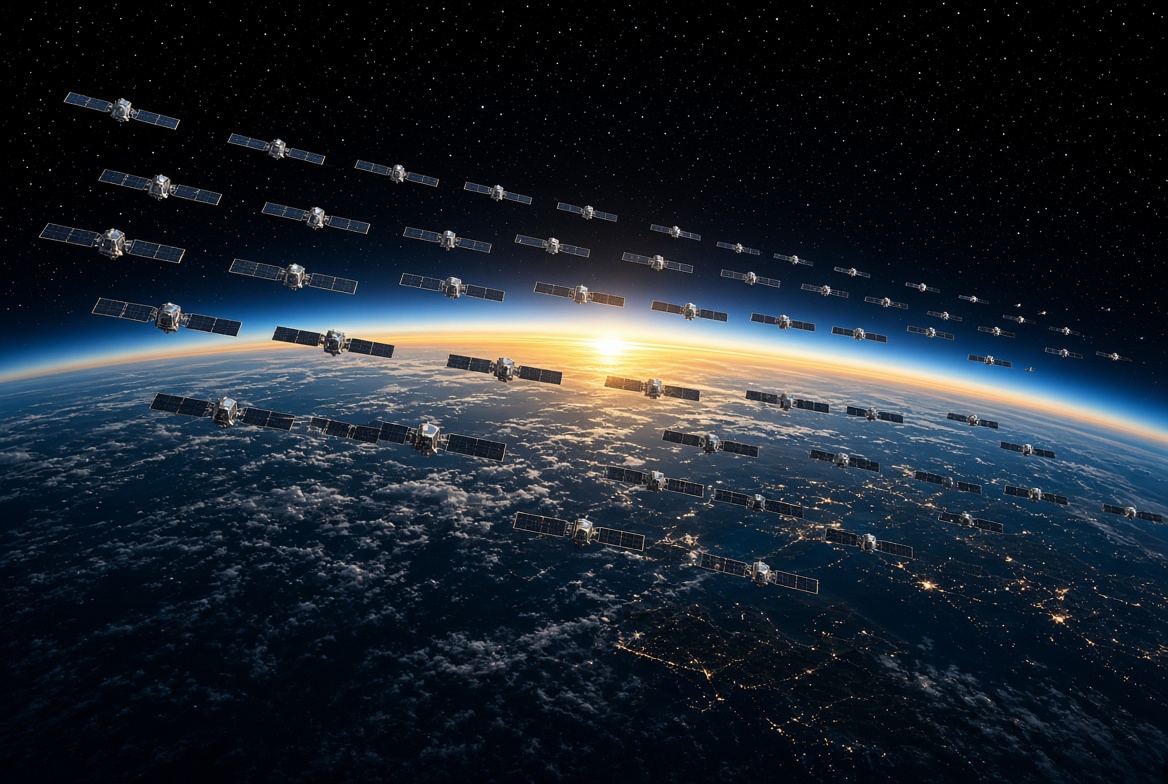
SpaceX has put the largest satellite count it has ever published into writing, and it says that plan only works if every other operator in orbit starts sharing what it knows.
In a new Space Safety page highlighted Tuesday morning by Sawyer Merritt on X, SpaceX said it “plans to operate up to 100,000 Starlink satellites and up to 1 million Starmind AI satellites to meet the growing demand for broadband and supercompute.” Starlink has a little over 11,000 satellites in orbit today, so the target alone implies roughly a ninefold expansion of the broadband network.
Starmind is SpaceX’s orbital AI compute constellation. Elon Musk confirmed the Starmind name in June after an xAI trademark filing surfaced, and in August SpaceX said it was working with Nvidia on the compute payload. The FCC accepted the filing for up to one million satellites back in February.
FCC accepts SpaceX filing for 1 million orbital data center plan
SpaceX also released a new render of what a full Starmind constellation could look like. Alongside it, SpaceX VP Michael Nicolls explained why the satellites will not operate on their own. “We need to operate clusters of satellites in tight formation to get enough coherent compute to run AI models efficiently,” Nicolls said. “A cluster will be 10-ish satellites connected with 10 terabits or so of bandwidth between them, and interconnected to the broader constellation.”
That is the most specific detail SpaceX has given on how Starmind will be built. Instead of a million independent servers, the network would work as tightly packed groups of about 10 satellites acting as one compute unit, with Starlink’s laser links carrying results back to Earth.
There is a bright and exciting future for humanity ahead – and space is fundamental to that future.
To achieve this, space safety must be done right. We encourage every operator to not only share ephemeris data proactively the same way Starlink already does, but to also adopt the high standards of space safety that SpaceX and Starlink use every day → https://t.co/QizAkQZvEm
— Starlink (@Starlink) October 6, 2026
Packing satellites that close together, at that scale, makes collision avoidance the central problem, and most of the Space Safety page is aimed at other operators. SpaceX said Starlink encountered collision risks with about 650 unique maneuvering third party satellites in 2026, and only about half of them shared data. Over six months, Starlink recorded roughly 164,000 more collision risks where the closest approach came within four hours of an unannounced maneuver.
Some operators keep maneuver plans private over proprietary concerns, while others cannot get government permission to share them. SpaceX called those policies “counterproductive,” saying they “largely only serve to create preventable collision risk between satellites.” Starlink is also offering a free ephemeris sharing and screening platform that returns risk results within a minute, backed by its Stargaze network of 30,000 optical sensors.
The push comes as the Starmind application draws opposition from astronomers and environmental groups. In a September filing with the FCC, SpaceX said each Starmind satellite could weigh up to 4,000 kg, nearly seven times the mass of a Starlink V2 Mini. Musk has brushed off crowding concerns before, telling viewers in June that “space is enormous” and that SpaceX already knows how to run very large constellations safely.
SpaceX’s Starmind page says its Gigasat factory in Bastrop, Texas, is designed to produce AI satellites at scale, with deployment of thousands of units starting as soon as late 2027.

Tesla (NASDAQ: TSLA) reported strong delivery figures that beat Wall Street guesses, and they were revealed alongside the company’s second-best quarter in terms of energy deployments ever.
Tesla announced this morning that it delivered 486,532 cars in Q3, while producing 464,391, exceeding analyst consensus, which sat around 462,000 units.
Meanwhile, Tesla reported 13.7 GWh of energy storage deployed for the quarter. That’s the second-best quarter Tesla has ever reported on that side of things.
🚨 Tesla delivered 486,532 vehicles in Q3, beating expectations at 464,391.
Big Q from the Tesla team, also 13.7 GWh of energy was deployed. pic.twitter.com/olioLWgG7a
— TESLARATI (@Teslarati) October 2, 2026
Vehicle Deliveries
Deliveries were strong, and it was another quarter when Tesla had the opportunity to outshine the Wall Street pundits who are quick to criticize and slow to give credit. Tesla saw a slight decrease in deliveries compared to Q3 2025, but Tesla still had the $7,500 EV Tax Credit to use to help incentivize consumers to pick an EV.
A small decrease of 2.1 percent is pretty telling because it shows Tesla does not need massive federal credits to convince consumers to purchase its vehicles.
It was also the company’s third-best performance all-time in terms of deliveries, trailing that of Q3 2025 with 497,099 deliveries and Q4 2024, when the company handed over 495,570 cars.
We reported several days ago that Tesla Showrooms across the United States were completely bare of inventory or unclaimed units. Many locations also removed Demo Drive units, which had been bought by customers looking to take delivery sooner.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
Energy Generation
Tesla’s Energy Generation performance in Q3 was also very strong, as the company deployed 13.7 GWh of energy storage over the past three months. The only quarter when Tesla reported stronger energy deployment figures was Q4 2025, when 14.2 GWh of energy storage was deployed.
Tesla’s Q3 performance in energy generation has continued to grow each quarter, with the company increasing its deployments by ten-fold since Q3 2021, when just 1.3 GWh was deployed.
It is also nearly double what it was in Q3 2024, when the company reported 6.9 GWh. This is one of Tesla’s quickest-growing divisions, and it flies under the radar with fans and analysts, as many are focused on self-driving or the vehicles themselves.
Tesla Stock
Shares rose 5.07 percent to $372.06 at just after 10 a.m. on the East Coast. This is a rarity for Tesla after a strong delivery report, as positive news usually brings the stock down. Many quarters with extremely robust delivery reports have not been as kind to the Teslanaires of the world.

Tesla Cybercab and Robotaxi’s real advantage won’t be the ride service

Why Elon Musk’s target date for buying an Optimus robot is harder than it sounds

Elon Musk drops a Thanksgiving hint about Starship’s biggest test yet

The Pentagon taps Elon Musk to design the battlefield of the future

Tesla Roadster’s new patent preps white-knuckle speeds, keeping it grounded


