News
SpaceX nears big US govt. missions as ULA handwaves about risks of competition

Speaking at the 2018 Von Braun Symposium in Huntsville, Alabama, ULA COO John Elbon expressed worries that the US National Security Space (NSS) apparatus could be put at significant risk if it comes to rely too heavily on the commercial launch industry to assure access to space.
Given that the US military’s launch capabilities rest solely on SpaceX and ULA and will remain that way for at least three more years, Elbon’s comment was effectively an odd barb tossed in the direction of SpaceX and – to a lesser extent – Blue Origin, two disruptive and commercially-oriented launch providers.
-
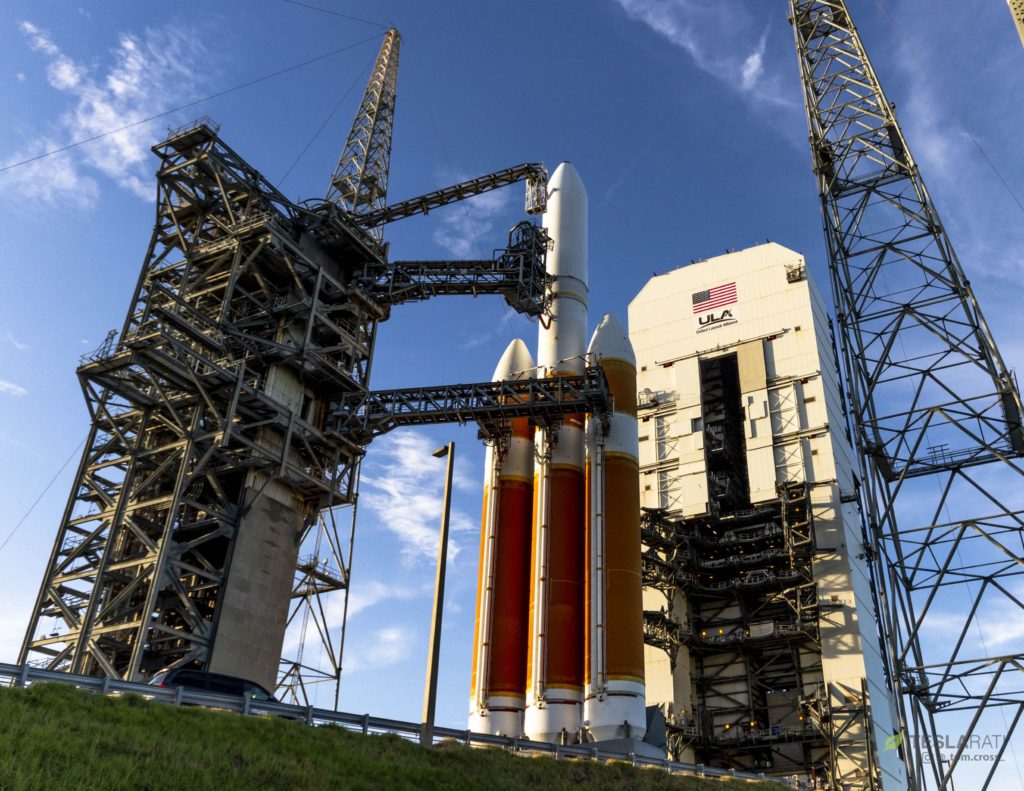
- The history of ULA and its Delta IV rocket is far wilder than most would expect. (Tom Cross)
-
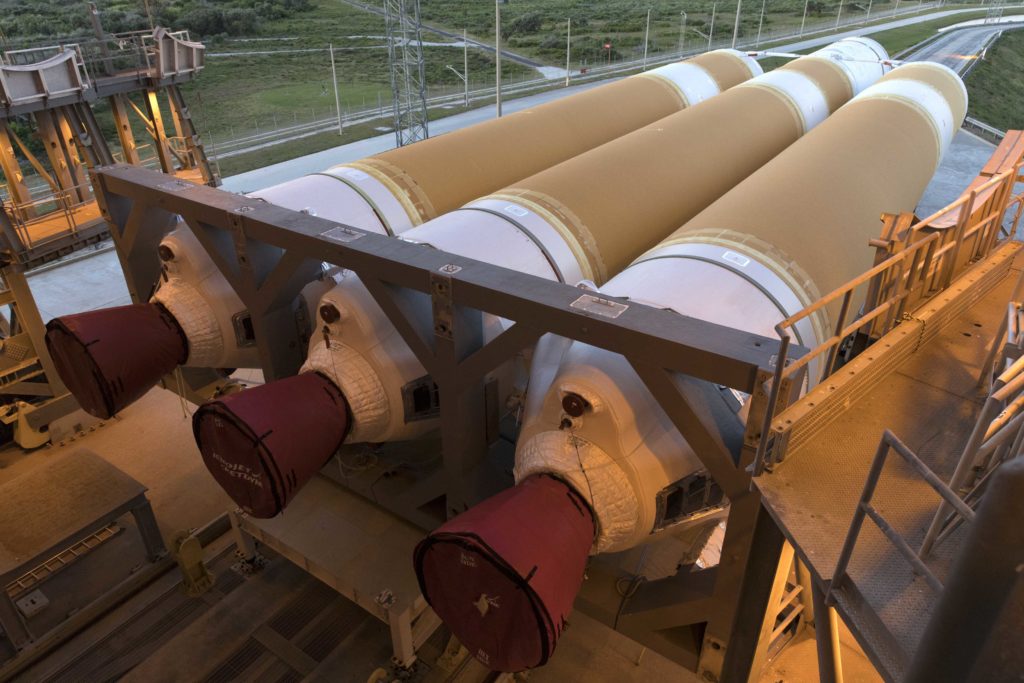
- The first stage of Parker Solar Probe’s Delta IV Heavy rocket prepares to be lifted vertical. (ULA)
Reading between the lines
For the most part, Elbon’s brief presentation centered around a reasonable discussion of ULA’s track record and future vehicle development, emphasizing the respectable reliability of its current Atlas V and Delta IV rockets and the ‘heritage’ they share with ULA’s next-generation Vulcan vehicle. However, the COO twice brought up an intriguing concern that the US military launch apparatus could suffer if it ends up relying too heavily on ‘commercially-sustained’ launch vehicles like Falcon 9/Heavy or New Glenn.
To provide historical context and evidence favorable to his position, Elbon brought up a now-obscure event in the history of the launch industry, where – 20 years ago – companies Lockheed Martin and Boeing reportedly “set out to develop … Atlas V and Delta IV” primarily to support the launch of several large satellite constellations. The reality and causes of the US launch industry’s instability in the late ’90s and early ’00s is almost indistinguishable from this narrative, however.
Despite the many veils of aerospace and military secrecy surrounding the events that occurred afterward, the facts show that – in 1999 – Boeing (per acquisition of McDonnell Douglas) and Lockheed Martin (LM) both received awards of $500M to develop the Delta IV and Atlas V rockets, and the military further committed to buying a full 28 launches for $2B between 2002 and 2006. Combined, the US military effectively placed $3B ($4.5B in 2018 dollars) on the table for its Evolved Expendable Launch Vehicle (EELV) program with the goal of ensuring uninterrupted access to space for national security purposes.
-
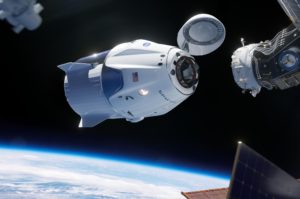
- Crew Dragon arrives at ISS. (SpaceX)
-
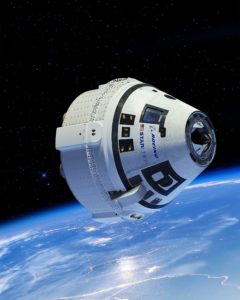
- Boeing’s Starliner spacecraft. (Boeing)
-
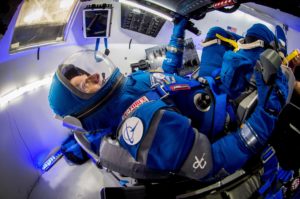
- A mockup of Boeing’s Starliner capsule is explored by one of NASA’s Commercial Crew astronauts, clad in a Boeing spacesuit. (Boeing)
-
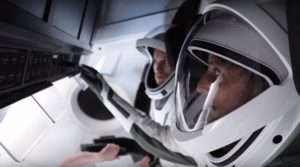
- SpaceX’s Commercial Crew pressure suit seen on NASA astronauts during testing. (SpaceX)
Rocketing into corporate espionage
“The robust commercial market forecast led the Air Force to reconsider its acquisition strategy. The EELV acquisition strategy changed from a planned down-select to a single contractor and a standard Air Force development program [where the USAF funds vehicle development in its entirety] to a dual commercialized approach that leveraged commercial market share and contractor investment.” – USAF EELV Fact Sheet, March 2017
The above quote demonstrates that there is at least an inkling of truth in Elbon’s spin. However, perhaps the single biggest reason that the EELV program and its two awardees stumbled was gross, inexcusable conduct on the part of Boeing. In essence, the company’s space executives conspired to use corporate espionage to gain an upper-hand over Lockheed Martin, knowledge which ultimately allowed Boeing to severely low-ball the prices of its Delta IV rocket, securing 19 of 28 available USAF launch contracts.
Ultimately, Lockheed Martin caught wind of Boeing’s suspect behavior and filed a lawsuit that began several years of USAF investigations and highly unpleasant revelations, while Boeing also had at least 10 future launch contracts withdrawn to the tune of ~$1B (1999). USAF investigations discovered that Boeing had lied extensively to the Air Force for more than four years – the actual volume of information stolen would balloon wildly from Boeing’s initial reports of “seven pages of harmless data” to 10+ boxes containing more than 42,000 pages of extremely detailed technical and proprietary information about Lockheed Martin’s Atlas V rocket proposal.
“If you rewind the clock 20 years, there were folks on a panel like this having dialogue about commercial launch, and there were envisioned several constellations that were going to require significant commercial launch. Lockheed Martin and Boeing set out to develop launch vehicles that were focused on that very robust commercial market – in the case of McDonald Douglas at the time, which later became Boeing, the factory in Decatur was…sized to crank out 40 [rocket boosters] a year, a couple of ships were bought to transport those…significant infrastructure put in place to address that envisioned launch market.” – John Elbon, COO, United Launch Alliance (ULA)
-
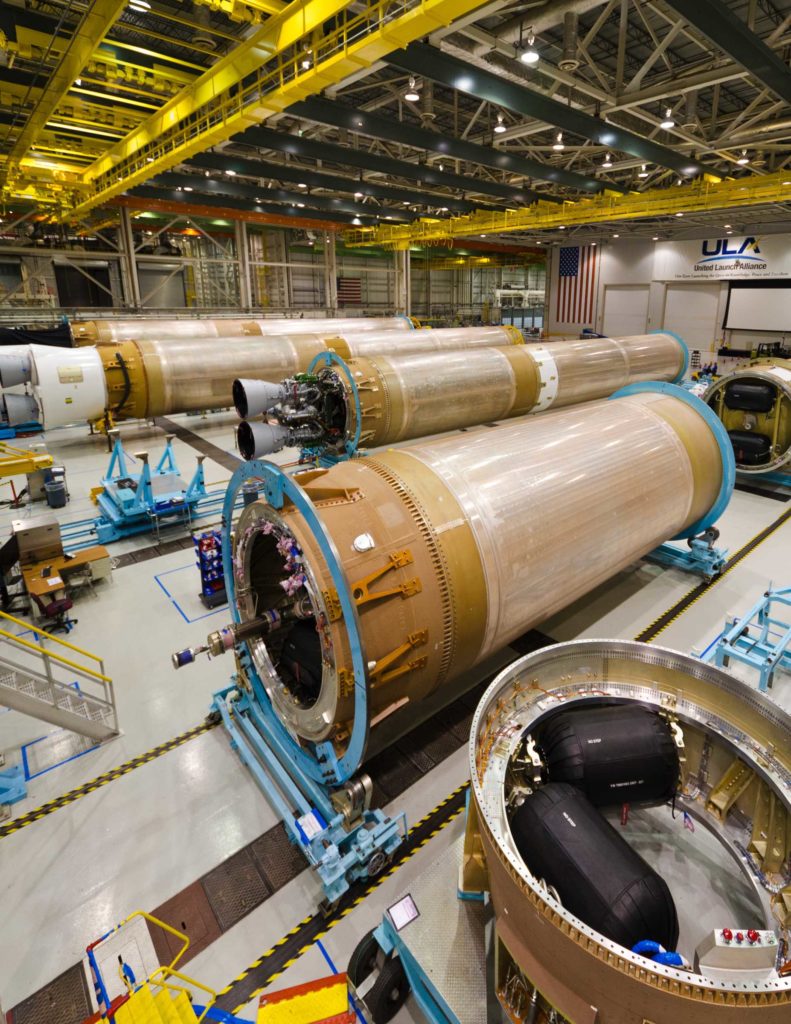
- ULA’s Decatur, Alabama factory now produces both Delta IV and Atlas 5. (ULA)
-
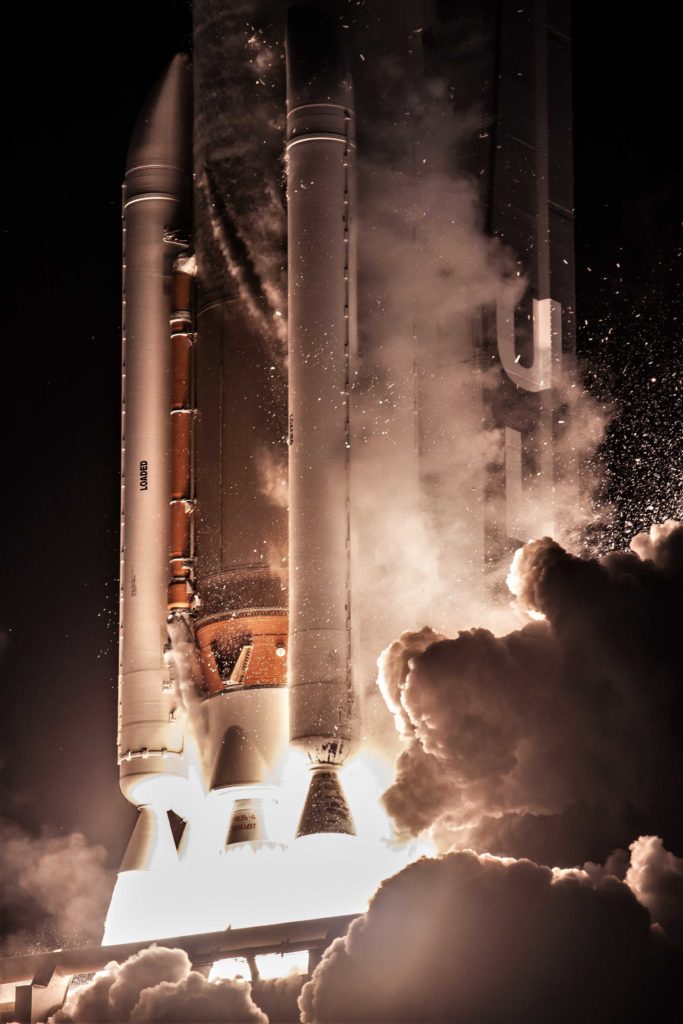
- ULA’s Atlas 5 launched AEHF-4 for the USAF earlier this month. (ULA)
In reality, Boeing was so desperate to secure USAF launches – despite the fact that it knew full well that Delta IV was too expensive to be sustainably competitive – that dozens of employees were eventually roped into a systematic, years-long, highly-illegal program of corporate espionage specifically designed to beat out government launch competitor Lockheed Martin. Humorously, Delta IV was not even Boeing’s design – rather, Boeing acquired designer McDonnell Douglas in late 1996, five days before the USAF announced the decision to reject Boeing and another company’s EELV proposals, narrowing down to two finalists (McDonnell Douglas and Lockheed Martin).
Seven years after the original lawsuit snowballed, Boeing settled with Lockheed Martin for a payment of more than $600M in 2006, accepting responsibility for its employees’ actions but admitting no corporate wrongdoing. Five years after that settlement, John Elbon became Vice President of Boeing’s Space Exploration division. This is by no means to suggest that Elbon is in any way complicit, having spent much of his 30+ years at Boeing managing the company’s involvement in the International Space Station, but more serves as an example of how recent these events are and why their consequences almost certainly continue to reverberate loudly within the US space industry.
SpaceX forces change
Worsened significantly by the consequences of Boeing’s lies about the actual operational costs of its Delta IV rocket (it had planned to secretly write off a loss on each rocket in order to steal USAF market share from LockMart), the commercial market for the extremely expensive rocket was and still is functionally nonexistent. 35 out of the family’s 36 launches have been contracted by the US military (30), NOAA (3), or NASA (2); the rocket’s first launch, likely sold at a major discount to Eutelsat, remains its one and only commercial mission.
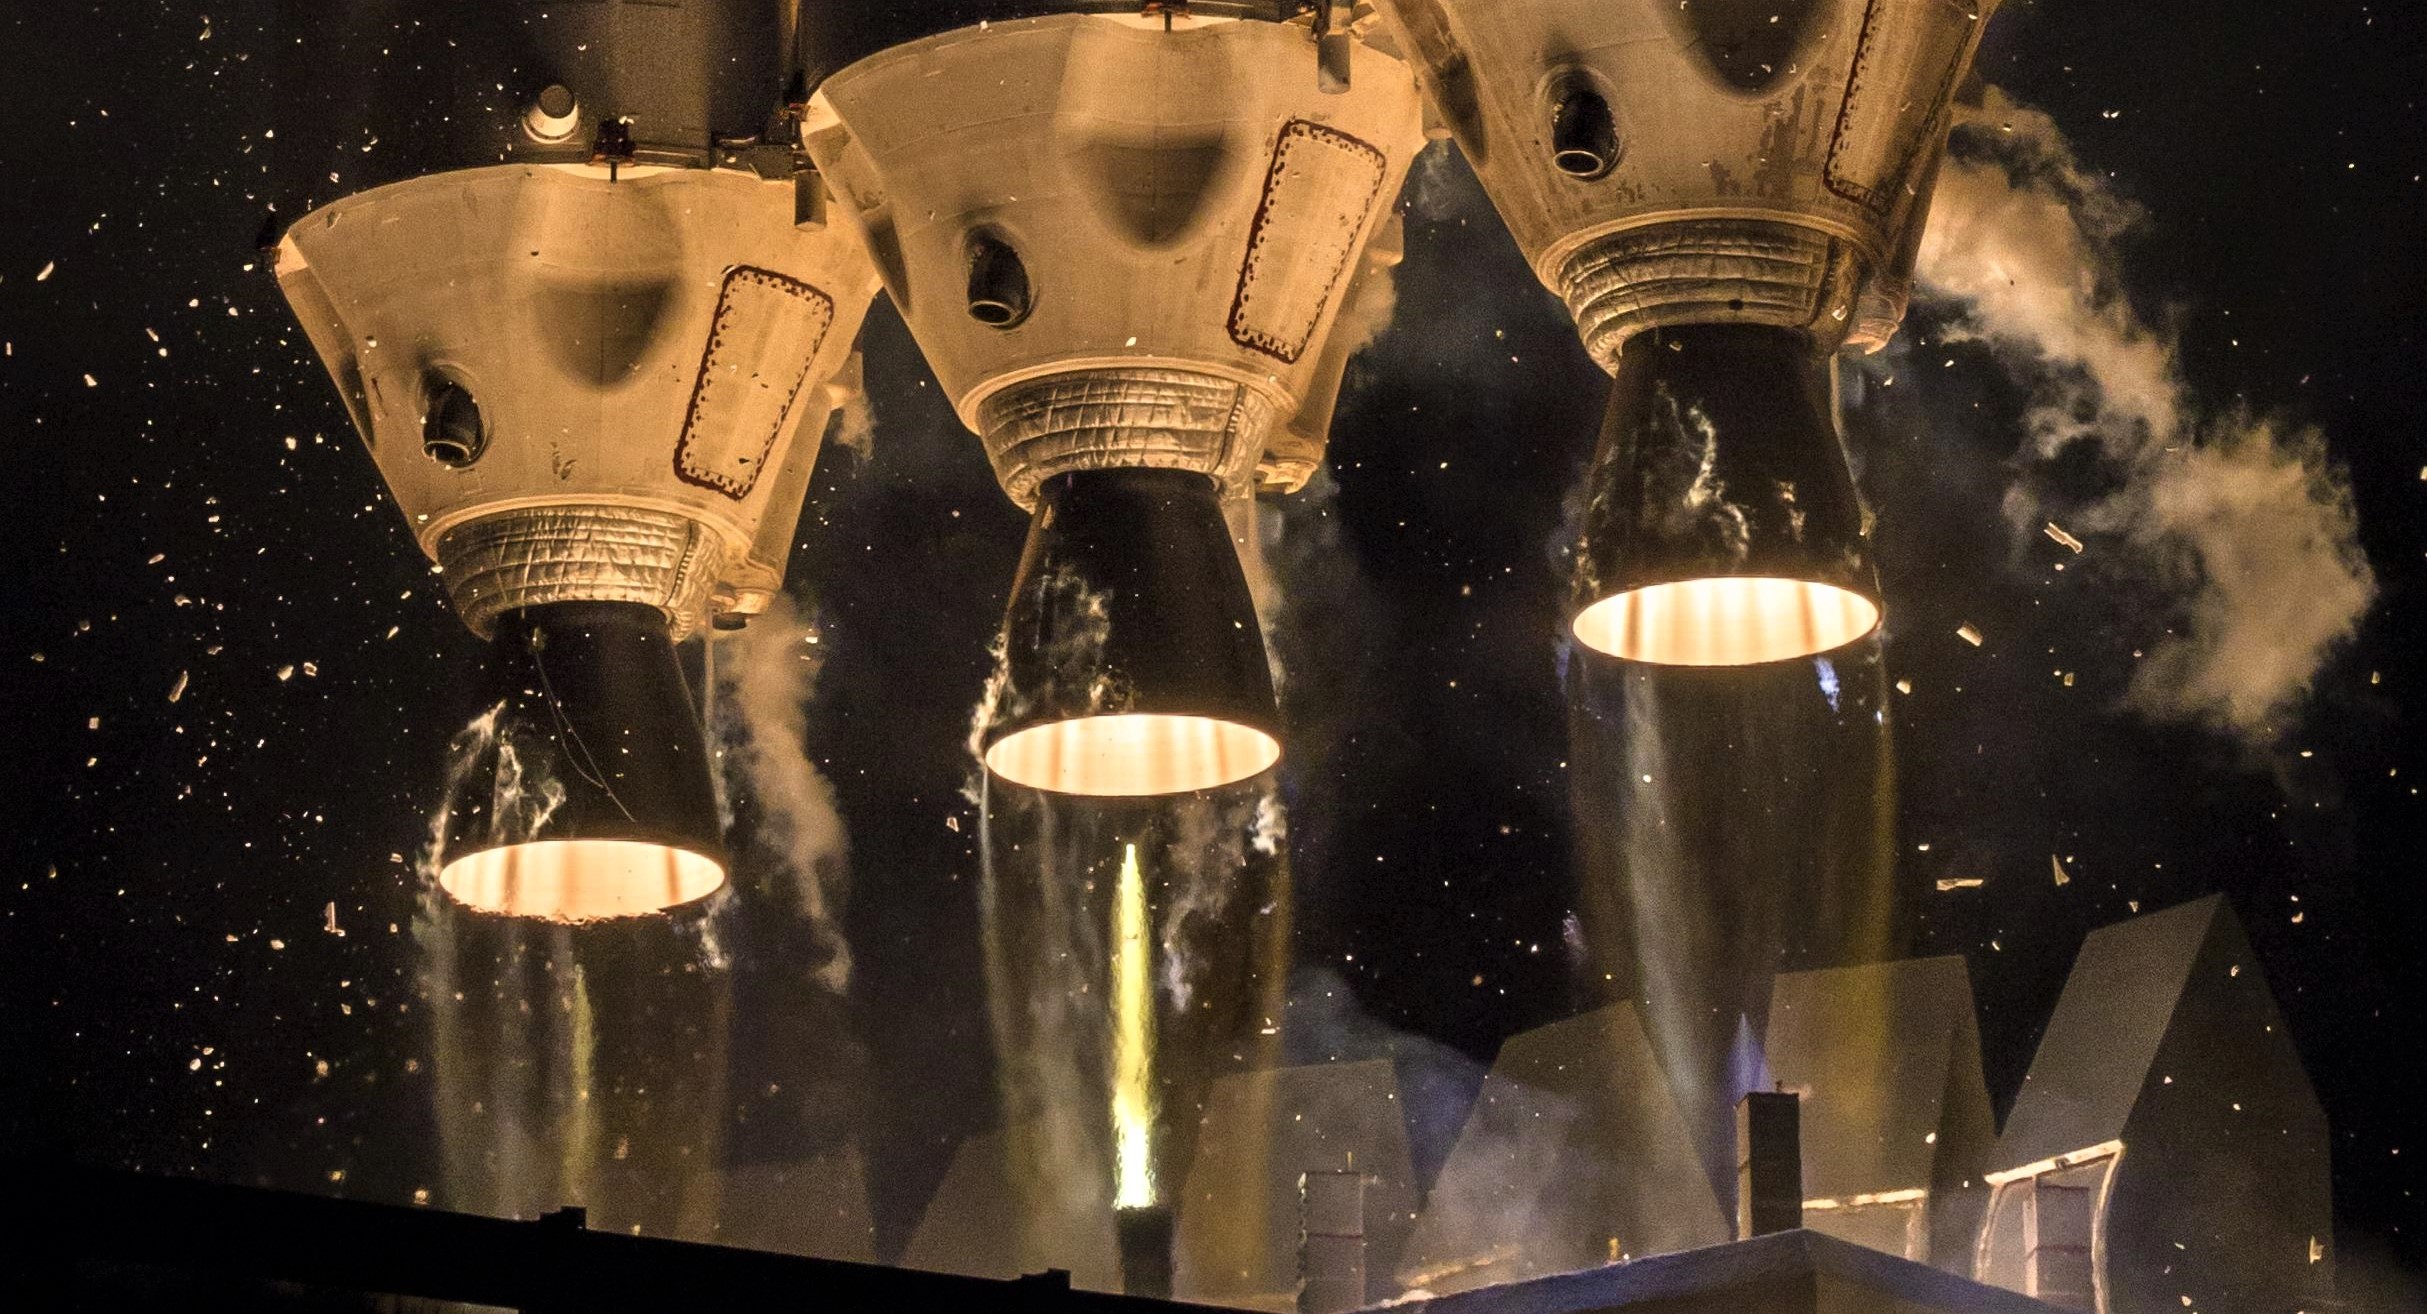
Atlas V, typically priced around 30% less than comparable Delta IV variants, has had a far more productive career, albeit with very few commercial launches since the Dec. 2006 formation of the United Launch Alliance. Since 2007, just 5 of Atlas V’s 70 launches have been for commercial customers. Frankly, although Atlas V was appreciably more affordable than Delta IV, neither rocket was ever able to sustainably compete with Europe’s Ariane 5 workhorse – Ariane 5 cost more per launch, but superior payload performance often let Arianespace manifest two large satellites on a single launch, approximately halving the cost for each customer. Russia’s affordable (but only moderately reliable) Proton rockets also played an important role in the commercial launch industry prior to SpaceX’s arrival.
After fighting tooth and nail for years to break ULA’s US governmental launch monopoly, SpaceX’s first dedicated National Security Space launch finally occurred less than a year and a half ago, in May 2017. SpaceX has since placed a USAF spaceplane and a classified NSS-related satellite into orbit and been awarded launch contracts for critical USAF payloads, most notably winning five of five competed GPS III satellite launches, to begin as early as mid-December. Falcon 9 will cost the USAF roughly 30% less than a comparable Atlas 5 contract, $97M to ULA’s ~$135M.
-
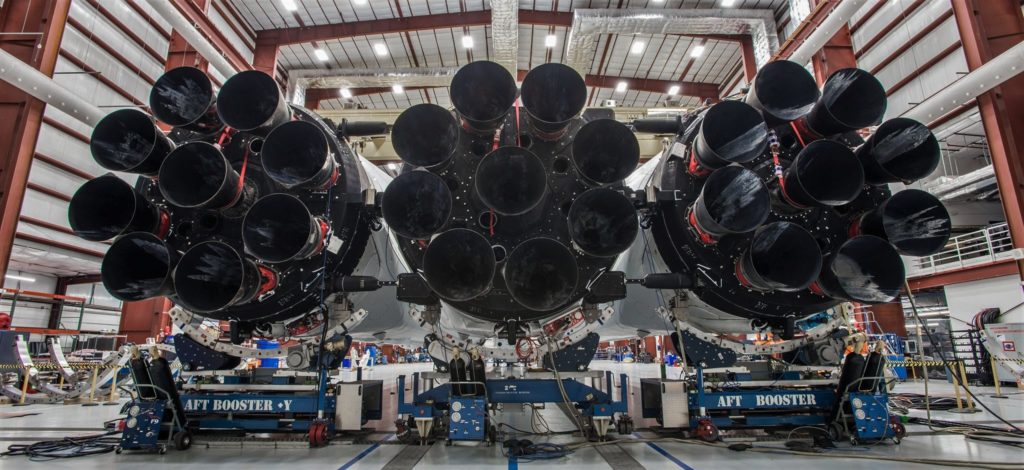
- The aft connection mechanisms on Falcon Heavy Flight 1 and Flight 2 appear to be quite similar. It’s possible that SpaceX has chosen to reuse aspects of the hardware recovered on Flight 1’s two side boosters. (SpaceX)
-
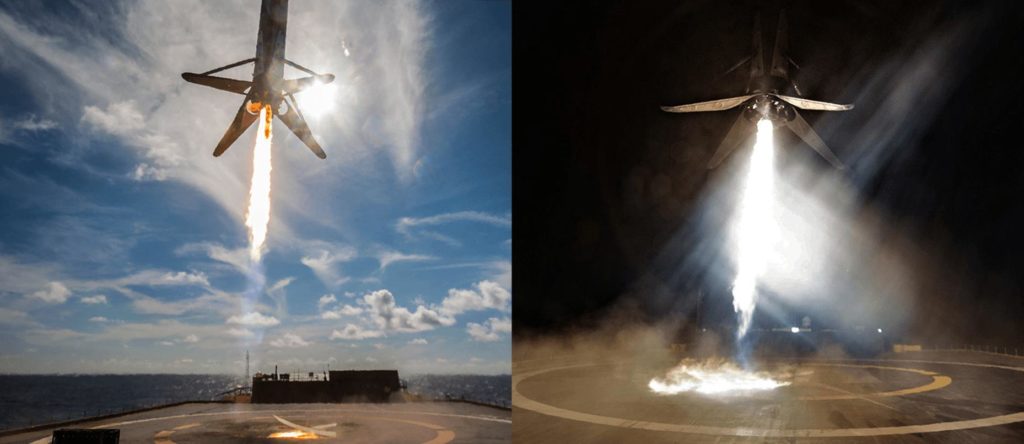
- Falcon 9 Block 5 booster B1046 seen during both of its post-launch landings. (SpaceX/SpaceX)
A bit more than two decades after Boeing bought McDonnell Douglas and began a calculated effort to steal trade secrets from Lockheed Martin, Elbon – now COO of the Boeing/Lockheed Martin-cooperative ULA – seems to fervently believe that the most critical mistake made in the late 1990s and early 2000s was the USAF’s decision to partially support the development of two separate rockets. Elbon concluded his remarks on the topic with one impressively unambiguous summary of ULA’s position:
“We have to make sure that we don’t get too much supply and not enough demand so that the [launch] providers can’t survive in a robust business environment, and then we lose the capability as a country to do the launches we need to do … [That’s] the perspective we have at ULA and it’s based on the experience that we’ve been through in the past.”
In his sole Delta IV vs. Atlas V case-study, what ULA now seems to think might have been “too much supply” under the USAF’s EELV program appears to literally be the fundamental minimum conditions needed for competition to exist at all – two companies offering two competing products. Short of directly stating as much, it’s difficult to imagine a more concise method of revealing the apparent belief that competition – at all – is intrinsically undesirable or risky.


Elon Musk said weeks ago during SpaceX’s third-quarter earnings call that the company’s Grok Bot, its autonomous AI Agent platform, was showing “the fastest growth of a product” that he’d ever seen in his life.
Now, SpaceXSI is scaling back Grok Bot users’ weekly limits, much to the surprise of those who have relied on it to take away monotonous tasks in their lives.
Elon Musk’s terse November 1 reply on X captured a sharp tension in the early days of agentic AI. Responding to a user who asked for a Grok Bot usage reset after hitting 100 percent with four days still left on the weekly cycle, Musk wrote: “The cost of serving Grok Bot was unsustainably high relative to revenue.”
@DogecoinNorway The cost of serving Grok Bot was unsustainably high relative to revenue
— Elon Musk (@elonmusk) November 1, 2026
The post arrived amid a wave of similar complaints from paying subscribers whose meters had jumped unexpectedly toward or to the limit, sometimes overnight and with little corresponding activity. It also stood in clear contrast to statements Musk had made only days and weeks earlier.
On the SpaceX third-quarter earnings call in mid-to-late October, Musk had described Grok Bot in almost the opposite terms. He called it “the fastest growth of a product that I’ve ever seen in my life” and said he had “never seen anything grow this fast.”
Company figures put paid weekly users at roughly 800,000 earlier in the month, more than doubling over the prior period. Daily active users had climbed from under 100,000 in early September to over 600,000 by late October.
Musk emphasized that the product has no free tier and that users appear to be getting real value beyond what they pay. In other remarks, he noted that usage per user was rising rather than declining, the opposite of the usual decay pattern for new software.
Grok Bot, launched around August, functions as an always-available agent with its own persistent cloud computer; it can schedule, research, shop, browse, and execute multi-step workflows even after the user steps away. Access is bundled into X subscription tiers (roughly $30, $100, and $200 per month) and certain Cursor plans, drawing from shared weekly usage pools whose exact sizes have not been publicly detailed.
The economics of that model are what Musk’s November 1 post put in the spotlight. Agentic systems burn far more compute than ordinary chatbot exchanges. Each task can trigger repeated model calls, tool use, web actions, and sustained background work.
When growth is as rapid as Musk celebrated, the absolute compute bill scales quickly even if average revenue per user stays fixed under flat monthly subscriptions. Industry observers noted the opportunity cost as well: the same GPUs can be rented to other AI labs at higher rates.
A simple back-of-the-envelope comparison circulating after the post illustrated the gap: if every reported daily user paid the top tier, annualized subscription revenue would still be modest relative to the scale of compute infrastructure SpaceX is building and leasing to companies like Anthropic.
Some users also reported possible dashboard anomalies around the same period, though Musk’s framing treated the underlying cost-revenue imbalance as the core issue rather than a pure metering glitch.
The juxtaposition is the core of this exchange. Within roughly two weeks of publicly framing Grok Bot as an unprecedented success with strong unit economics and no free tier, Musk acknowledged that serving the same product had become unsustainable relative to the revenue it generates.
For the broader industry, the episode underscores a structural challenge of the agent era: demand is real and growing faster than many expected, yet the cost of fulfilling that demand through always-on, multi-step agents can outrun subscription pricing before companies can adjust limits, introduce metered billing, or raise prices.
Musk’s reply did not promise an immediate reset or higher allowances; it simply stated the constraint. In doing so, it supplied a rare, explicit public data point on the unit economics of a high-profile AI agent just as adoption numbers were still being celebrated as the fastest in Musk’s experience.
The tension between rapid, paid growth and the compute required to deliver it is now on the record.
News
Tesla owners who tap Emergency Drive Away for fun are in for a surprise
Tapping Activate on Tesla’s Emergency Drive Away reportedly triggers a $539 service bill without moving.

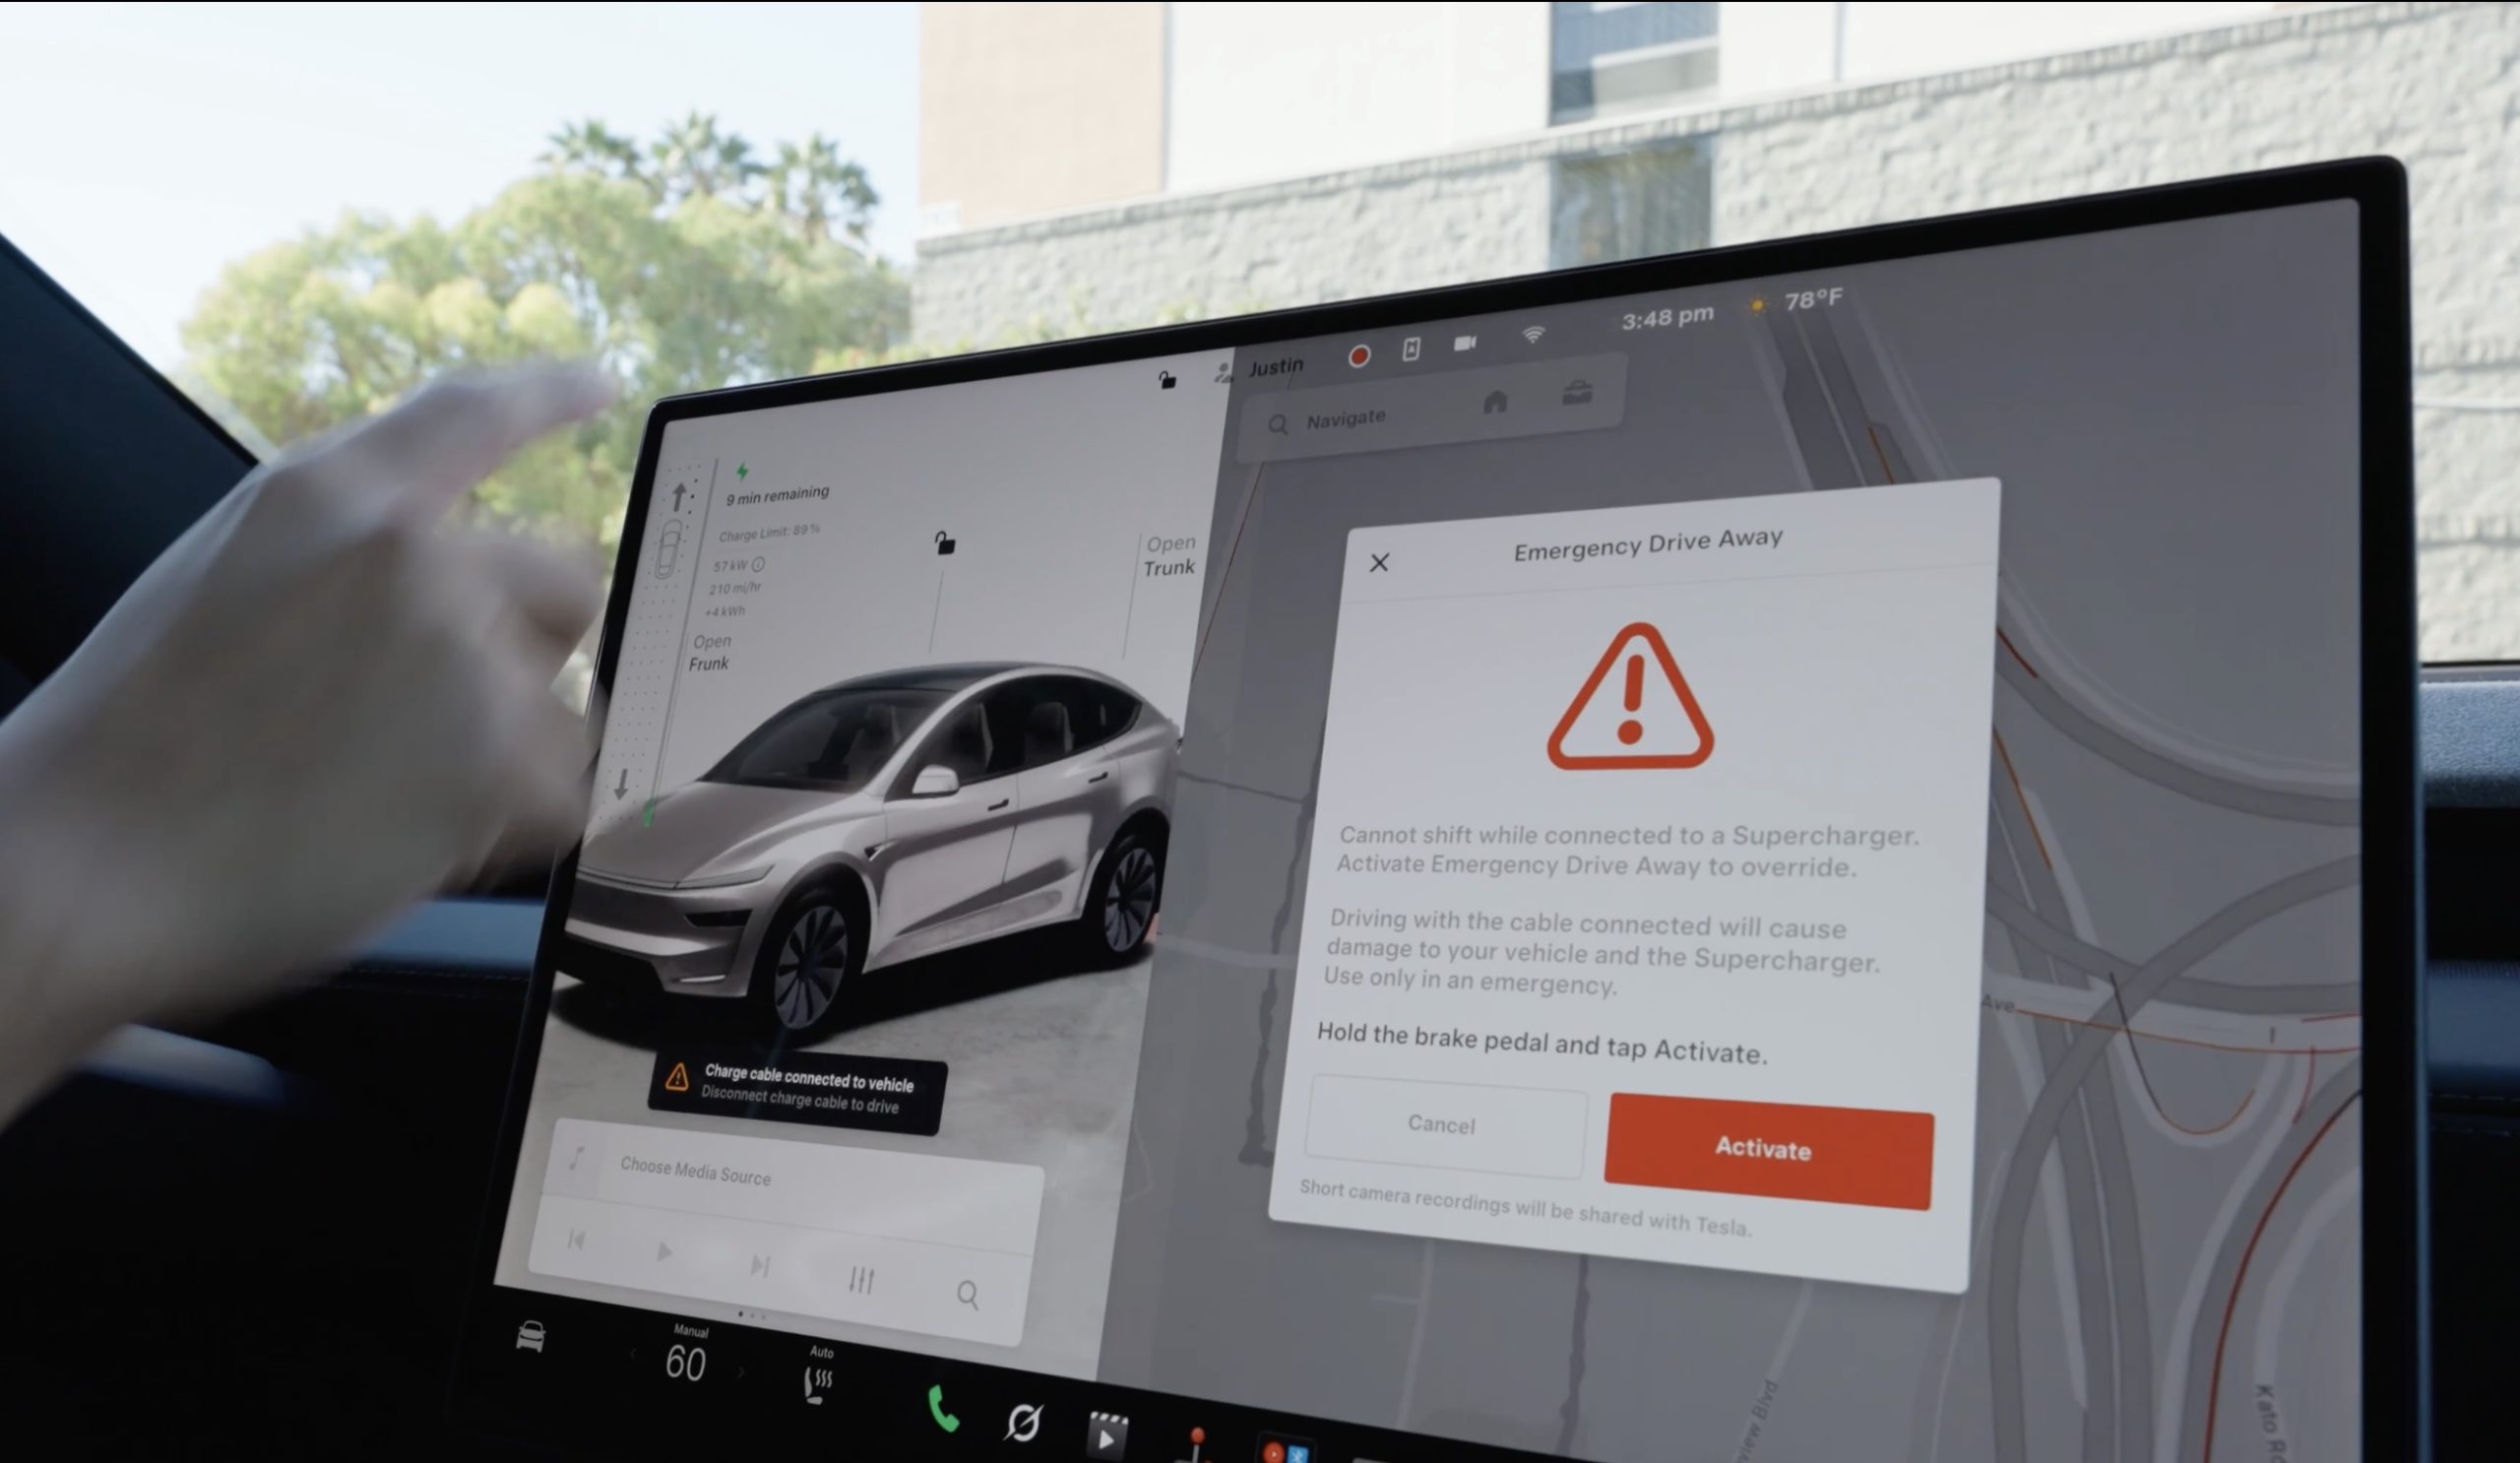
Tesla owners who press Activate on Emergency Drive Away may be on the hook for a service bill even if their car never leaves the Supercharger stall.
Yaro, who posts about Tesla service cases on X as @Tutrifour, said a customer called after tapping Activate while still plugged into a Supercharger. The owner was about to pull away, remembered the cable was still connected and stopped. The car never moved, but the touchscreen showed a red alert reading “Emergency Drive Away has been activated” with “Service is required” underneath. A Service Mode screenshot showed the active alert BMS_a228_EmergencyDriveAwayServiceRequired, which Yaro said only Tesla Service can clear.
Here is a lesson to Tesla owners. Don’t press Activate on the new Emergency Drive Away feature on your Tesla because service charges $539 to inspect the charge port and to clear the alert. Yes, even if you didn’t move the car an inch. https://t.co/NZJENw4SQv
— Yaro (@Tutrifour) October 30, 2026
The cost of clearing it was the bigger surprise. “Don’t press Activate on the new Emergency Drive Away feature on your Tesla because service charges $539 to inspect the charge port and to clear the alert. Yes, even if you didn’t move the car an inch,” Yaro wrote. The $539 figure comes from that single case, and Tesla has not published a set price for the inspection or commented on the post. Yaro also noted that the car would still charge with the alert on screen.
Tesla launched Emergency Drive Away on October 1 with software update 2026.38.3, letting drivers pull away from a U.S. Supercharger with the cable still attached, as Teslarati reported. To use it, a driver shifts into Drive while connected, holds the brake and taps Activate. The prompt warns that driving with the cable connected will damage the vehicle and the Supercharger, and that short camera recordings will be shared with Tesla.
Tesla Charging has been clear about what follows a real activation. Repairs to a Supercharger stall can run up to $25,000 depending on the site, a service visit for the car’s charge port is mandatory, and deliberate misuse “will invoke additional penalties.” What the company had not spelled out is that the service requirement is triggered the moment Activate is pressed, not the moment the cable breaks away.
From an engineering standpoint, that is the cautious choice. Once Activate is pressed, the car cannot be sure the charge port latch was not stressed, so flagging it for inspection removes the guesswork. It also means the button carries a price on its own, which is a stronger deterrent against casual use than any warning screen.
Customer called because they have an active alert after tapping ACTIVATE on the new Emergency Drive Away feature. They didn’t actually drive away but were about to until they “remembered” they had the charge cable connected.
This alert can only be cleared by Tesla Service. https://t.co/SkHyJJPFwU
— Yaro (@Tutrifour) October 28, 2026
The report follows the feature’s first known real world use, when a driver in Austin during F1 weekend appeared to trigger it by accident and dragged the Supercharger cable along with the car. The Reddit user who filmed it said the driver seemed to have only half read the prompts.
For owners, the takeaway is to treat the red prompt as a stop sign. If it appears after shifting out of Park by mistake, shift back and unplug the normal way from the touchscreen, the Tesla app or the button on the charge handle. Activate is meant for moments when staying at the stall is the bigger risk, and Tesla is now pricing it that way.
Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.
Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.

Grok Bot users hit with weekly limits early, Elon Musk explains what happened

Tesla owners who tap Emergency Drive Away for fun are in for a surprise


