Investor's Corner
OPINION: Analysts miss the mark on Tesla following Q3 Delivery Guidance

This is a preview from our weekly newsletter. Each week I go ‘Beyond the News’ and handcraft a special edition that includes my thoughts on the biggest stories, why it matters, and how it could impact the future.
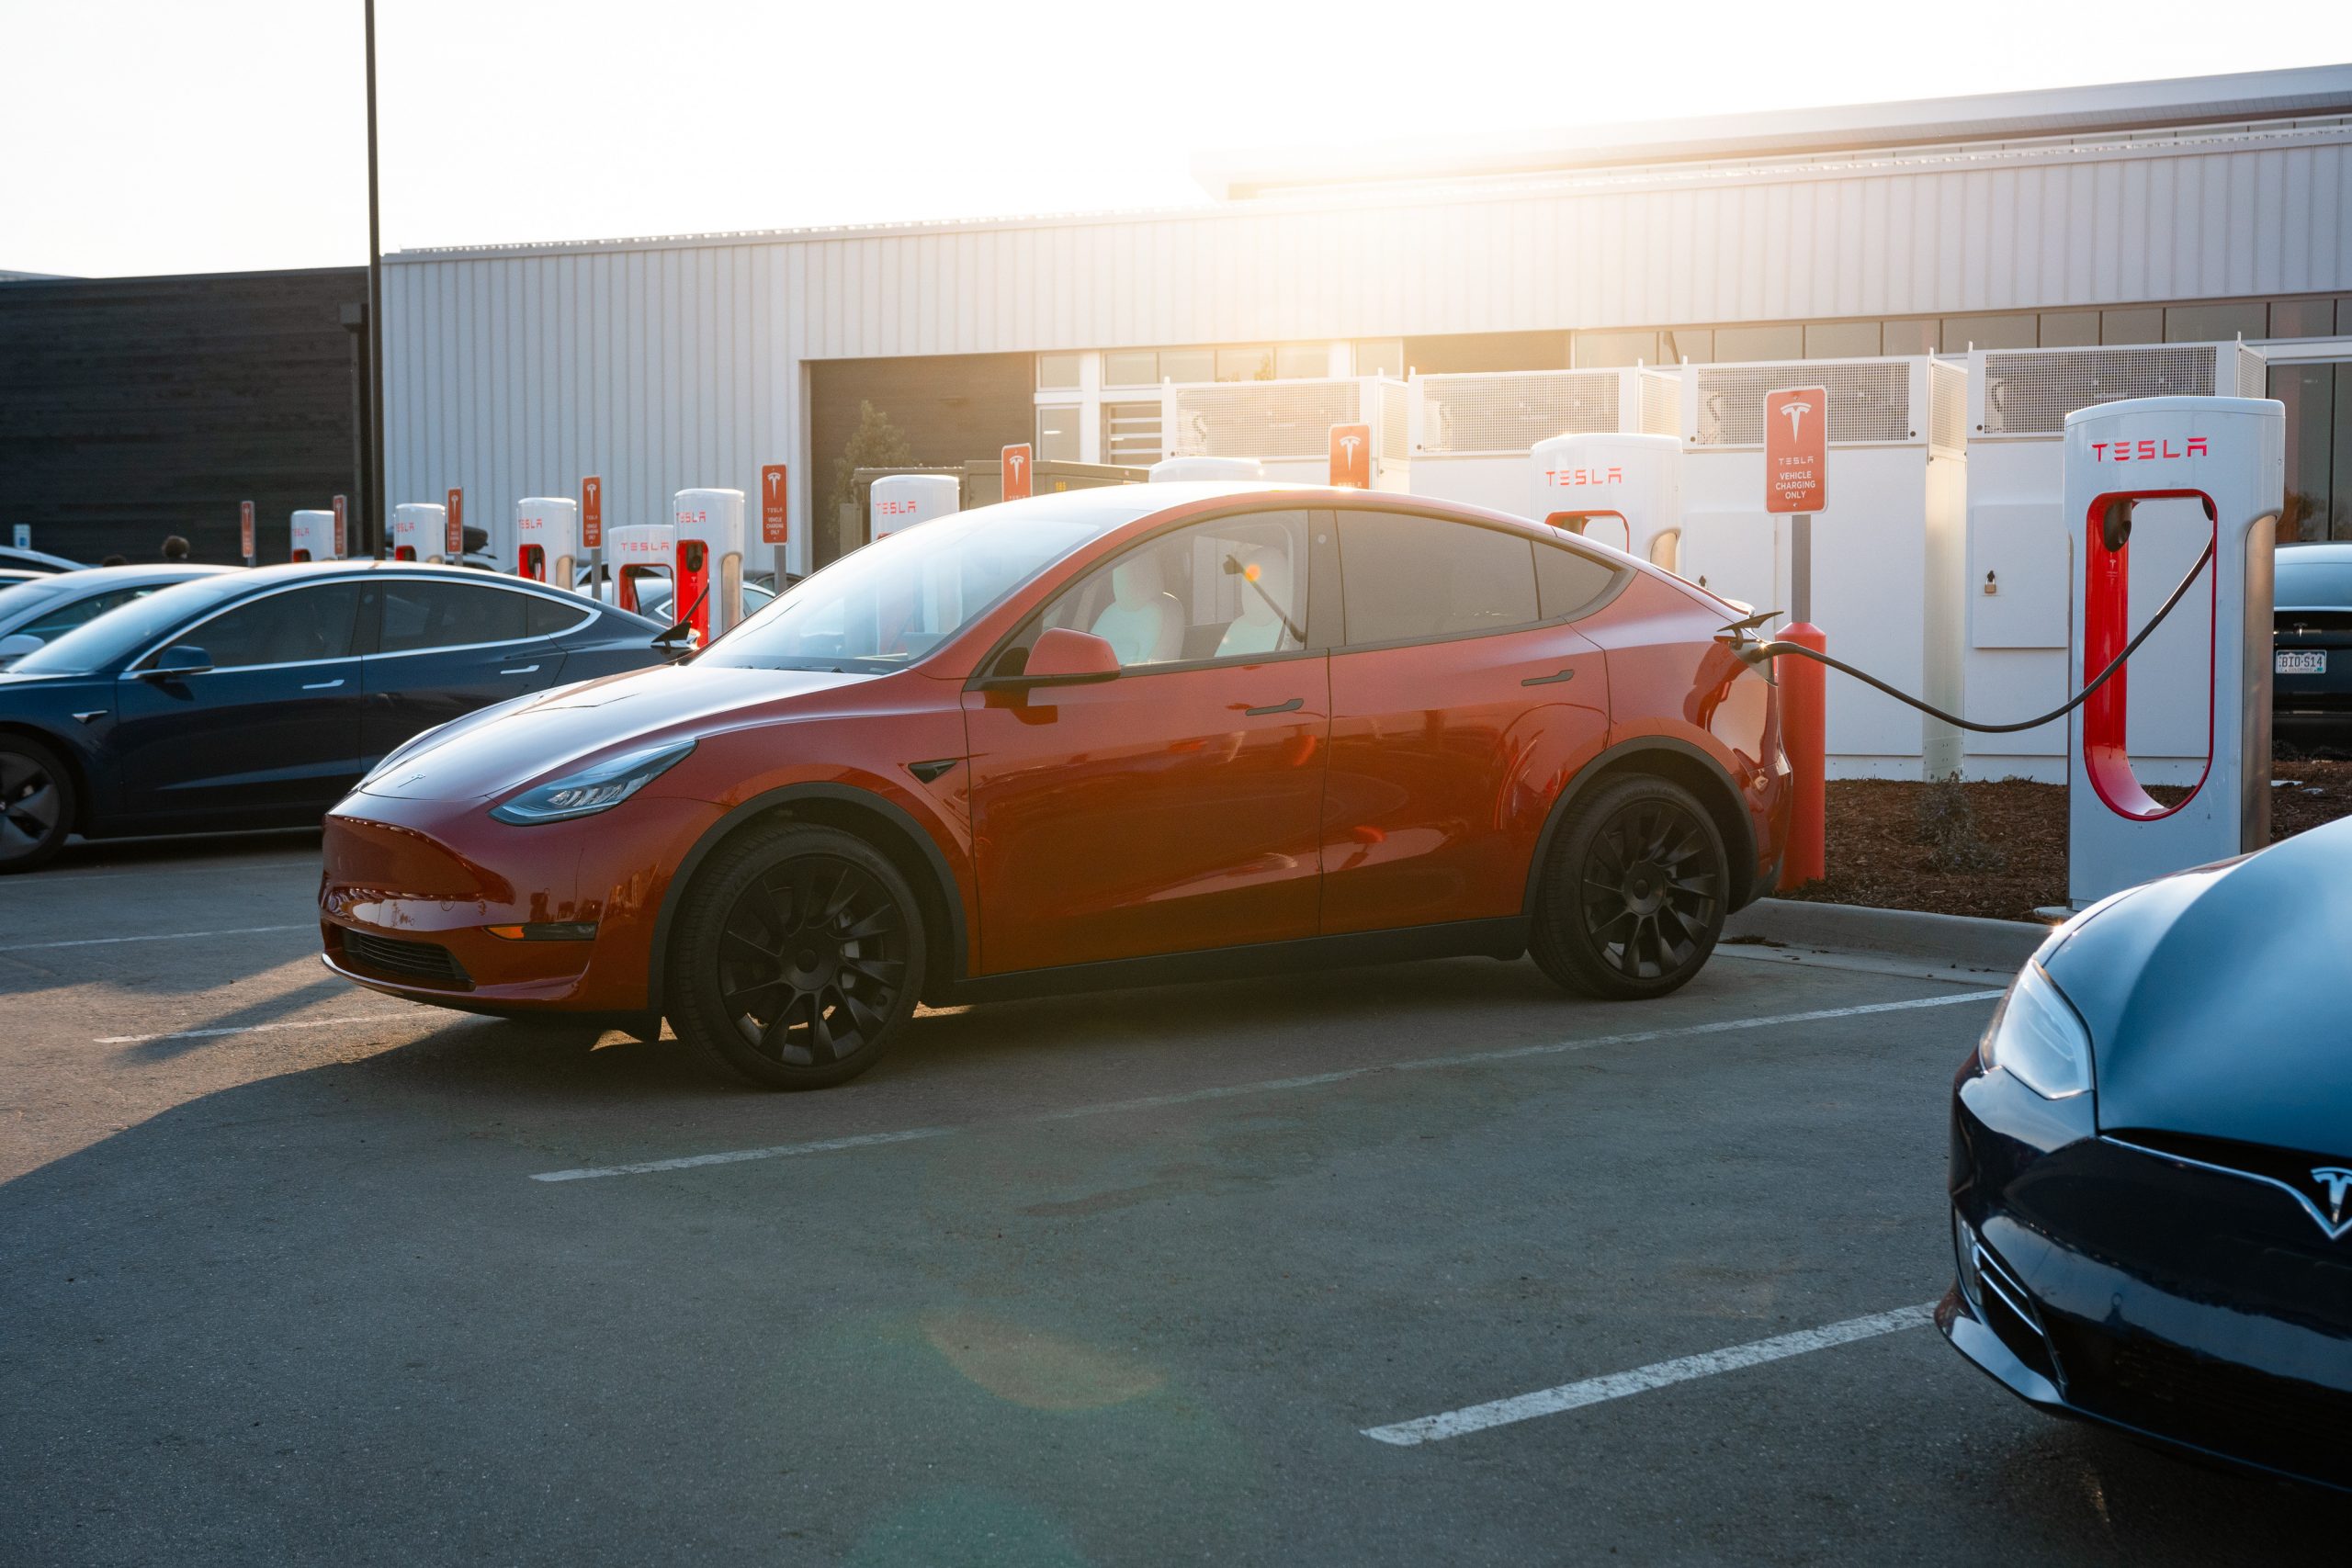
Tesla is coming off its most successful quarter in company history. The Q3 delivery guidance saw Tesla deliver over 241,000 vehicles for the first time in company history, with production at a slightly lower rate than that. However, despite the bullish outlook for Tesla from a retail investor standpoint, analysts and media continue to miss the mark on the company, believing in their breakdowns that the automaker’s growth story will begin to stagnate. However, Tesla is averting several crises simultaneously, including parts shortages and opening new facilities.
The consistently baffling thing to me as a journalist and reporter that has covered the sector for over two years is that analysts continue to sit on a hill, ready to die on it. Just because they have been outspoken when writing notes regarding their negative outlooks on Tesla stock or deliveries, they are unwilling to admit their wrongs, for the most part. Tesla has continued a growth story that is one of the most impressive in perhaps the long and storied history of the automotive industry.
I’m not an analyst. I did work in finance before I ventured into writing for a career, but I am in no way an analyst or seasoned investor of any kind. However, I do recognize that there are obvious shortcomings in the descriptions of Tesla by some analysts, unwilling to give credit where credit is due. Tesla has been the only car company on Earth that has been able to avert the semiconductor shortage through in-house measures and efforts. Tesla’s software team absolutely killed it with the development and production of microcontrollers that would assist with the company’s efforts to avoid a production stoppage. Yet, despite all of this effort and hard work and dedication by Tesla’s highly talented team of engineers, there is relatively no credit given by analysts apart from Morgan Stanley’s Adam Jonas, who was baffled at the company’s ability to avoid the chip shortage.
Tesla delivers record 241,300 cars in Q3, handily beating consensus estimates
Meanwhile, other automakers like Ford, who have adopted EVs partially with their release of the Mustang Mach-E and eventual releases of the F-150 Lightning and E-Transit van, are experiencing drops in deliveries. Ford had a 23% drop in pickup truck deliveries, despite the F-150 being the most popular truck in the U.S. market. While SUV sales did rise 3.4% compared to Q2, the drop in pickup trucks is evidently a result of the chip shortage, as many manufactured but incomplete pickups sit in lots surrounding the company’s production facilities waiting for chips.
I don’t know this for a fact, but I feel as if mainstream media outlets would be singing the praises of companies like Ford, Chevy, GMC, or Honda if these companies were able to produce chips on their own and avoid the semiconductor issues. I do not necessarily like being accusatory of other media outlets, and I do not like going out of my way to believe that journalists have some kind of inside agenda. I believe all of us have a duty to remain fair and balanced and unbiased. But let’s be honest here, Tesla is not getting the attention or the credit it deserves. The semiconductor shortage is plaguing so many industries, and Tesla is averting it completely, somehow.
Companies are declining while Tesla has already reported eight consecutive profitable quarters, going for its ninth. We will find out if Tesla was profitable in Q3 next week during the Earnings Call on October 20th. However, the ability to conduct such consistent growth through deliveries in somewhat incredible, and I truly believe analysts are doing themselves and their clients a huge disservice by ignoring or avoiding such a tremendous growth story during such a trying time. Many of them will live to regret their decisions, whether it’s paid inside interests or a personal vendetta.
I think there is a reason many analysts with bullish Tesla outlooks are ranked so highly on TipRanks, while those who continue a bearish outlook are ranked tremendously low.
A big thanks to our long-time supporters and new subscribers! Thank you.
I use this newsletter to share my thoughts on what is going on in the Tesla world. If you want to talk to me directly, you can email me or reach me on Twitter. I don’t bite, be sure to reach out!
-Joey

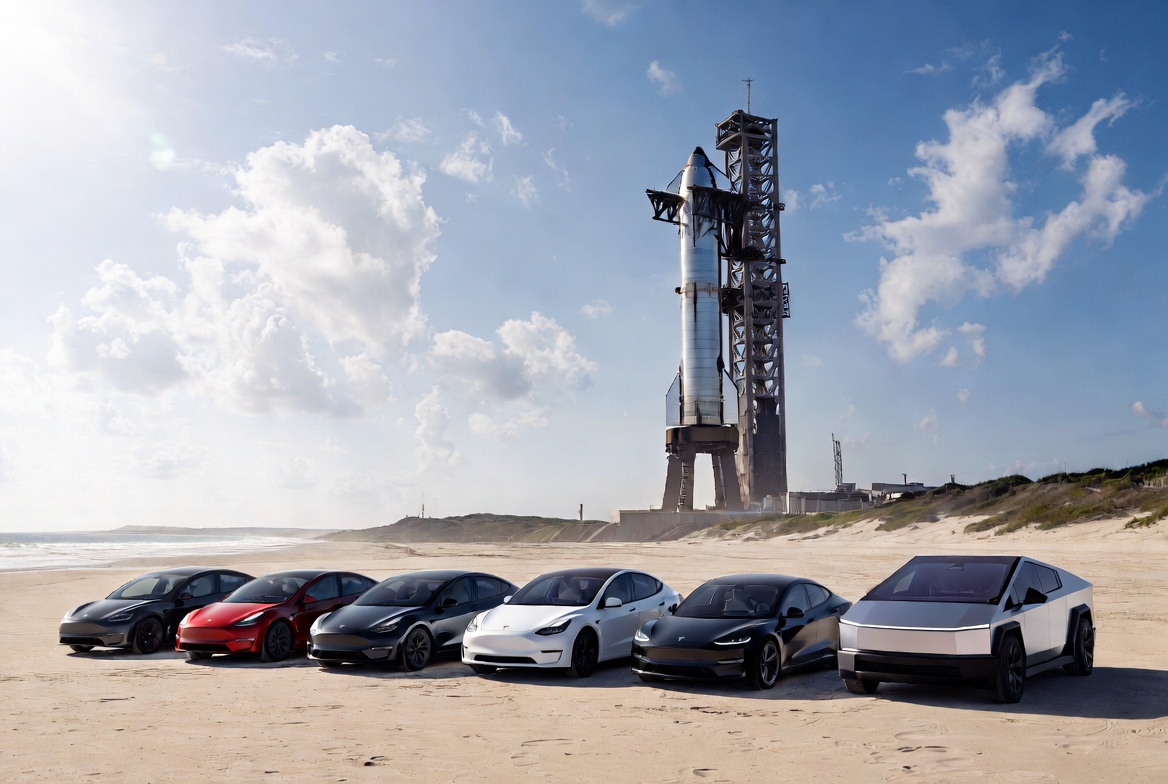
Tesla and SpaceX shares fell on Wednesday after Democrats swept both chambers of Congress. The decline stood out as broader market securities recovered and turned positive, while both of Musk’s publicly traded companies lagged.
CEO Elon Musk already joked about the unsuccessful campaigning for the Republicans, but now the new party will make pretty drastic changes to how it handles Tesla and SpaceX, and those companies will adjust their outlook.
Let’s take a deeper look.
Tesla ($TSLA)
Tesla shares traded lower during the regular session after Democrats secured both the House and Senate. The stock was down 2.32 percent at around 1:45 p.m. on the East Coast, trading at around $389.30.
The pressure is tied to more than the raw scale of Musk’s political spending, estimated at $450–474 million this cycle with roughly $224 million directed at Texas. In that state, Tesla now faces a Democratic governor and a Democratic senator after Gina Hinojosa unseated Greg Abbott and James Talarico defeated Ken Paxton.
The Austin Gigafactory, Robotaxi pilot programs in multiple Texas cities, and any related AI compute expansion sit under a new state executive who campaigned against certain corporate subsidies and floated a moratorium on new data-center construction.
Federally, Democratic control of key committees opens the door to deeper examination of Tesla’s autonomous-driving safety record, federal energy-storage and manufacturing incentives, and the national-security implications of any combination with SpaceX.
Investors are also weighing whether the company’s historically close alignment with the prior Republican leadership will invite slower permitting, additional hearings, or tighter rules on Full Self-Driving deployment.
For Tesla, the political shift adds near-term friction around state permitting and federal regulatory approvals for autonomy and energy storage. A potential merger with SpaceX may face slower review even if it proceeds.
Core growth drivers such as vehicle deliveries, energy deployments, and robotaxi rollout remain intact, yet the stock now carries a higher political-risk premium that could weigh on valuation until the company demonstrates workable relationships with the new Texas leadership and congressional majorities.
SpaceX ($SPCX)
SpaceX shares also declined in live trading on November 4 following the Democratic midterm sweep. The stock traded at $134.97, down 4.49 percent. The drop occurred even as broader indexes stabilized, highlighting a company-specific reaction to the election outcome.
Musk’s large contributions, concentrated in Texas races that both companies lost, place SpaceX’s Starbase launch facility and headquarters under a new Democratic governor.
At the federal level, Democratic control of Congress enables greater scrutiny of NASA, the Department of Defense, and other contracts that support a meaningful share of revenue, along with reviews of Starlink national-security uses and any Tesla merger. Analysts have noted that empowered committees can hold hearings and request documents on these relationships.
For SpaceX, the results raise the risk of delayed contract awards, higher compliance costs, and tighter constraints on AI and satellite infrastructure expansion, particularly in Texas where a data-center moratorium has been discussed.
A merger with Tesla could encounter political friction that slows integration of launch, connectivity, and autonomy capabilities.
While Starlink growth and launch cadence continue as primary drivers, the company faces a more contested path for federal funding and state-level operations, requiring management to rebuild ties with the new congressional majorities and Texas leadership to limit the overhang.
Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.

Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.
Elon Musk
SpaceX President to gift Trump Accounts her SpaceX stock
Gwynne Shotwell’s 2 million SpaceX shares are headed to children’s Trump Accounts starting this December.
SpaceX President Gwynne Shotwell said Friday that more than 2 million SpaceX shares belonging to her and her husband, Robert, will be distributed to children’s Trump Accounts in December, turning a pledge she made over the summer into an actual transfer. “Robert and I are thrilled that our gift of over 2 million shares of SpaceX stock will be distributed to children’s Trump accounts in December!” Shotwell wrote on X, adding that the shares are “transferring to escrow as we speak.”
The first round goes to children aged 11 to 17 who live in ZIP codes where the median family income is $57,000 or less, along with kids in ZIP codes with too few residents for the Census to report that figure. Shotwell said those families should receive a notice by Monday, Reuters reported.
A second gift is expected to be finalized in the next few weeks. That round will cover eligible children in military families serving overseas, children in foster care, and more kids in Texas counties near the Shotwells’ home where median family income is $90,000 or less. Elon Musk replied to the announcement with “Cool” and a heart emoji.
Shotwell first announced the donation on July 6, less than a month after SpaceX priced its record IPO at $135 per share on the Nasdaq. IPO filings showed Shotwell owned about 12.6 million SpaceX shares, Quartz reported at the time, which makes the gift roughly one sixth of her stake. At the roughly $146 per share used to value Musk’s own pledge earlier this month, 2 million shares are worth about $290 million.
How the stock would actually reach the accounts had been an open question since July. Treasury guidance acknowledged that stock donations could flow into Trump Accounts, but it did not explain the mechanics for a program whose contributions default into an S&P 500 index fund. Shotwell thanked the Treasury, the IRS, the Dell Foundation, Greater Horizons, Invest America and the law firms Morgan Lewis and Gibson Dunn for “working over the past few months to make this happen.”
The transfer also works as a dry run for a far larger gift. On October 19, Musk said he would give one of his SpaceX shares to every kid in America next year and called it “the first of many.” With roughly 72 million children in the country, that pledge is worth about $10.5 billion. President Donald Trump thanked Musk the same day and said the shares would go through Trump Accounts, though neither SpaceX nor the Treasury has published how or when that distribution will happen.
Shotwell’s recipients also fill a gap in the program itself. Trump Accounts launched on July 4, and the $1,000 Treasury deposit only goes to babies born between 2025 and 2028. Teenagers aged 11 to 17 receive no government seed money, so for many of the families getting a notice on Monday, SpaceX stock will be the first asset in the account. The accounts convert into retirement accounts when the child turns 18.

Ferrari Luce sold out for 2027 after design controversy

Musk’s Tesla and SpaceX decline after Democratic Midterm sweep


