Investor's Corner
Tesla (TSLA) Q2 2019 production and delivery report: What Wall St analysts are saying

Tesla stock (NASDAQ: TSLA) is surging on Wednesday on the heels of the release of the company’s Q2 2019 delivery and production report. With deliveries and production far exceeding forecasts from Wall St, several analysts have weighed in on the electric car maker’s record-setting quarter, which saw Tesla producing a total of 87,048 vehicles, comprised of 14,517 Model S and Model X, and 72,531 Model 3; and delivering a total of 95,200 cars, comprised of 17,650 Model S and X and 77,550 Model 3.
Morgan Stanley analyst Adam Jonas, who quoted a “worst case” $10 price target on TSLA stock back in May, admitted that despite the number of leaked Elon Musk emails and reports pointing to a record quarter, Tesla’s over 95,000 vehicle deliveries were unexpected. “We had not spoken to any investors that expected deliveries to be this high. We expect the stock to squeeze and then fade on this news,” Jonas wrote in a note. Nevertheless, the analyst still pointed out that continued concerns about “sustainable” demand and competition in regions such as China would likely weigh down the stock.
“It isn’t clear how much of the beat was due to underlying demand, more attractive pricing, sales bonuses, or pull-forward from (the) third quarter after tax credit reduction. Based on year-to-date deliveries, if Tesla achieves 95,000 units in the third and fourth quarters, it would take them to about 350,000 units for 2019, just shy of guidance of 360,000-400,000 units,” Jonas, who currently has an Equalweight rating on Tesla stock with a price target of $230 per share, noted.
Nomura analyst Christopher Eberle, who has a Neutral rating and a $300 price target for TSLA, also weighed in on the electric car maker’s Q2 results. “Tesla noted that orders generated during the quarter exceeded deliveries, implying the company enters 3Q19 with an increase in its backlog,” he stated. Eberle remained cautious, adjusting his third-quarter delivery estimate by just 5% to 80,000 units.
Joseph Osha of JMP Securities, who maintains a Market Perform rating and a $347 price target on the electric car maker, stated that he expects to see Tesla’s cash balance rise to $2.67 billion in the second quarter. Osha also argued that the second quarter results prove that the company’s lower-than-expected first quarter figures were not an indicator of real end demand in the United States. “Overall, the message we hear is that Tesla’s weak first quarter was not, in fact, an indicator of real end demand in the U.S. market. The combination of U.S. demand and export volume appears sufficient to support an outlook of ~380,000 deliveries this year, and our outlook for the second half of the year remains unchanged,” the analyst stated.
Wedbush Securities analyst Daniel Ives, who has a Neutral rating and a $230 price target on Tesla stock, noted that the company’s strong Q2 delivery numbers were “a clear step in the right direction,” which could help restore the credibility of Elon Musk’s story. Ives was among the most vocal critics of Tesla following its first-quarter results, at one point calling Q1’s results “one of (the) top debacles we have ever seen.” Ives also mocked Tesla for maintaining its optimistic forecast for the rest of 2019, stating that “Musk & Co., in an episode out of the Twilight Zone, act as if demand and profitability will magically return to the Tesla story.” Prior to the release of Tesla’s Q2 2019 production and delivery report, Ives expected the company to deliver 84,001 vehicles.
Goldman Sachs analyst David Tamberrino, one of TSLA’s most ardent critics who currently has a Sell rating and a $158 price target on the electric car maker, stood by his pessimistic outlook on the company. Tamberrino stated that “second-quarter deliveries and order flow were helped by the release of Tesla’s Standard Model 3 variant, right-hand drive Model 3s and the upcoming phasing out of U.S. tax incentives.” The Goldman Sachs analyst also expects a “sequential” stepdown in demand in the third quarter, on account of Tesla’s decision to offer lower-priced Model 3 variants and a leasing option, which he notes could have negative impacts on the vehicle’s gross margins and FCF generation. Interestingly, Tamberrino expected Tesla to deliver 91,124 vehicles in the second quarter (one of the highest on Wall Street, exceeding even that of Tesla bull and Baird analyst Ben Kallo), which is quite ironic considering his constant pessimistic stance against the electric car maker. Goldman Sachs’ investment bank is also among TSLA’s prominent shareholders.
As of writing, Tesla stock is trading +6.13% at $238.31 per share.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.


Investor's Corner
Elon Musk drops a Thanksgiving hint about Starship’s biggest test yet
Elon Musk says Starship Flight 15 will try to catch the ship itself, a first.

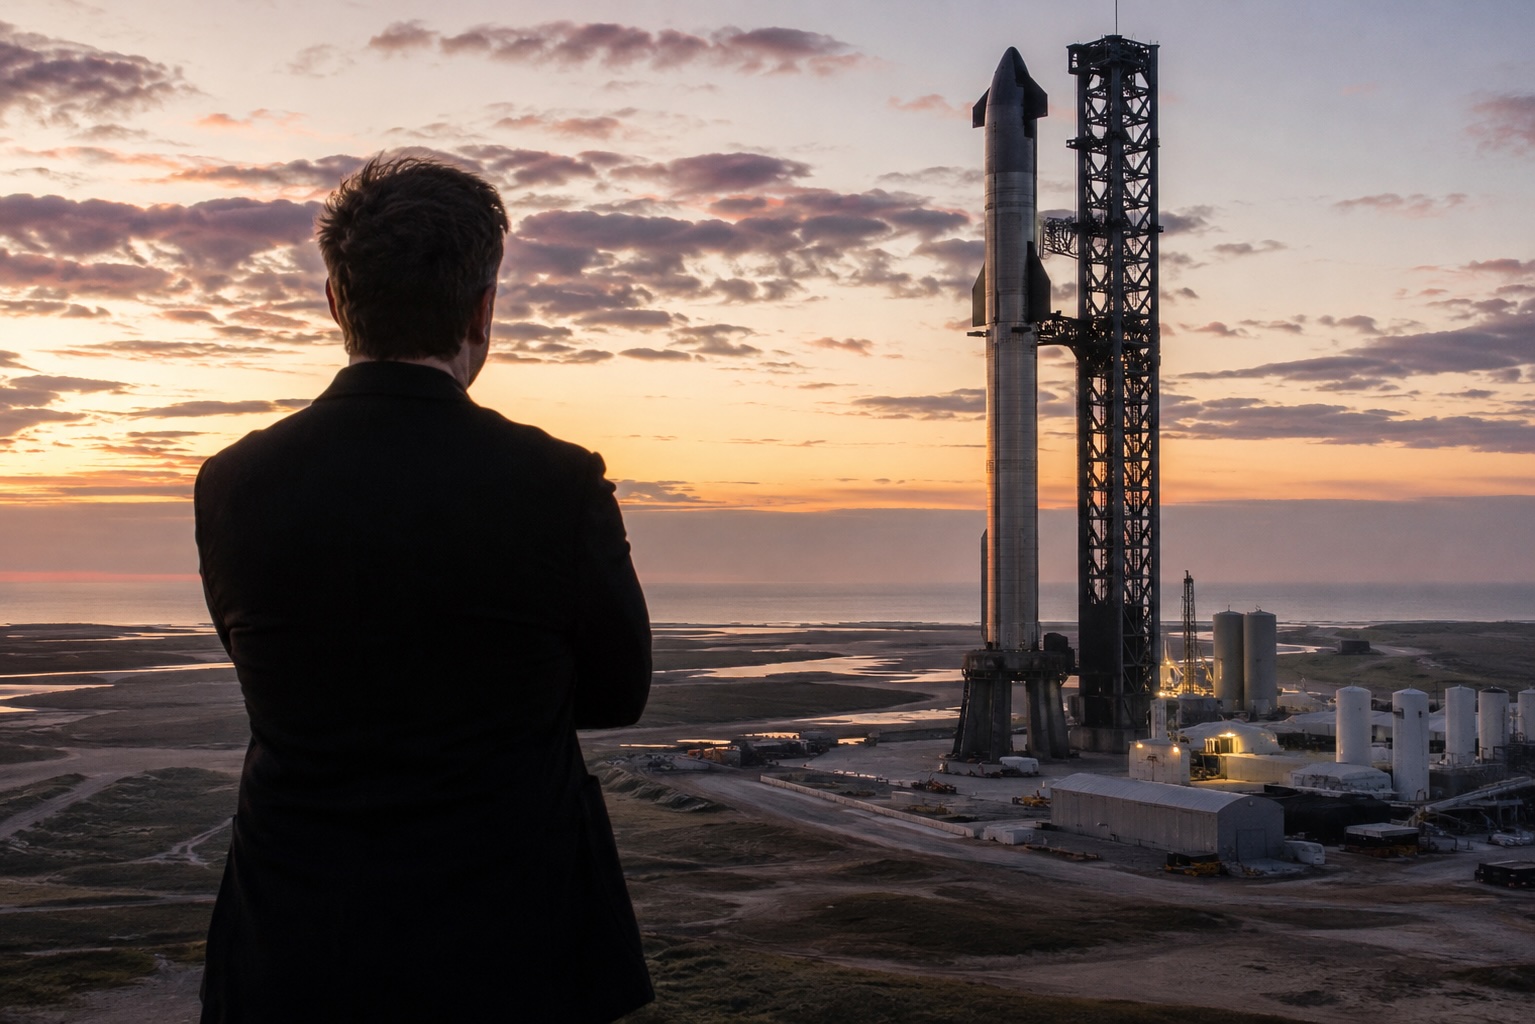
Elon Musk says SpaceX’s next Starship flight will try something nobody has done before, by catching the ship itself. Speaking to roughly 2,000 people at the X Takeover event at Giga Texas on Saturday, Musk said Flight 15 is about four to six weeks away and “probably launches a little bit before Thanksgiving, is my guess.”
That is a slip from earlier reporting, which had pointed to a launch as early as October 19. Musk explained why the date keeps moving. “We’re making a bunch of improvements to the rocket between every flight,” he said, adding that there are often hundreds, sometimes thousands, of small changes. This time the list is short, “but some of them take a fair bit of work and we’ve got to go inside the tank to make some of these changes.”
“We’re going to try to catch the ship, which is a super big deal,” Musk said. “If we do so, that’ll be the first time that there’s been full recovery of an orbital class rocket.” SpaceX has already caught the Super Heavy booster with the tower’s mechanical arms, and has talked about catching the ship since late 2025, but the upper stage has never been caught.
Musk also laid out what comes after. “The next big milestone would be to refly both the booster and the ship,” he said, describing a Flight 16 where “all parts of an orbital rocket are reflown.”
The reason SpaceX wants this comes down to cost and cadence. Every Starship ship so far has ended its flight in the ocean, and SpaceX expects most of those water landings to end in fireballs. A ship that returns to Starbase intact can be inspected and flown again. SpaceX’s IPO filing, says Starship V3 is designed to deliver 100 metric tons to orbit in a fully reusable configuration, that SpaceX aims to cut the cost to reach orbit by 99% or more versus the historical average, and that tower catches should allow “multiple launches per day.”
The payoff goes beyond cheaper launches. The next generation Starlink V3 satellites are too large for Falcon 9 and can only fly on Starship, which can carry up to 60 per flight. Flight 14 on September 28 deployed the first 26 of them after Starship reached orbit despite an early engine shutdown, as Teslarati reported. Musk blamed engine computer software, and said the heat shield “was extremely robust,” which he claimed in August had solved Starship’s biggest challenge.
NASA’s Moon plans depend on the same capability. NASA’s inspector general has described a lander mission that needs a propellant depot in low Earth orbit and more than 10 tanker flights, with SpaceX targeting one tanker launch every six days. That schedule only works if ships and boosters come back fast and fly again. Also, ship to ship propellant transfer has not been attempted yet.
One interesting hurdle yet to be explored is bringing the ship back to the launch site, with reentry over land, which will undoubtedly come with a lot of aviation safety reviews.
Investor's Corner
SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions
SpaceX reveals plans for one million Starmind AI satellites and calls out operators hiding maneuvers.
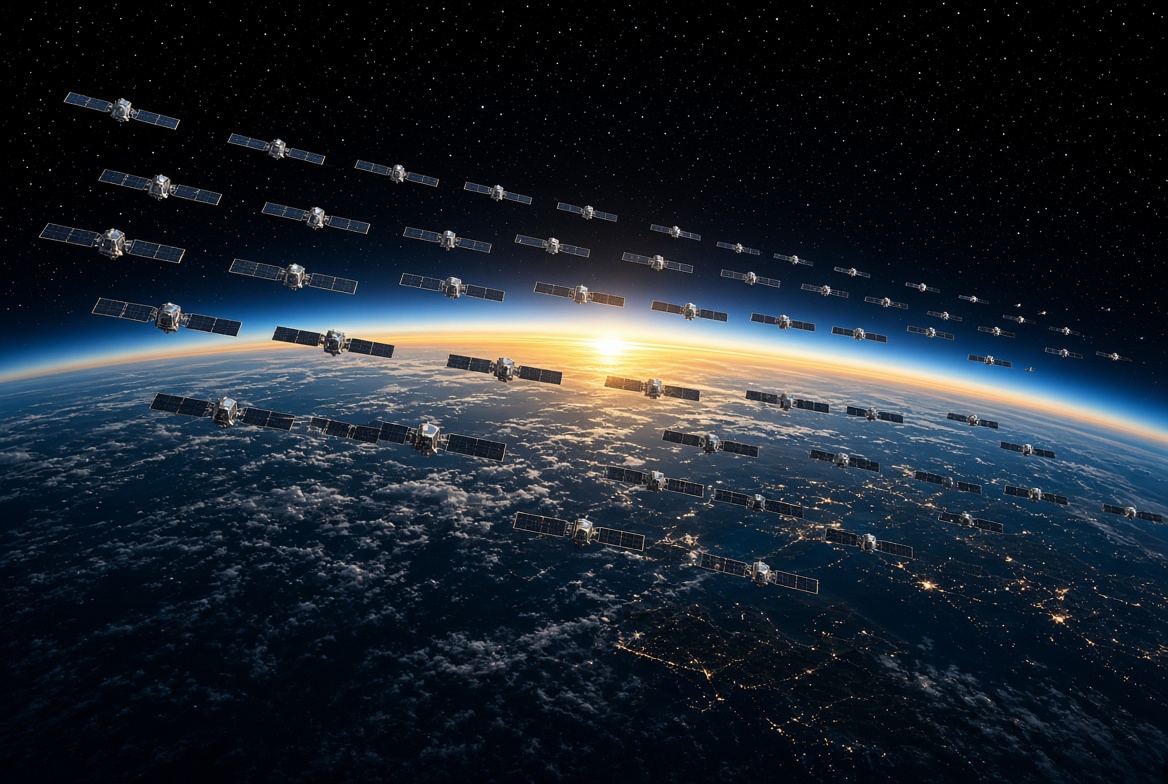
SpaceX has put the largest satellite count it has ever published into writing, and it says that plan only works if every other operator in orbit starts sharing what it knows.
In a new Space Safety page highlighted Tuesday morning by Sawyer Merritt on X, SpaceX said it “plans to operate up to 100,000 Starlink satellites and up to 1 million Starmind AI satellites to meet the growing demand for broadband and supercompute.” Starlink has a little over 11,000 satellites in orbit today, so the target alone implies roughly a ninefold expansion of the broadband network.
Starmind is SpaceX’s orbital AI compute constellation. Elon Musk confirmed the Starmind name in June after an xAI trademark filing surfaced, and in August SpaceX said it was working with Nvidia on the compute payload. The FCC accepted the filing for up to one million satellites back in February.
FCC accepts SpaceX filing for 1 million orbital data center plan
SpaceX also released a new render of what a full Starmind constellation could look like. Alongside it, SpaceX VP Michael Nicolls explained why the satellites will not operate on their own. “We need to operate clusters of satellites in tight formation to get enough coherent compute to run AI models efficiently,” Nicolls said. “A cluster will be 10-ish satellites connected with 10 terabits or so of bandwidth between them, and interconnected to the broader constellation.”
That is the most specific detail SpaceX has given on how Starmind will be built. Instead of a million independent servers, the network would work as tightly packed groups of about 10 satellites acting as one compute unit, with Starlink’s laser links carrying results back to Earth.
There is a bright and exciting future for humanity ahead – and space is fundamental to that future.
To achieve this, space safety must be done right. We encourage every operator to not only share ephemeris data proactively the same way Starlink already does, but to also adopt the high standards of space safety that SpaceX and Starlink use every day → https://t.co/QizAkQZvEm
— Starlink (@Starlink) October 6, 2026
Packing satellites that close together, at that scale, makes collision avoidance the central problem, and most of the Space Safety page is aimed at other operators. SpaceX said Starlink encountered collision risks with about 650 unique maneuvering third party satellites in 2026, and only about half of them shared data. Over six months, Starlink recorded roughly 164,000 more collision risks where the closest approach came within four hours of an unannounced maneuver.
Some operators keep maneuver plans private over proprietary concerns, while others cannot get government permission to share them. SpaceX called those policies “counterproductive,” saying they “largely only serve to create preventable collision risk between satellites.” Starlink is also offering a free ephemeris sharing and screening platform that returns risk results within a minute, backed by its Stargaze network of 30,000 optical sensors.
The push comes as the Starmind application draws opposition from astronomers and environmental groups. In a September filing with the FCC, SpaceX said each Starmind satellite could weigh up to 4,000 kg, nearly seven times the mass of a Starlink V2 Mini. Musk has brushed off crowding concerns before, telling viewers in June that “space is enormous” and that SpaceX already knows how to run very large constellations safely.
SpaceX’s Starmind page says its Gigasat factory in Bastrop, Texas, is designed to produce AI satellites at scale, with deployment of thousands of units starting as soon as late 2027.

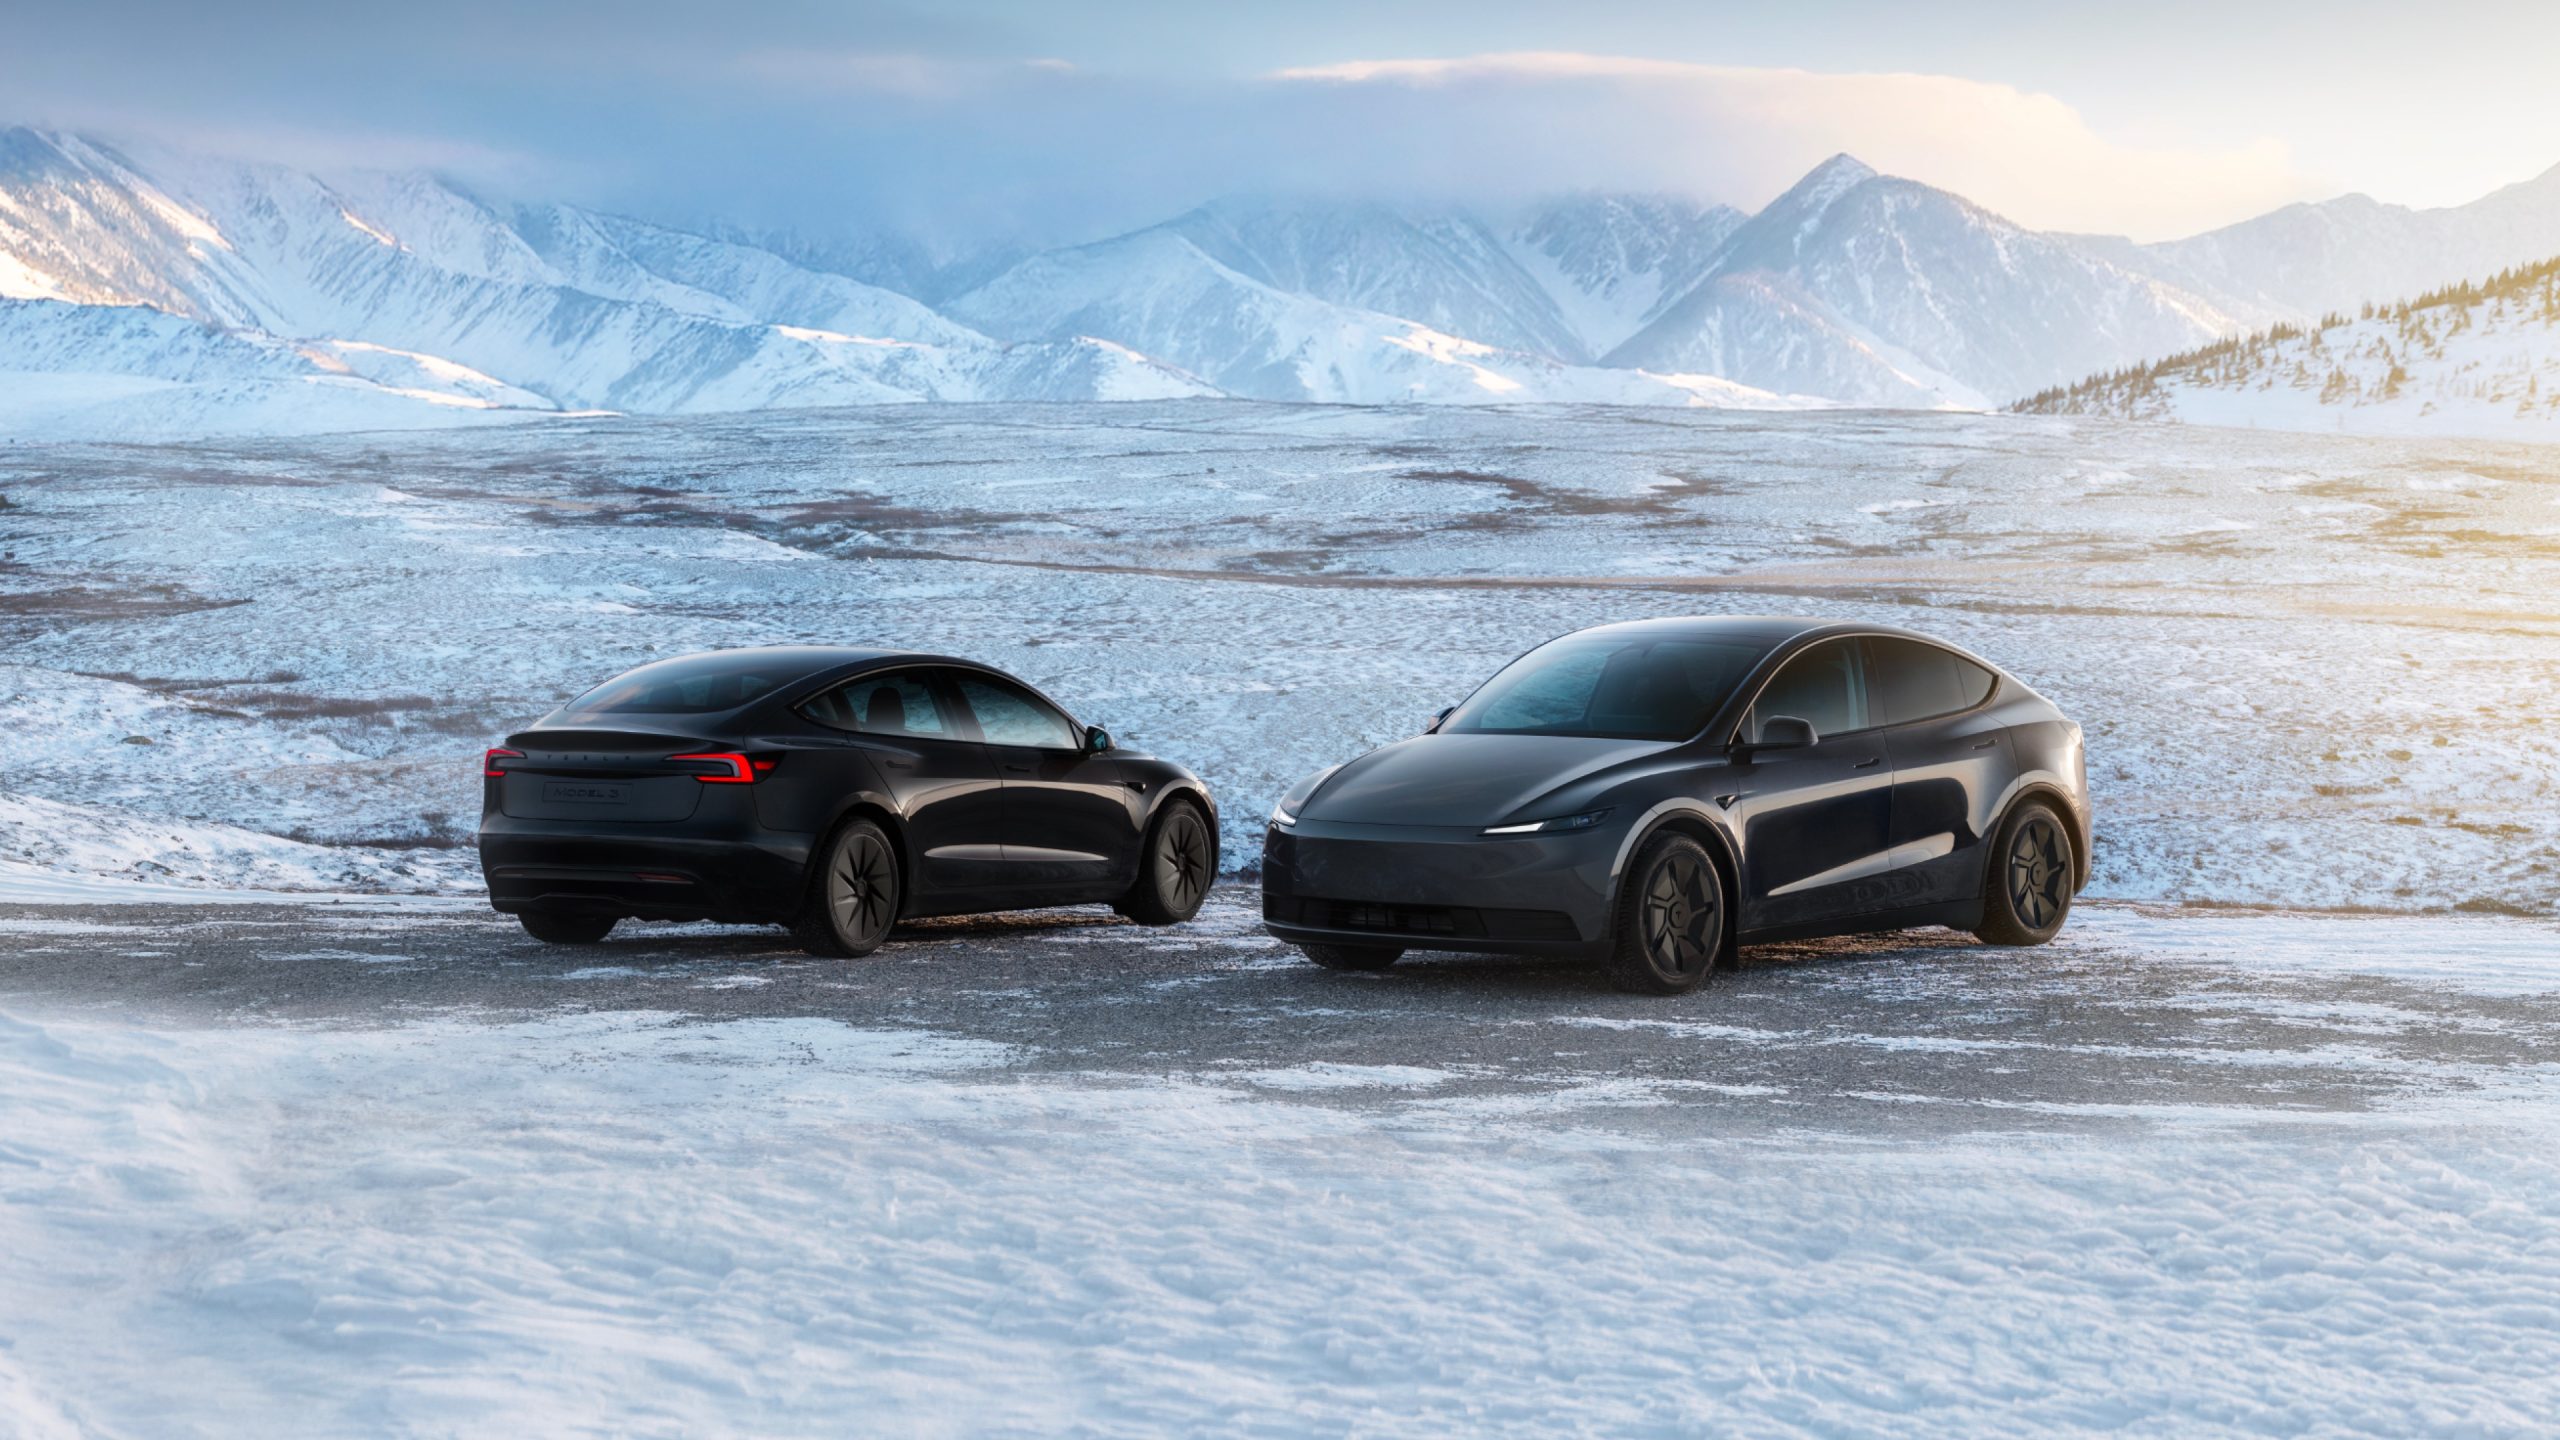
Tesla (NASDAQ: TSLA) reported strong delivery figures that beat Wall Street guesses, and they were revealed alongside the company’s second-best quarter in terms of energy deployments ever.
Tesla announced this morning that it delivered 486,532 cars in Q3, while producing 464,391, exceeding analyst consensus, which sat around 462,000 units.
Meanwhile, Tesla reported 13.7 GWh of energy storage deployed for the quarter. That’s the second-best quarter Tesla has ever reported on that side of things.
🚨 Tesla delivered 486,532 vehicles in Q3, beating expectations at 464,391.
Big Q from the Tesla team, also 13.7 GWh of energy was deployed. pic.twitter.com/olioLWgG7a
— TESLARATI (@Teslarati) October 2, 2026
Vehicle Deliveries
Deliveries were strong, and it was another quarter when Tesla had the opportunity to outshine the Wall Street pundits who are quick to criticize and slow to give credit. Tesla saw a slight decrease in deliveries compared to Q3 2025, but Tesla still had the $7,500 EV Tax Credit to use to help incentivize consumers to pick an EV.
A small decrease of 2.1 percent is pretty telling because it shows Tesla does not need massive federal credits to convince consumers to purchase its vehicles.
It was also the company’s third-best performance all-time in terms of deliveries, trailing that of Q3 2025 with 497,099 deliveries and Q4 2024, when the company handed over 495,570 cars.
We reported several days ago that Tesla Showrooms across the United States were completely bare of inventory or unclaimed units. Many locations also removed Demo Drive units, which had been bought by customers looking to take delivery sooner.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
Energy Generation
Tesla’s Energy Generation performance in Q3 was also very strong, as the company deployed 13.7 GWh of energy storage over the past three months. The only quarter when Tesla reported stronger energy deployment figures was Q4 2025, when 14.2 GWh of energy storage was deployed.
Tesla’s Q3 performance in energy generation has continued to grow each quarter, with the company increasing its deployments by ten-fold since Q3 2021, when just 1.3 GWh was deployed.
It is also nearly double what it was in Q3 2024, when the company reported 6.9 GWh. This is one of Tesla’s quickest-growing divisions, and it flies under the radar with fans and analysts, as many are focused on self-driving or the vehicles themselves.
Tesla Stock
Shares rose 5.07 percent to $372.06 at just after 10 a.m. on the East Coast. This is a rarity for Tesla after a strong delivery report, as positive news usually brings the stock down. Many quarters with extremely robust delivery reports have not been as kind to the Teslanaires of the world.

Tesla Roadster livestream: everything Tesla has revealed before Thursday night

SpaceX just combined Grok, Cursor, and X into one mega plan

Taiwan power firm bets big on Tesla Megapacks as AI data center thirst grows

The Pentagon taps Elon Musk to design the battlefield of the future

Tesla Roadster’s new patent preps white-knuckle speeds, keeping it grounded


