
It’s the question that puzzles pundits and makes short-sellers see red: Why isn’t Tesla broke yet? The company has posted losses almost every quarter since its founding, but not only does it remain in business, it steadily rolls out new products and opens up new markets, as Tesla fanboys cheer and the stock (over the long term) has soared.
Many have sought an answer to this consequential question – the latest is the Youtube channel The Rest of Us, in a charmingly childlike animated video that explains Tesla’s unique financial model in the simplest of terms.
Above: Exploring the financials at Tesla (Youtube: The Rest of Us)
In short, Tesla isn’t broke because it isn’t running out of cash. Theoretically, losses can continue indefinitely, as long as the kitty is regularly replenished. But where does the cash come from? Some comes from the sale of vehicles – Tesla earns a healthy margin on each car it sells (despite the disingenuous claims of some naysayers), and it sometimes even gets cash in the form of deposits before it even builds a vehicle (a clever financial feat that’s the envy of other automakers).
However, even as Tesla rakes in piles of money from product sales, it shovels out much more. Whence cometh the cash to top up Tesla’s reserves? Some is borrowed (debt financing), but more comes from the stock market (equity financing). Why do investors keep buying shares in a company that perennially loses money? Because savvy investors don’t base their decisions on what a company is doing today, but on its prospects for the future. Tesla is focused on the future like no other automaker, and has steadily invested huge sums to prepare for a future in which it sees huge opportunities.
Many articles about Tesla and other high-flying tech companies use terms such as “burn rate,” which can give the false impression that the cash that’s coming in just disappears, frittered away, heedlessly tossed to the winds, flushed down the…you get the idea.
Back in 2016, Vincent Paver, writing in Medium, made some good points as he explained that, far from throwing its cash in the fireplace, Tesla has invested much of it in capital goods – handy things like factories, machine tools, robots and charging facilities. Paver points out that, at the time of writing, Tesla had “burned” $1.6 billion over the last 12 months, but the book value of its equipment had increased by $2.8 billion over the same period. Other expenditures, such as vehicle development costs and employee training, may not result in tangible bricks-and-mortar assets, but they are also investments, as they allow Tesla to create new products that it can sell for more lovely cash.
Paver concludes that what we have here is not a company that is recklessly flinging away money, but one that is “in a capital-intensive business, and is [investing] substantial but appropriate sums of money on equipment and capacity expansion, tied directly to strong end user demand.”
And there you have the real key to why the callow California carmaker hasn’t gone belly-up, and won’t if current trends continue. The demand for Tesla’s products is strong – the backlog of Model 3 orders remains huge, and Models S and X continue to sell at a steady pace. Yes, not being able to produce vehicles fast enough to meet demand is a problem, but the reverse would be much worse. If Tesla’s waiting list disappears, and sales figures start going down, then it will truly be time to worry about the company’s cash flow.
Paver calls Tesla “a rare example of a public company aggressively chasing a market opportunity many multiples greater than its current scale.” Elon Musk’s new compensation plan, which was recently approved by shareholders, envisions the automaker growing to a market cap of $650 billion, which would make Tesla one of the five largest companies in the US. If and when that happens, rest assured that plenty more cash will be burned along the way.
===
Note: Article originally published on evannex.com by Charles Morris

Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.

Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.
Elon Musk
SpaceX President to gift Trump Accounts her SpaceX stock
Gwynne Shotwell’s 2 million SpaceX shares are headed to children’s Trump Accounts starting this December.
SpaceX President Gwynne Shotwell said Friday that more than 2 million SpaceX shares belonging to her and her husband, Robert, will be distributed to children’s Trump Accounts in December, turning a pledge she made over the summer into an actual transfer. “Robert and I are thrilled that our gift of over 2 million shares of SpaceX stock will be distributed to children’s Trump accounts in December!” Shotwell wrote on X, adding that the shares are “transferring to escrow as we speak.”
The first round goes to children aged 11 to 17 who live in ZIP codes where the median family income is $57,000 or less, along with kids in ZIP codes with too few residents for the Census to report that figure. Shotwell said those families should receive a notice by Monday, Reuters reported.
A second gift is expected to be finalized in the next few weeks. That round will cover eligible children in military families serving overseas, children in foster care, and more kids in Texas counties near the Shotwells’ home where median family income is $90,000 or less. Elon Musk replied to the announcement with “Cool” and a heart emoji.
Shotwell first announced the donation on July 6, less than a month after SpaceX priced its record IPO at $135 per share on the Nasdaq. IPO filings showed Shotwell owned about 12.6 million SpaceX shares, Quartz reported at the time, which makes the gift roughly one sixth of her stake. At the roughly $146 per share used to value Musk’s own pledge earlier this month, 2 million shares are worth about $290 million.
How the stock would actually reach the accounts had been an open question since July. Treasury guidance acknowledged that stock donations could flow into Trump Accounts, but it did not explain the mechanics for a program whose contributions default into an S&P 500 index fund. Shotwell thanked the Treasury, the IRS, the Dell Foundation, Greater Horizons, Invest America and the law firms Morgan Lewis and Gibson Dunn for “working over the past few months to make this happen.”
The transfer also works as a dry run for a far larger gift. On October 19, Musk said he would give one of his SpaceX shares to every kid in America next year and called it “the first of many.” With roughly 72 million children in the country, that pledge is worth about $10.5 billion. President Donald Trump thanked Musk the same day and said the shares would go through Trump Accounts, though neither SpaceX nor the Treasury has published how or when that distribution will happen.
Shotwell’s recipients also fill a gap in the program itself. Trump Accounts launched on July 4, and the $1,000 Treasury deposit only goes to babies born between 2025 and 2028. Teenagers aged 11 to 17 receive no government seed money, so for many of the families getting a notice on Monday, SpaceX stock will be the first asset in the account. The accounts convert into retirement accounts when the child turns 18.
Investor's Corner
Tesla has a Cybercab problem nobody saw coming
Tesla’s Cybercab line now builds robotaxis faster than Tesla can deploy them, Lars Moravy says.
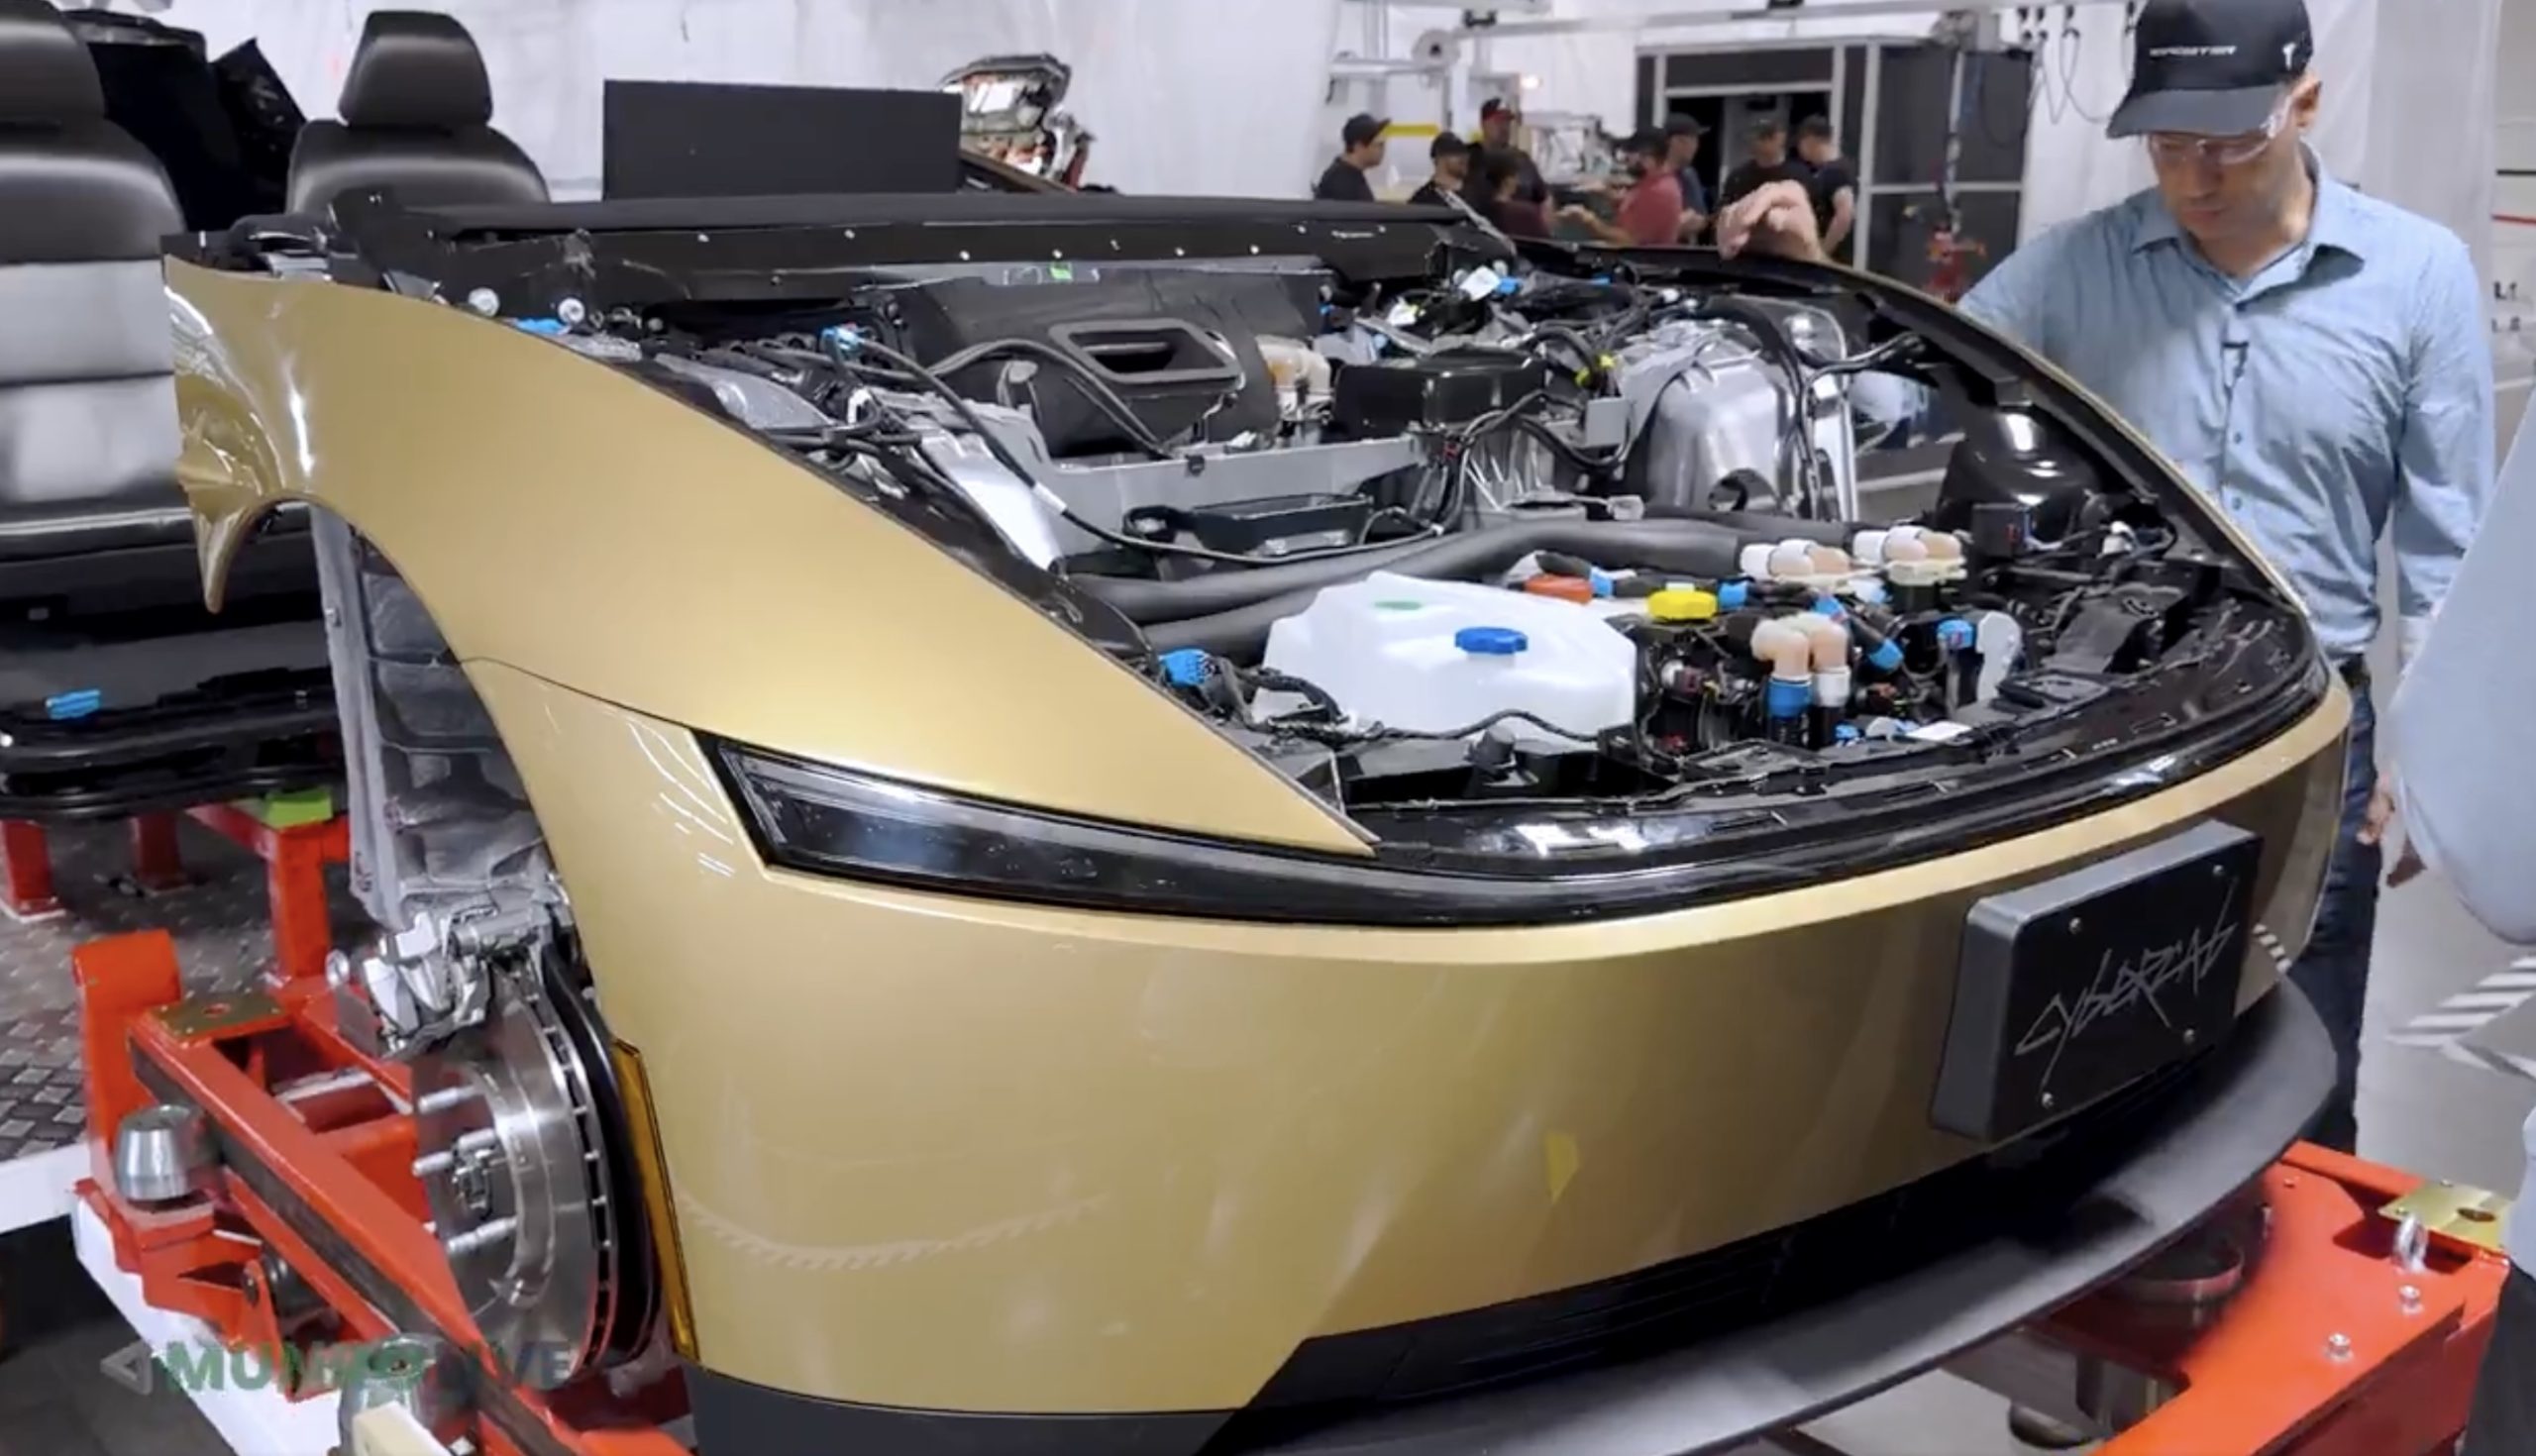
Tesla’s Cybercab line in Texas can now build the two seat robotaxi faster than the company can put it into service, according to Lars Moravy, Tesla’s Vice President of Vehicle Engineering. “We don’t run every day because the line can run so fast. It’s currently outpacing our deployments,” Moravy said in a new Cybercab deep dive from Munro Live. “So, it’s a bit of a race right now. Who’s going to go faster? Right now the manufacturing line’s ahead.”
Tesla’s official Robotaxi account shared a Cybercab analysis video on X on Monday, calling it a “Cybercab engineering deep dive.” Moravy’s comments go further than what he told analysts on the Q3 earnings call last week, when he said the Cybercab line’s listed capacity of more than 125,000 units a year undersells what it can actually run.
The tour shows where that speed comes from. Tesla’s unboxed process splits the Cybercab into front, rear, side and center modules that are built and tested on their own before they meet on a short final line. That final line has just 25 fully automated stations, which Tesla’s team estimated is a fifth to a tenth of what a Model Y needs. The full line is about 78% automated, the framing line is already at 100%, and the layout uses roughly 50% less floor space per vehicle. The stated goal is “100% automation in 10 second cycle time,” or one finished Cybercab every 10 seconds.
Tesla also deleted the paint shop. Only the side modules are coated, and the exterior panels get their color inside the molding machine. Engineers said the car is designed to run at least 500,000 miles, which matters for a vehicle that will spend most of its day carrying riders.
The battery got the same treatment. The Cybercab uses an 88S6P pack of 4680 cells in a steel enclosure, a first for Tesla, with each module potted separately so a single failed module can be swapped instead of the whole pack. Wireless battery management boards replace a wiring harness, and new contactors are fast enough to drop the pyro fuse entirely. Tesla’s battery director graded the pack an A minus, compared with a D for the Model Y structural pack and a B minus for Cybertruck. Up front, the drive unit runs an 11:1 gear ratio versus roughly 9:1 on most Teslas, since the Cybercab does not need a high top speed.
Cybercab engineering deep dive — Robotaxi (@robotaxi) October 26, 2026
The deployment side is now the bottleneck Moravy described. Tesla had more than 50 Cybercabs working the Formula 1 weekend in Austin, and Texas records show 463 Cybercabs registered. Tesla said on its earnings call that Cybercab service will launch in Dallas next month, and Moravy said the company is aiming to get Cybercabs to customers by the end of 2026. Every unit built so far has gone into Tesla’s own fleet since the line moved into volume production in April.
Munro Live also asked when it could get a Cybercab to tear down. Tesla’s answer: “Not yet.”

Tesla owners who tap Emergency Drive Away for fun are in for a surprise

Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit


