Investor's Corner
Tesla’s growth story continues in manufacturing and not autonomy: Morgan Stanley

Tesla’s (NASDAQ: TSLA) growth story has leaned on the potential of autonomous, self-driving vehicles revolutionizing the way everyday transportation is performed. While Tesla has developed its Autopilot and Full Self-Driving suites with relative success in the past several years, Morgan Stanley analysts are not convinced that autonomous driving programs will continue to fuel the automaker’s growth story and continuing expansion. Instead, Tesla’s bread and butter, which is vehicle manufacturing, along with other strengths like material sourcing, supply chain, and infrastructure development, is where the financial firm is putting its money.
It is no secret Tesla has fallen short with its FSD and Robotaxi plans, as CEO Elon Musk has predicted since 2018 that the automaker would complete its venture into fully-autonomous vehicles. However, each year has gone by with a new set of challenges, whether they would be based on manufacturing or the supply of necessary parts, further delaying the rollout of a “feature complete” FSD suite or a rollout of the planned Robotaxi fleet. This has led to some skepticism about whether the electric car company will really continue its monumental pace of growth through that medium, and not another, which Tesla has already proven to be well-versed in: manufacturing.
Tesla manufacturing prowess, stock split plans indicate ‘massive position of strength:’ Wedbush
A new note to investors from Adam Jonas and other analysts at Morgan Stanley seems to indicate the latter, that Tesla’s true road to continuing expansion and increased valuations is a focus on what it does best. For the past several years, Tesla has focused intently on increasing manufacturing efficiency and accuracy, and it has ultimately led to a streak of nine consecutive quarters of growth in vehicle deliveries. While that streak may be in jeopardy due to the shutdowns of its most-productive factory, which is in Shanghai, there is still evidence to suggest that Tesla’s best way to continue growing is through its production prowess.
“With respect to Tesla, we think attributes like AI, autonomous, and EV are fully, if not over-appreciated here,” the analysts wrote in their note. “In fact, we believe Tesla’s more ‘gritty’ capabilities in terms of manufacturing, material sourcing, supply chain, and infrastructure will drive the next leg of growth to the story.”
Tesla will trade with increased volatility in the coming weeks and months, Morgan Stanley predicted in the new note. The company’s focus on its autonomy may be dragging down expectations for the stock, as Tesla continues to push its belief that FSD and Level 4 to Level 5 autonomy will be arriving by the end of the year. The analysts see this as a major issue in Tesla’s outlook moving forward:
“Firstly, we think the core auto margin is too high at this point, as it does not fully reflect input cost inflation. Secondly, we believe expectations of full autonomy or FSD ‘flipping’ into a major near-term margin boost are overestimated. In fact, we believe L4/L5 autonomy at scale is well over a decade away. It will come folks, but it’s too darn difficult.”
-
- Credit: Gary Black | Twitter
-
- Credit: Gary Black | Twitter
-
- Credit: Gary Black | Twitter
In reality, Tesla has made major strides in its FSD program through the Beta fleet, and Autopilot is coming off of one of its safest years in history when compared to nationwide accident data from the NHTSA. But whether Tesla will solve full autonomy by the end of the year as Musk expects truly remains to be seen.
Musk remains confident with Tesla’s development of FSD and said earlier this year that he would be “shocked” if the company cannot effectively develop major improvements and complete the suite by the end of 2022. Meanwhile, Tesla’s Robotaxi fleet will likely come with a dedicated vehicle design in the coming years, based on predictions from company executives during its most recent earnings call. While Tesla’s outlook on Robotaxis was previously about owners making money from the operation of the ride-sharing service, the automaker has shifted to another perspective, which aligns more with its focus on sustainability. Read more about that here.
Jonas still holds a $1,300 price target on Tesla stock with an ‘Overweight’ rating.
Disclosure: Joey Klender is a TSLA Shareholder.
I’d love to hear from you! If you have any comments, concerns, or questions, please email me at joey@teslarati.com. You can also reach me on Twitter @KlenderJoey, or if you have news tips, you can email us at tips@teslarati.com.

Investor's Corner
Tesla has a Cybercab problem nobody saw coming
Tesla’s Cybercab line now builds robotaxis faster than Tesla can deploy them, Lars Moravy says.

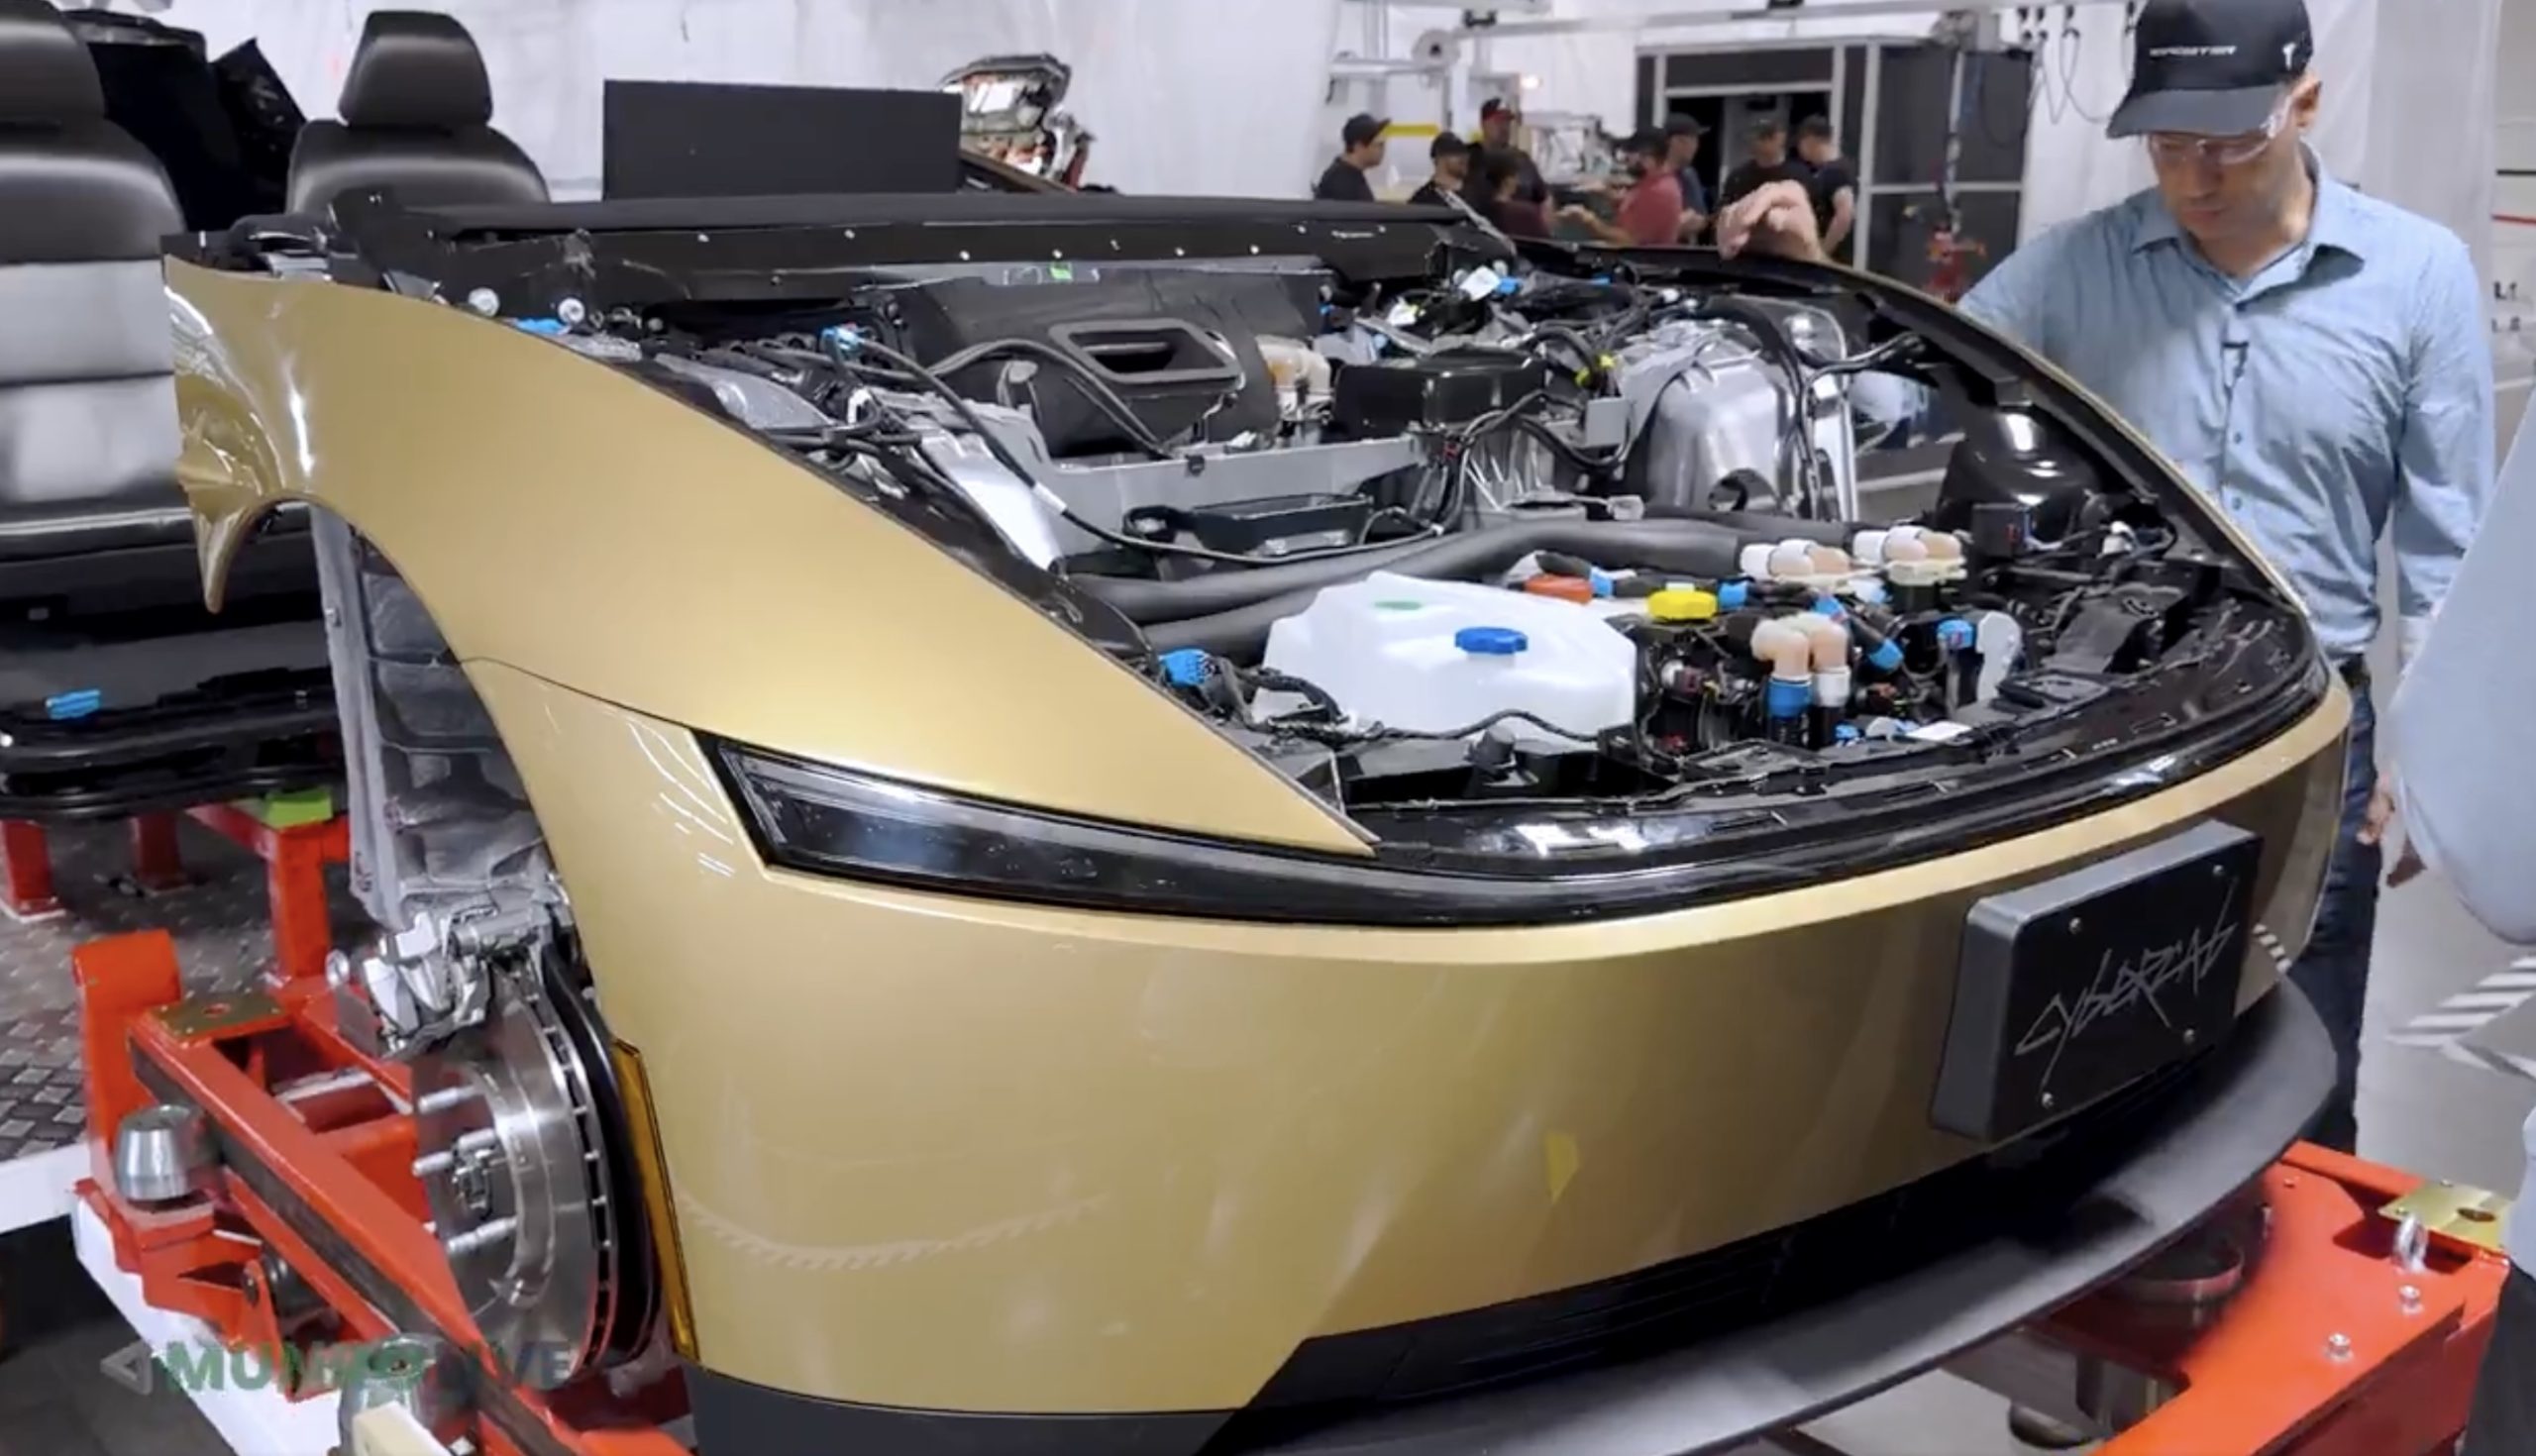
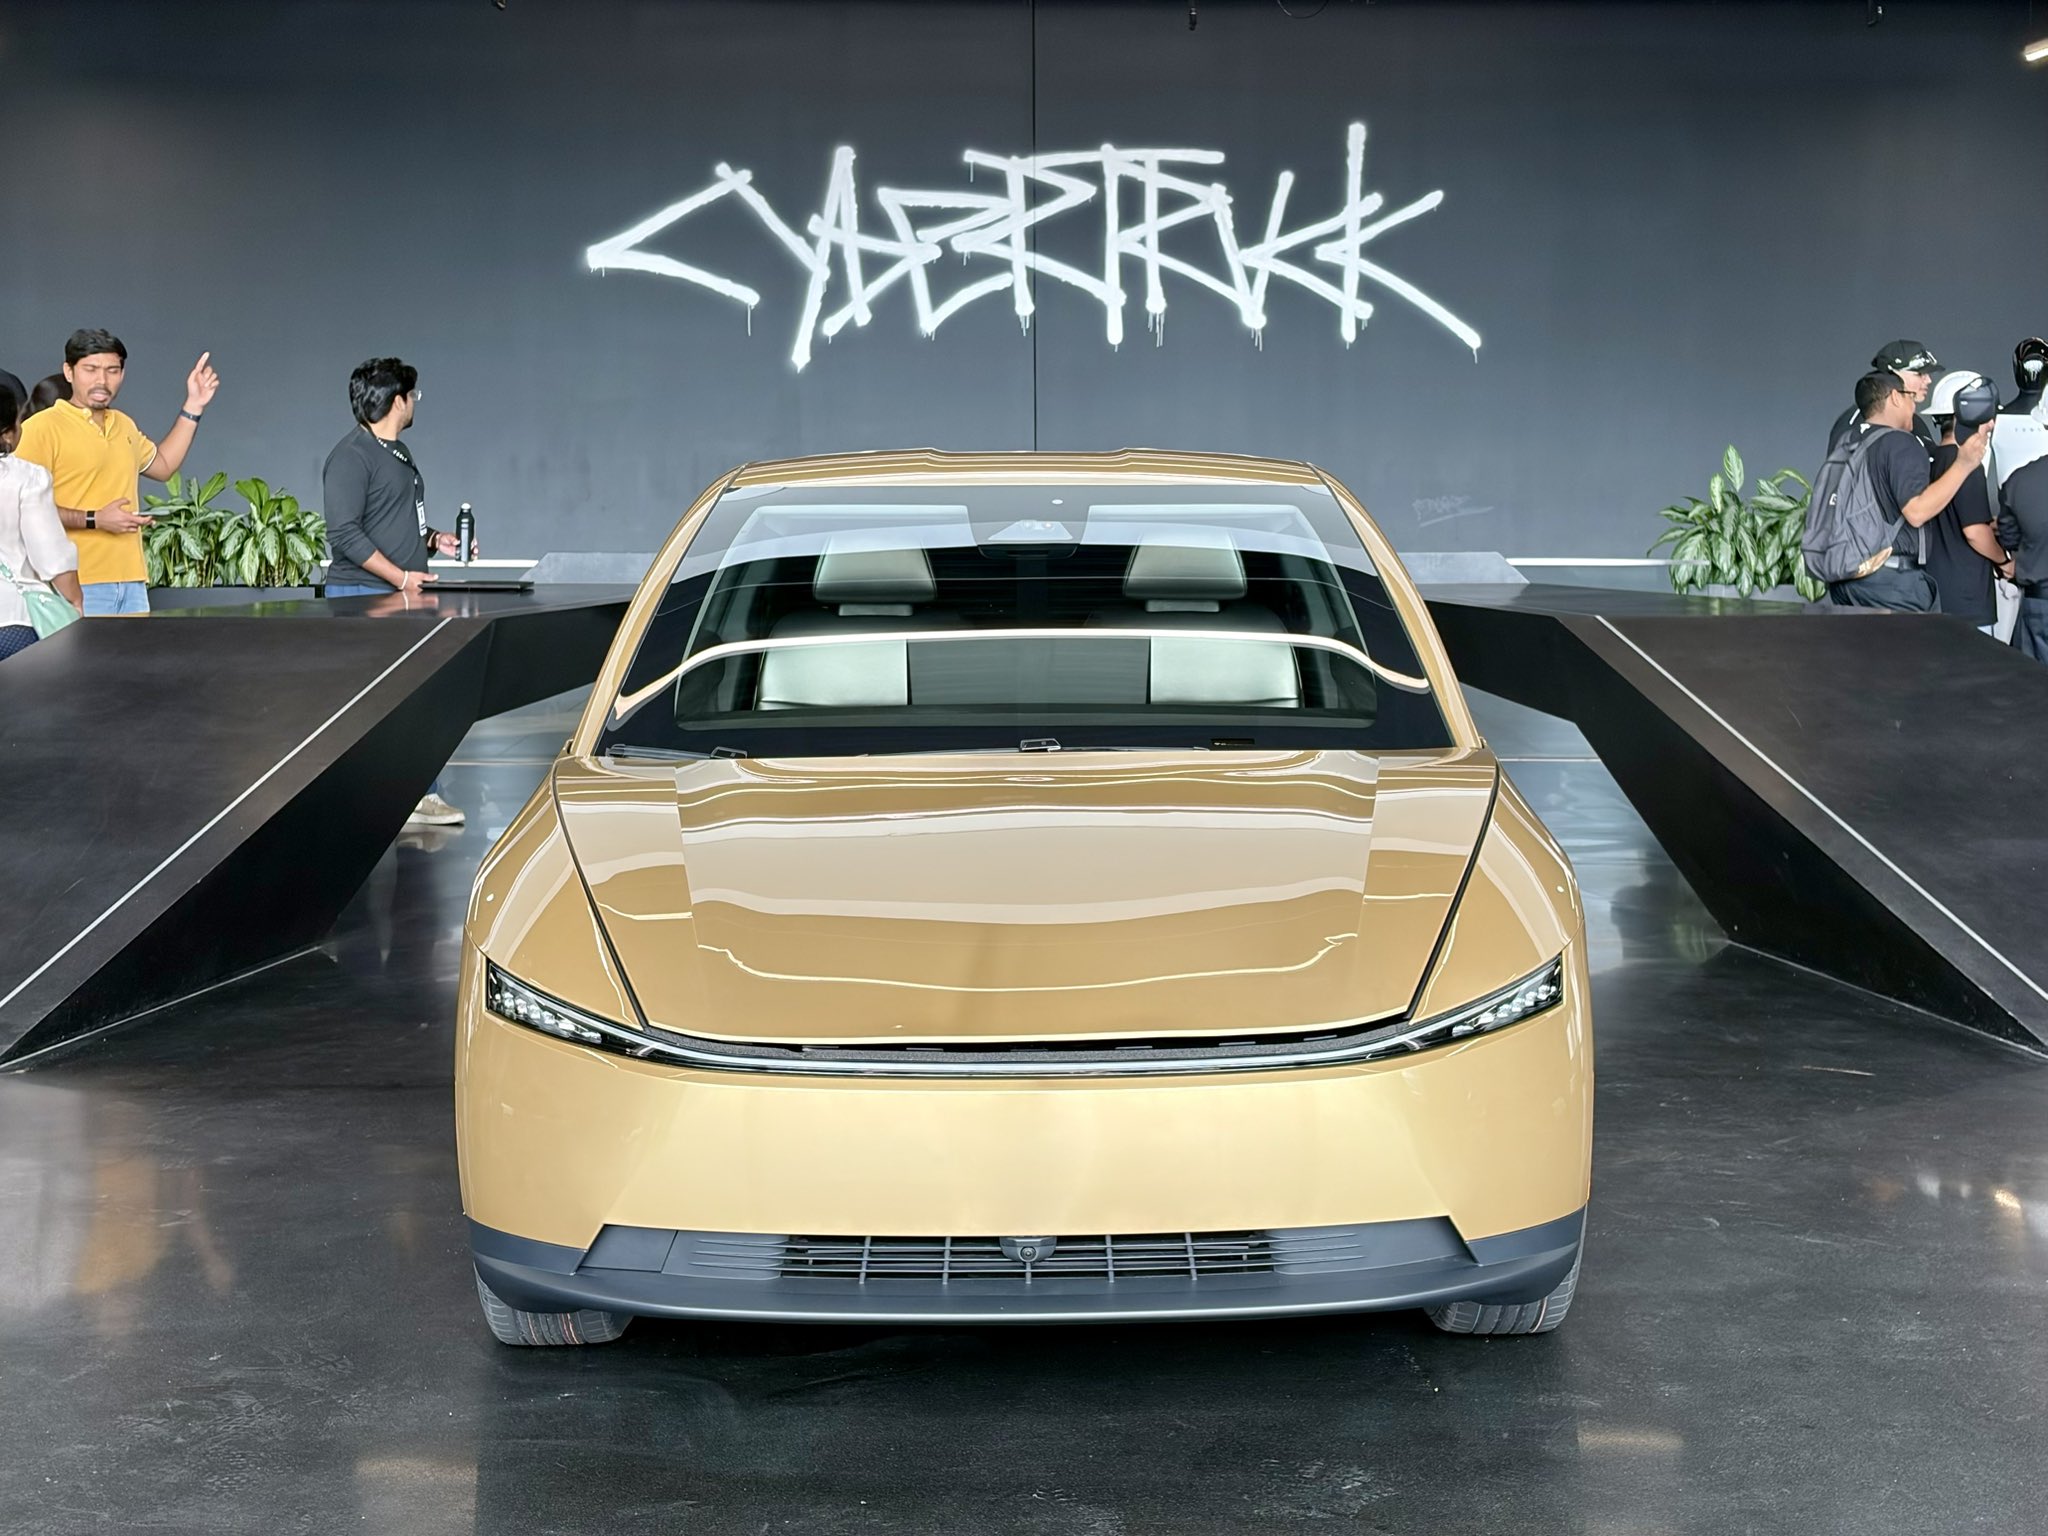
Tesla’s Cybercab line in Texas can now build the two seat robotaxi faster than the company can put it into service, according to Lars Moravy, Tesla’s Vice President of Vehicle Engineering. “We don’t run every day because the line can run so fast. It’s currently outpacing our deployments,” Moravy said in a new Cybercab deep dive from Munro Live. “So, it’s a bit of a race right now. Who’s going to go faster? Right now the manufacturing line’s ahead.”
Tesla’s official Robotaxi account shared a Cybercab analysis video on X on Monday, calling it a “Cybercab engineering deep dive.” Moravy’s comments go further than what he told analysts on the Q3 earnings call last week, when he said the Cybercab line’s listed capacity of more than 125,000 units a year undersells what it can actually run.
The tour shows where that speed comes from. Tesla’s unboxed process splits the Cybercab into front, rear, side and center modules that are built and tested on their own before they meet on a short final line. That final line has just 25 fully automated stations, which Tesla’s team estimated is a fifth to a tenth of what a Model Y needs. The full line is about 78% automated, the framing line is already at 100%, and the layout uses roughly 50% less floor space per vehicle. The stated goal is “100% automation in 10 second cycle time,” or one finished Cybercab every 10 seconds.
Tesla also deleted the paint shop. Only the side modules are coated, and the exterior panels get their color inside the molding machine. Engineers said the car is designed to run at least 500,000 miles, which matters for a vehicle that will spend most of its day carrying riders.
The battery got the same treatment. The Cybercab uses an 88S6P pack of 4680 cells in a steel enclosure, a first for Tesla, with each module potted separately so a single failed module can be swapped instead of the whole pack. Wireless battery management boards replace a wiring harness, and new contactors are fast enough to drop the pyro fuse entirely. Tesla’s battery director graded the pack an A minus, compared with a D for the Model Y structural pack and a B minus for Cybertruck. Up front, the drive unit runs an 11:1 gear ratio versus roughly 9:1 on most Teslas, since the Cybercab does not need a high top speed.
Cybercab engineering deep dive — Robotaxi (@robotaxi) October 26, 2026
The deployment side is now the bottleneck Moravy described. Tesla had more than 50 Cybercabs working the Formula 1 weekend in Austin, and Texas records show 463 Cybercabs registered. Tesla said on its earnings call that Cybercab service will launch in Dallas next month, and Moravy said the company is aiming to get Cybercabs to customers by the end of 2026. Every unit built so far has gone into Tesla’s own fleet since the line moved into volume production in April.
Munro Live also asked when it could get a Cybercab to tear down. Tesla’s answer: “Not yet.”
Tesla (NASDAQ: TSLA) reported its earnings for the third quarter of 2026, marking a reasonable performance on the various financial metrics. Tesla still plans to hold a call that will field investor questions at 5:30 p.m. ET, 4:30 p.m. CT.
Here’s where Earnings came in:
- Total Revenues: $28.046 reported vs. $28.34B expected
- Non-GAAP EPS: $0.48 reported vs. $0.45 expected
- Operating Margin: 2.6 % reported vs. 2.5% expected
- Operating Income: $718M reported vs. $721M expected
- Free Cash Flow: $1.531B reported vs. ~-$4.51B expected
Tesla $TSLA Earnings Results:
Revenues: $28.046B
Non-GAAP EPS: $0.48
Operating Margin: 2.6%
Operating Income: $718M
FCF: $1.531B— TESLARATI (@Teslarati) October 21, 2026
Major Takeaways
Full Self-Driving (Supervised)
“FSD (Supervised)⁴ attach rate continued to grow, reaching over 75% of new vehicle deliveries in North America – our most mature market – a nearly twenty percentage point sequential increase. We believe that FSD is driving demand in markets where it is available, and we continue to work with regulators to get it approved in other markets.”
Tesla Semi
“We began volume production of Tesla Semi, our Class 8 heavy-duty truck. The top variant can go 500 miles at full 82,000 lbs gross combination weight while achieving an efficiency of 1.7 kWh/mile. That efficiency allows the Tesla Semi to use a third of the energy used by a comparable diesel truck to haul the same payload. In a transportation market where energy is one of the largest components of total cost per mile, this will provide a meaningful advantage to Tesla Semi operators.”
SI Compute
“We plan to reach 400 MW of SI training compute by the end of the year, supporting the development of both vehicle and humanoid robot autonomy software. Additionally, we continued construction for the Austin Fab, where we plan to start commissioning equipment in 2027.”
Robotaxi
“We began deployment of Cybercab into our Robotaxi fleet in Austin. We reached nearly two million cumulative unsupervised miles for our Robotaxi service as of the end of the quarter. Operating hours in Austin are now 6am to midnight, and we expect to reduce wait times via increased fleet supply and improvement of Robotaxi orchestration algorithms. Grok is available in Cybercab with access to Grok Bot and Connectors, which allows users to manage their inbox, calendars, files, chats and tasks – all hands free via voice command – making Cybercab a mode of transport, a productivity space and, with our entertainment options, a second living room.”
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.

Starlink is ‘biggest competitive advantage,’ but it’s temporary, United CEO says

Tesla Cybercab’s unorthodox paint process explained


