Investor's Corner
Moody’s upgrades Tesla (TSLA) to ‘Stable’ over Model 3 efficiencies, adequate liquidity

Tesla (NASDAQ:TSLA) recently received a positive report and upgrade from Moody’s Investors Service, which changed its outlook towards the electric car maker from “Negative” to “Stable.” In its report, Moody’s affirmed Tesla’s ratings, including the company’s B3 Corporate Family Rating (CFR) and Caa1 senior unsecured ratings. Tesla’s speculative grade liquidity was also changed from SGL-4 (Weak) to SGL-3 (Adequate).
According to the financial firm, Tesla’s B3 CFR reflects the company’s achievements in the production ramp of the Model 3, whose output is “now in line with Moody’s earlier expectations.” This, according to the firm’s report, should allow Tesla to “achieve production efficiencies, lower costs, and strengthen automotive gross margins.” These improvements are also key to offset the losses generated by the company’s automotive service operations, which could then push Tesla towards profitability. Moody’s added that the sale of regulatory credits is expected to give a boost to Tesla’s finances as well.
“An important contributor to achieving net profit will be the sale of regulatory credits, which represent no incremental cost to the company and fall directly to earnings. We expect these sales, which accounted for over $400 million in revenues/earnings during 2018, will continue to grow as emission regulations become more restrictive in all major markets,” Moody’s wrote.
Moody’s stated that it still expects Tesla to generate modestly negative free cash flow of around $500 million over the next 12 months, though the firm expects the electric car maker’s capital expenditures to decrease over this time, thanks to the company’s growing experience in its automotive production business. “Tesla’s increased experience with its production processes have significantly reduced the level of capital expenditures needed to support its growth plans, with annual CapEx falling from approximately $4 billion in 2017 to a current run rate of $1.5 to $2 billion, thus providing a significant boost to expected cash flow,” the firm noted.
Impressively, Moody’s noted that Tesla’s liquidity position is now “Adequate.” The company’s $5 billion in cash, for one, is expected to give the electric car maker a generous cushion to address maturing debt obligations through 2021, as well as address potential operational challenges that it could face in the coming year. Moody’s explains its positive outlook on Tesla’s liquidity as follows.
“Tesla has an adequate liquidity profile supported primarily by its $5 billion cash position. After giving consideration for approximately $1 billion in cash needed to fund normal ongoing operations, and $566 million to cover a November 2019 convertible note maturity, Tesla has incremental liquidity of approximately $3.4 billion. This affords the company an important cushion to contend with potential stress arising from softness in US demand, operational challenges accompanying its European and Chinese expansion plans, and the time that will be necessary to implement additional efficiency-enhancing initiatives,” the firm noted.
Nevertheless, Moody’s argued that Tesla still has notable areas of improvement, particularly in terms of its corporate governance. The firm cites the significant turnover of the company’s senior management ranks including JB Straubel’s recent decision to step aside from his CFO post; the actions of Elon Musk which have resulted in conflicts against the Securities and Exchange Commission; and a board of directors that has “not demonstrated meaningful oversight over the CEO’s activities” as areas of improvement for the electric car maker. While Tesla has been making efforts to improve this, such as the appointment of two new members of its board, Moody’s argues that “Tesla retains a very weak corporate governance structure” nonetheless.
Tesla’s updated rating with Moody’s could be upgraded or downgraded in the future, depending on the company’s performance. The firm noted that it could upgrade Tesla further if the company could demonstrate “sustained profitability and positive free cash flow in the face of rapid expansion plans in Europe and China,” as well as a capability to maintain an adequate liquidity profile. On the other hand, Tesla’s rating could be lowered if demand for its vehicles begins to soften in the United States, or if the company makes missteps in its China and Europe ramp. A downgrade could also happen if Tesla is unable to remain on a clear path towards strengthening margins in its automotive business, while narrowing losses in its other endeavors.
Moody’s full report on Tesla’s recent upgrade could be accessed here.
Disclosure: I have no ownership in shares of TSLA and have no plans to initiate any positions within 72 hours.


Tesla (NASDAQ: TSLA) reported strong delivery figures that beat Wall Street guesses, and they were revealed alongside the company’s second-best quarter in terms of energy deployments ever.
Tesla announced this morning that it delivered 486,532 cars in Q3, while producing 464,391, exceeding analyst consensus, which sat around 462,000 units.
Meanwhile, Tesla reported 13.7 GWh of energy storage deployed for the quarter. That’s the second-best quarter Tesla has ever reported on that side of things.
🚨 Tesla delivered 486,532 vehicles in Q3, beating expectations at 464,391.
Big Q from the Tesla team, also 13.7 GWh of energy was deployed. pic.twitter.com/olioLWgG7a
— TESLARATI (@Teslarati) October 2, 2026
Vehicle Deliveries
Deliveries were strong, and it was another quarter when Tesla had the opportunity to outshine the Wall Street pundits who are quick to criticize and slow to give credit. Tesla saw a slight decrease in deliveries compared to Q3 2025, but Tesla still had the $7,500 EV Tax Credit to use to help incentivize consumers to pick an EV.
A small decrease of 2.1 percent is pretty telling because it shows Tesla does not need massive federal credits to convince consumers to purchase its vehicles.
It was also the company’s third-best performance all-time in terms of deliveries, trailing that of Q3 2025 with 497,099 deliveries and Q4 2024, when the company handed over 495,570 cars.
We reported several days ago that Tesla Showrooms across the United States were completely bare of inventory or unclaimed units. Many locations also removed Demo Drive units, which had been bought by customers looking to take delivery sooner.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
Energy Generation
Tesla’s Energy Generation performance in Q3 was also very strong, as the company deployed 13.7 GWh of energy storage over the past three months. The only quarter when Tesla reported stronger energy deployment figures was Q4 2025, when 14.2 GWh of energy storage was deployed.
Tesla’s Q3 performance in energy generation has continued to grow each quarter, with the company increasing its deployments by ten-fold since Q3 2021, when just 1.3 GWh was deployed.
It is also nearly double what it was in Q3 2024, when the company reported 6.9 GWh. This is one of Tesla’s quickest-growing divisions, and it flies under the radar with fans and analysts, as many are focused on self-driving or the vehicles themselves.
Tesla Stock
Shares rose 5.07 percent to $372.06 at just after 10 a.m. on the East Coast. This is a rarity for Tesla after a strong delivery report, as positive news usually brings the stock down. Many quarters with extremely robust delivery reports have not been as kind to the Teslanaires of the world.
Elon Musk
Elon Musk and Trump are closer than ever, and Tesla could be the big winner
Elon Musk sat beside Trump as AI leaders signed a voluntary White House safety accord.

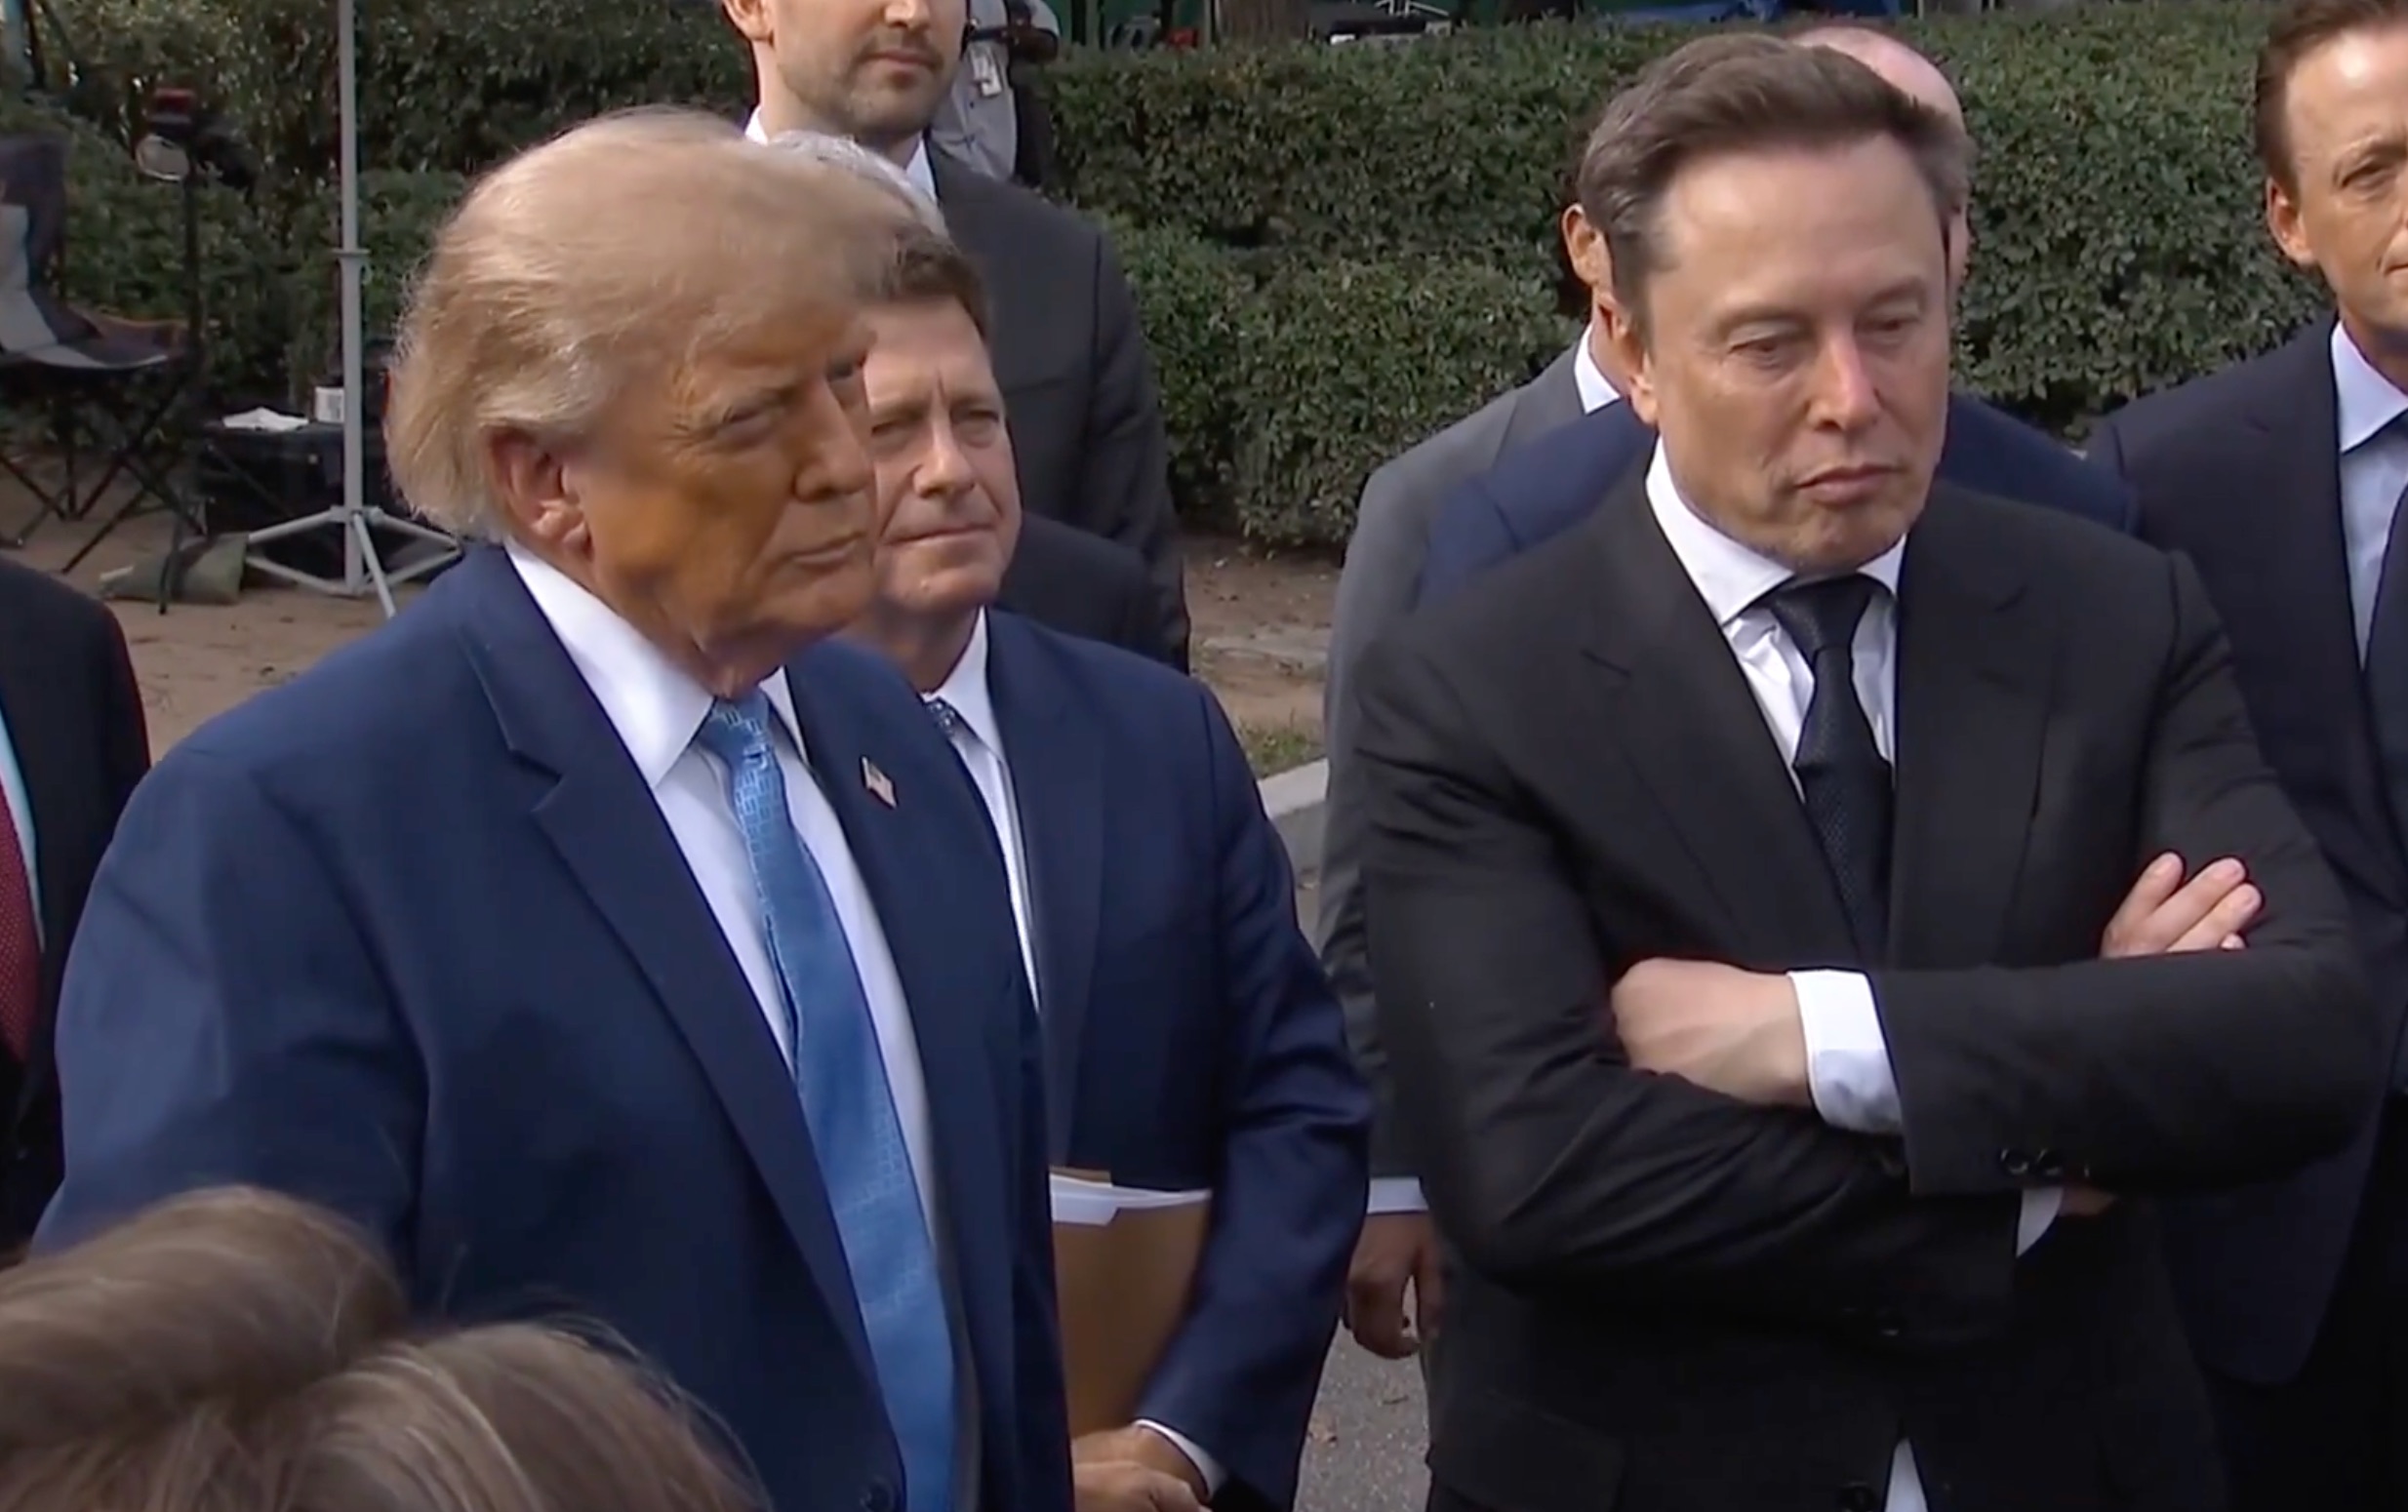
Elon Musk had the seat right next to President Donald Trump on Tuesday as the White House hosted the leaders of America’s biggest artificial intelligence companies for a lunch that ended with a voluntary industry accord on AI safety.
A seating chart Trump posted on Truth Social placed Musk at the president’s left in the East Room, with Nvidia CEO Jensen Huang on his right, according to an Associated Press reporter. Anthropic CEO Dario Amodei, OpenAI President Greg Brockman, Meta’s Mark Zuckerberg, Google’s Sundar Pichai, Microsoft’s Satya Nadella and Amazon founder Jeff Bezos also attended, along with Vice President JD Vance and House Speaker Mike Johnson.
🚨 Elon Musk is currently speaking to the media alongside President Trump after a meeting with AI Leaders in Washington today
Trump says AI is now being called “Super Intelligence” or SI pic.twitter.com/woJJqUVP9B
— TESLARATI (@Teslarati) September 29, 2026
After the lunch, Trump told reporters outside the West Wing that the executives had signed “The White House Accord on Superintelligence: A Joint Commitment on Frontier SI Responsibilities.” Johnson described it as a voluntary statement of principles built on “robust internal controls and layers of internal and external review,” while Zuckerberg said company boards would independently review reports from outside auditors. Trump called the document “morally binding,” said he would name a new AI czar within days, and signed an executive order formally renaming artificial intelligence “super intelligence,” CNBC reported.
Musk was not in the room for Tesla alone. Since SpaceX absorbed xAI, he runs the company behind Grok and one of the largest AI training operations anywhere. On September 25, he said another 220,000 Nvidia GB300 chips would come online at Colossus 2 within a week, with more expected in November and December.
“I think it is worth highlighting the positive benefits of A.I. … S.I., pardon me.”
“Thank you.”@elonmusk catches his own slip after calling the technology “A.I.” while speaking alongside President Trump and other tech leaders, quickly correcting himself to “super… pic.twitter.com/fH7CFileNb
— Fox News (@FoxNews) September 29, 2026
SpaceX confirms third massive compute deal at Colossus data center
Musk also used the trip to restate his energy ambitions. “SpaceX is aiming together with Tesla to do 200 gigawatts of solar production per year,” he said at an event in Washington. It is the same combined target he laid out that feeds directly into Terafab, the Tesla and SpaceX chip venture that will need enormous amounts of power.
The showing between Musk and Trump has come a long way, since the two had the very public split in mid 2025 after Musk opposed the “Big Beautiful Bill” and left DOGE. They reconciled at Charlie Kirk’s memorial that September, and Trump later called their relationship “good”. Since then, Musk has joined Trump’s China delegation in May and attended last week’s White House state dinner for Chinese President Xi Jinping.
For Tesla, that access to government official could pay dividends. As Teslarati noted in January, federal autonomy rules, NHTSA oversight and a single national standard for driverless vehicles all run through an administration Musk can more easily reach directly as Tesla works to scale Robotaxi and Cybercab beyond Texas.
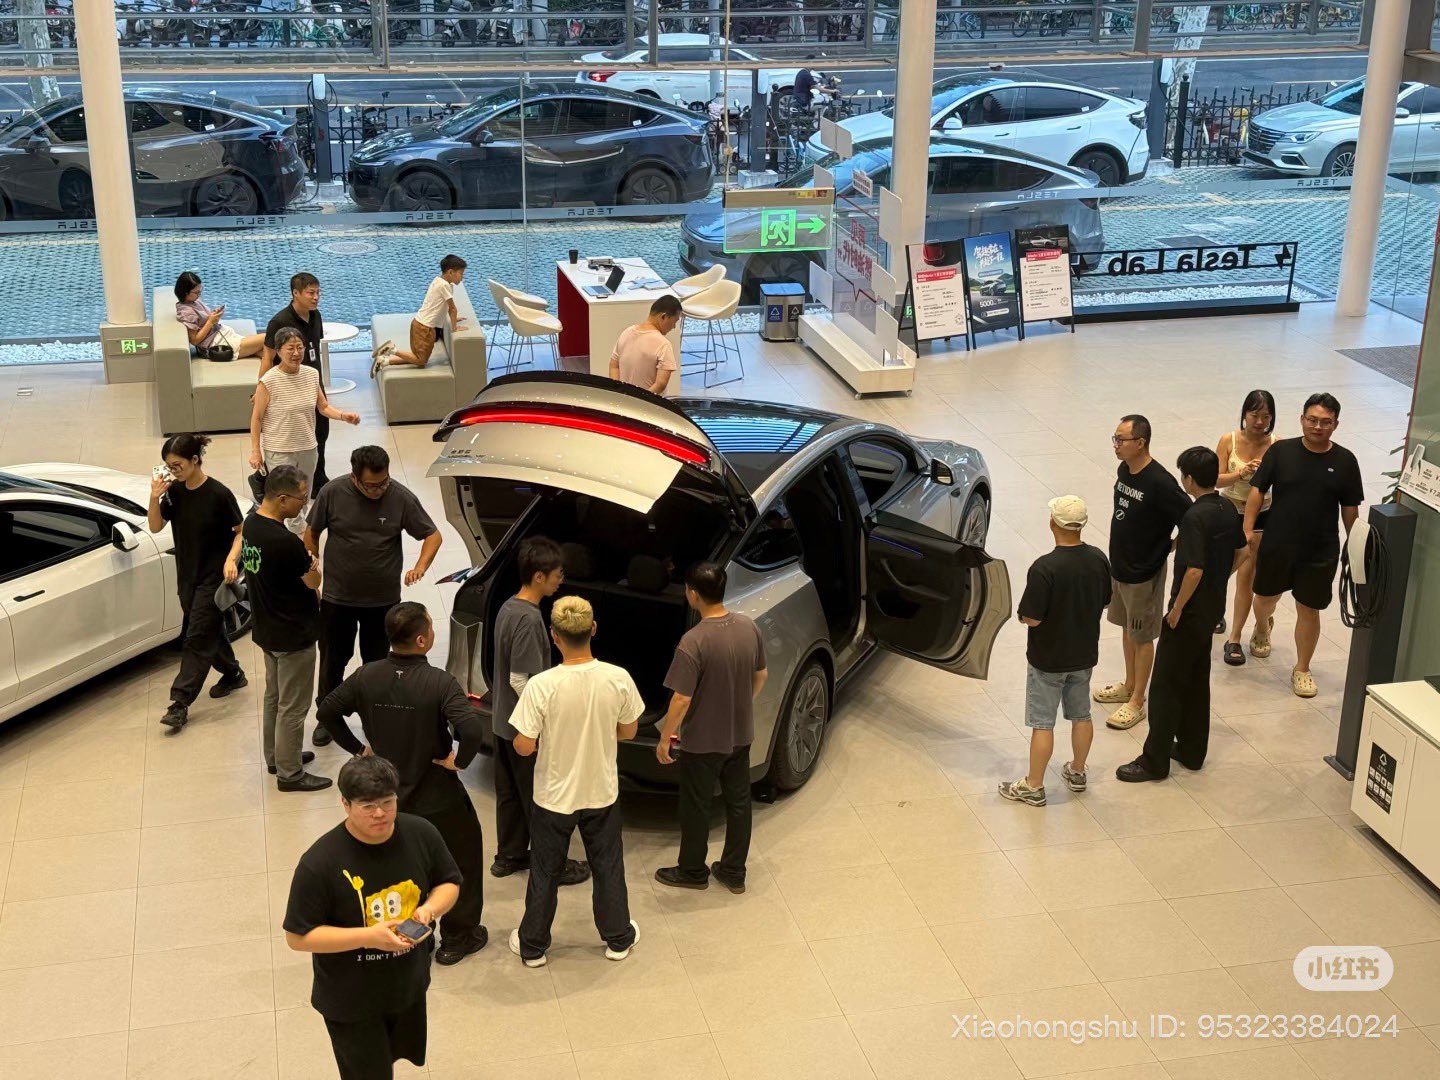
Tesla (NASDAQ: TSLA) showrooms have been picked clean ahead of the end of the third quarter of the year, as demand looks to be strong and delivery estimates for new vehicles are pushed into late 2026 and early 2027.
Tesla appears to have sold out of many of its Model 3 and Model Y trim levels in the United States, as only the Model Y RWD and Model Y All-Wheel-Drive are available for delivery before the end of the year.
Additionally, many showrooms are either completely empty or void of all but just one demo unit within the buildings themselves in an effort to bolster what could be one of Tesla’s best quarters in vehicle deliveries in recent memory.
I’m at Tesla right now and when I walked into their showroom I was shocked to see it basically empty.
I asked one of the people working there where all of the cars are “Gone – it’s the end of the quarter and we’ve sold out of everything… including the display vehicles”So… pic.twitter.com/rN7s3gE6sJ
— Devin Olsen (@DevinOlsenn) September 25, 2026
All the cars are gone from Tesla Century City!
All they have is Model Y L, a self-driving video playing on the background. I guess the best product is no product. Either that or they just sold the showroom cars. pic.twitter.com/mzCjWaXwww
— Whole Mars Catalog (@wholemars) September 26, 2026
Show room is empty. I asked and they have sold the demo cars too. Delivery numbers better be outstanding! pic.twitter.com/jq5N28Q6tZ
— Electric Brawl (@3lectricBrawl) September 22, 2026
Additionally, when I spoke to the guys at Tesla Mechanicsburg two weeks ago, when I returned the Model Y L, their third hauler of the week had just arrived, and every vehicle on it, along with every vehicle in their delivery lot, was accounted for and had a name attached to it for delivery.
Talking to the guys at the Mechanicsburg showroom on Friday, they couldn’t believe they had ANOTHER hauler coming in of cars for delivery—and each was accounted for
No car just sitting in inventory. They’re expecting a BIG quarter, and this is more than just the Y L https://t.co/ce801GkKVv
— TESLARATI (@Teslarati) September 21, 2026
Tesla saw a 25 percent increase in deliveries in Q2 compared to the same quarter the year before. The vast majority of the 480,126 units it delivered, 467,762 vehicles to be exact, were the Model 3 and Model Y.
In Q3 2025, Tesla delivered 497,099 vehicles, once again a figure that was dominated by the company’s two mass-market vehicles. Analysts have unusually wide predictions for this quarter, likely because so many firms missed the Q2 delivery figure by such a substantial margin; Wall Street predicted 408,000 cars, while Tesla delivered 480,000.
Goldman Sachs has Tesla slotted for 435,000 deliveries in Q3, while JPMorgan said it anticipates 482,000. The median guess is about 449,000 deliveries for Q3.
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.

Starlink launches Communities Program for passive income through internet sharing

Tesla just made its headlights even better through a software update


