News
Tesla’s 2020 Aftermath: A look at the shorts who said 500k was ‘absurd’

Tesla’s 2020 showing has created an aftermath of reflection from bulls and bears alike. Despite the company coming off of a record year with a massive 500,000 vehicle delivery and production rate, which was considered “absurd” by some short-sellers in years past, Tesla proved the doubters wrong once again.
Everyone knows that the stock market is really an unpredictable and unfathomably tough thing to read. Some of the world’s best analysts can misread even the slightest bit of data and be miles off of what a particular stock accomplishes. Tesla, which is one of the more polarizing stocks despite its 700% climb in 2020, has had doubters since day 1. The difference between doubters of Tesla and doubters of other companies is that Tesla shorts and bears are some of the most vocal on Wall Street because the company’s momentum and hype have been talked about for nearly a decade.
2020 was easily the toughest year for the U.S. automotive market since the Great Recession of 2008. Tesla was one of the few companies that accomplished the feat of sustaining growth through the year of the COVID-19 pandemic, which crippled many industries, not just the automotive one, for most of the year. However, doubts on Tesla set in way back when the company started in 2008. Six years after Tesla built the original Roadster, analysts were still curious about the automaker’s capabilities moving forward and doubted that it would be able to scale its production to half-a-million cars by 2020. The old saying goes, “hindsight is 2020,” and as Tesla reached its goal for the year, it is easy to sit back and judge those who were wrong. However, their reasoning for not reaching 500,000 vehicles was completely flawed, and everything Tesla said it would do years ago has been accomplished.
Mark Spiegel called 500,000 cars in 2020 “absurd”
Mark Spiegel is a notable Tesla short-seller and has been bearish on the automaker’s stock for years. In 2014, Spiegel posted an article to Seeking Alpha, titled, “Why Projections For Tesla To Sell 500,000 Cars In 2020 Are Absurd.”
Spiegel used data like the compound annual growth rate to support his evidence, stating, “If Tesla sells 35,000 cars this year, 500,000 sales in 2020 would imply a six-year CAGR of 56%.” Additionally, Spiegel did not believe that Tesla could scale growth at that rate in six years because “no complex product manufacturer has ever grown that quickly from a revenue base of $3 billion or more.” But hey, there is a first time for everything.
Microsoft was able to scale its CAGR by 32.1% from 1993 to 1999, which is a six-year time span and was identical to Tesla’s outlook that was challenged in the 2014 article. While Microsoft managed a remarkable 32.1% CAGR because of the evergrowing popularity of the computer and other technology, Tesla’s overwhelming growth throughout the same timespan was due to tech developments, industry influence, proving affordability of electric cars, and a consistent growth rate that proved the company was here to stay.
Spiegel’s outlook for 2020 was 186,000 cars sold by Tesla, but the company managed to nearly accomplish this figure in Q4 alone, as it delivered 180,570 cars in the final three months of the year. Spiegel was way off in his predictions, and Tesla’s domination in 2020 was just one of many examples of analysts getting it completely wrong.
Tesla wasn’t a prime candidate for scaling its products, according to Thomas Bartman
In an April 2015 article in the Harvard Business Review, Thomas Bartman wrote an opinionated piece called, “Why Tesla Won’t Be Able to Scale.” Bartman claimed that Tesla’s EVs were “not actually disruptive, which will likely cause it to struggle to scale.” Bartman didn’t have the Model 3 to use as a benchmark at the time, but he doubted that Tesla would be able to sell a vehicle for $35,000, which it did.
“Tesla plans to launch a ‘mainstream’ luxury car, the Model 3,” Bartman wrote, “which it estimates will cost $35,000, although analysts have begun to question the feasibility of reaching that price point.” Tesla did discontinue this variant in late 2020, but the Standard Range Model 3 was available for over three years. The Standard Range+ was only $2,770 more and was more popular because of the range. Also, the SR was not listed on Tesla’s website and had to be ordered in a showroom or over the phone.
Bartman believed that Tesla had launched two good vehicles in the Model S and Model X, but legacy auto would quickly catch up after a few years. However, this has been proven wrong repeatedly, as companies like Mercedes-Benz and Audi have failed to launch effective and competitive EVs that are comparable to Tesla’s models globally. The Model 3 continues to dominate in China and the U.S., and the Model Y is gaining plenty of momentum as it nears the one-year mark since its first deliveries.
Tesla China Model Y attracts flocks of customers in local showrooms
“As Tesla attempts to scale, it’s likely to discover that its internal impediments, combined with competitor responses, make it much harder than anticipated,” Bartman said. “The symptoms of these problems will manifest as product launch delays, cost overruns, and higher than expected prices.”
The only issue is that Tesla was able to internally combat production issues, even though Elon Musk has admitted many times that Model 3 manufacturing was “production hell.” The company has effectively beaten all of its competitors to launching an effective and cost-worthy electric car by launching four of them.
Hindsight is 2020
With 2020 over (thank God), Tesla and analysts are already looking forward to the new year. 2021 has plenty in store for Tesla: Two production facilities in the U.S. and Europe are set to begin manufacturing efforts, the launch of the Cybertruck at the tail-end of the year, and a possible refresh of the Model S and Model X. Moving forward, Tesla shorts may be more cautious, especially considering their traumatic $38 billion loss this year.

Elon Musk said weeks ago during SpaceX’s third-quarter earnings call that the company’s Grok Bot, its autonomous AI Agent platform, was showing “the fastest growth of a product” that he’d ever seen in his life.
Now, SpaceXSI is scaling back Grok Bot users’ weekly limits, much to the surprise of those who have relied on it to take away monotonous tasks in their lives.
Elon Musk’s terse November 1 reply on X captured a sharp tension in the early days of agentic AI. Responding to a user who asked for a Grok Bot usage reset after hitting 100 percent with four days still left on the weekly cycle, Musk wrote: “The cost of serving Grok Bot was unsustainably high relative to revenue.”
@DogecoinNorway The cost of serving Grok Bot was unsustainably high relative to revenue
— Elon Musk (@elonmusk) November 1, 2026
The post arrived amid a wave of similar complaints from paying subscribers whose meters had jumped unexpectedly toward or to the limit, sometimes overnight and with little corresponding activity. It also stood in clear contrast to statements Musk had made only days and weeks earlier.
On the SpaceX third-quarter earnings call in mid-to-late October, Musk had described Grok Bot in almost the opposite terms. He called it “the fastest growth of a product that I’ve ever seen in my life” and said he had “never seen anything grow this fast.”
Company figures put paid weekly users at roughly 800,000 earlier in the month, more than doubling over the prior period. Daily active users had climbed from under 100,000 in early September to over 600,000 by late October.
Musk emphasized that the product has no free tier and that users appear to be getting real value beyond what they pay. In other remarks, he noted that usage per user was rising rather than declining, the opposite of the usual decay pattern for new software.
Grok Bot, launched around August, functions as an always-available agent with its own persistent cloud computer; it can schedule, research, shop, browse, and execute multi-step workflows even after the user steps away. Access is bundled into X subscription tiers (roughly $30, $100, and $200 per month) and certain Cursor plans, drawing from shared weekly usage pools whose exact sizes have not been publicly detailed.
The economics of that model are what Musk’s November 1 post put in the spotlight. Agentic systems burn far more compute than ordinary chatbot exchanges. Each task can trigger repeated model calls, tool use, web actions, and sustained background work.
When growth is as rapid as Musk celebrated, the absolute compute bill scales quickly even if average revenue per user stays fixed under flat monthly subscriptions. Industry observers noted the opportunity cost as well: the same GPUs can be rented to other AI labs at higher rates.
A simple back-of-the-envelope comparison circulating after the post illustrated the gap: if every reported daily user paid the top tier, annualized subscription revenue would still be modest relative to the scale of compute infrastructure SpaceX is building and leasing to companies like Anthropic.
Some users also reported possible dashboard anomalies around the same period, though Musk’s framing treated the underlying cost-revenue imbalance as the core issue rather than a pure metering glitch.
The juxtaposition is the core of this exchange. Within roughly two weeks of publicly framing Grok Bot as an unprecedented success with strong unit economics and no free tier, Musk acknowledged that serving the same product had become unsustainable relative to the revenue it generates.
For the broader industry, the episode underscores a structural challenge of the agent era: demand is real and growing faster than many expected, yet the cost of fulfilling that demand through always-on, multi-step agents can outrun subscription pricing before companies can adjust limits, introduce metered billing, or raise prices.
Musk’s reply did not promise an immediate reset or higher allowances; it simply stated the constraint. In doing so, it supplied a rare, explicit public data point on the unit economics of a high-profile AI agent just as adoption numbers were still being celebrated as the fastest in Musk’s experience.
The tension between rapid, paid growth and the compute required to deliver it is now on the record.
News
Tesla owners who tap Emergency Drive Away for fun are in for a surprise
Tapping Activate on Tesla’s Emergency Drive Away reportedly triggers a $539 service bill without moving.

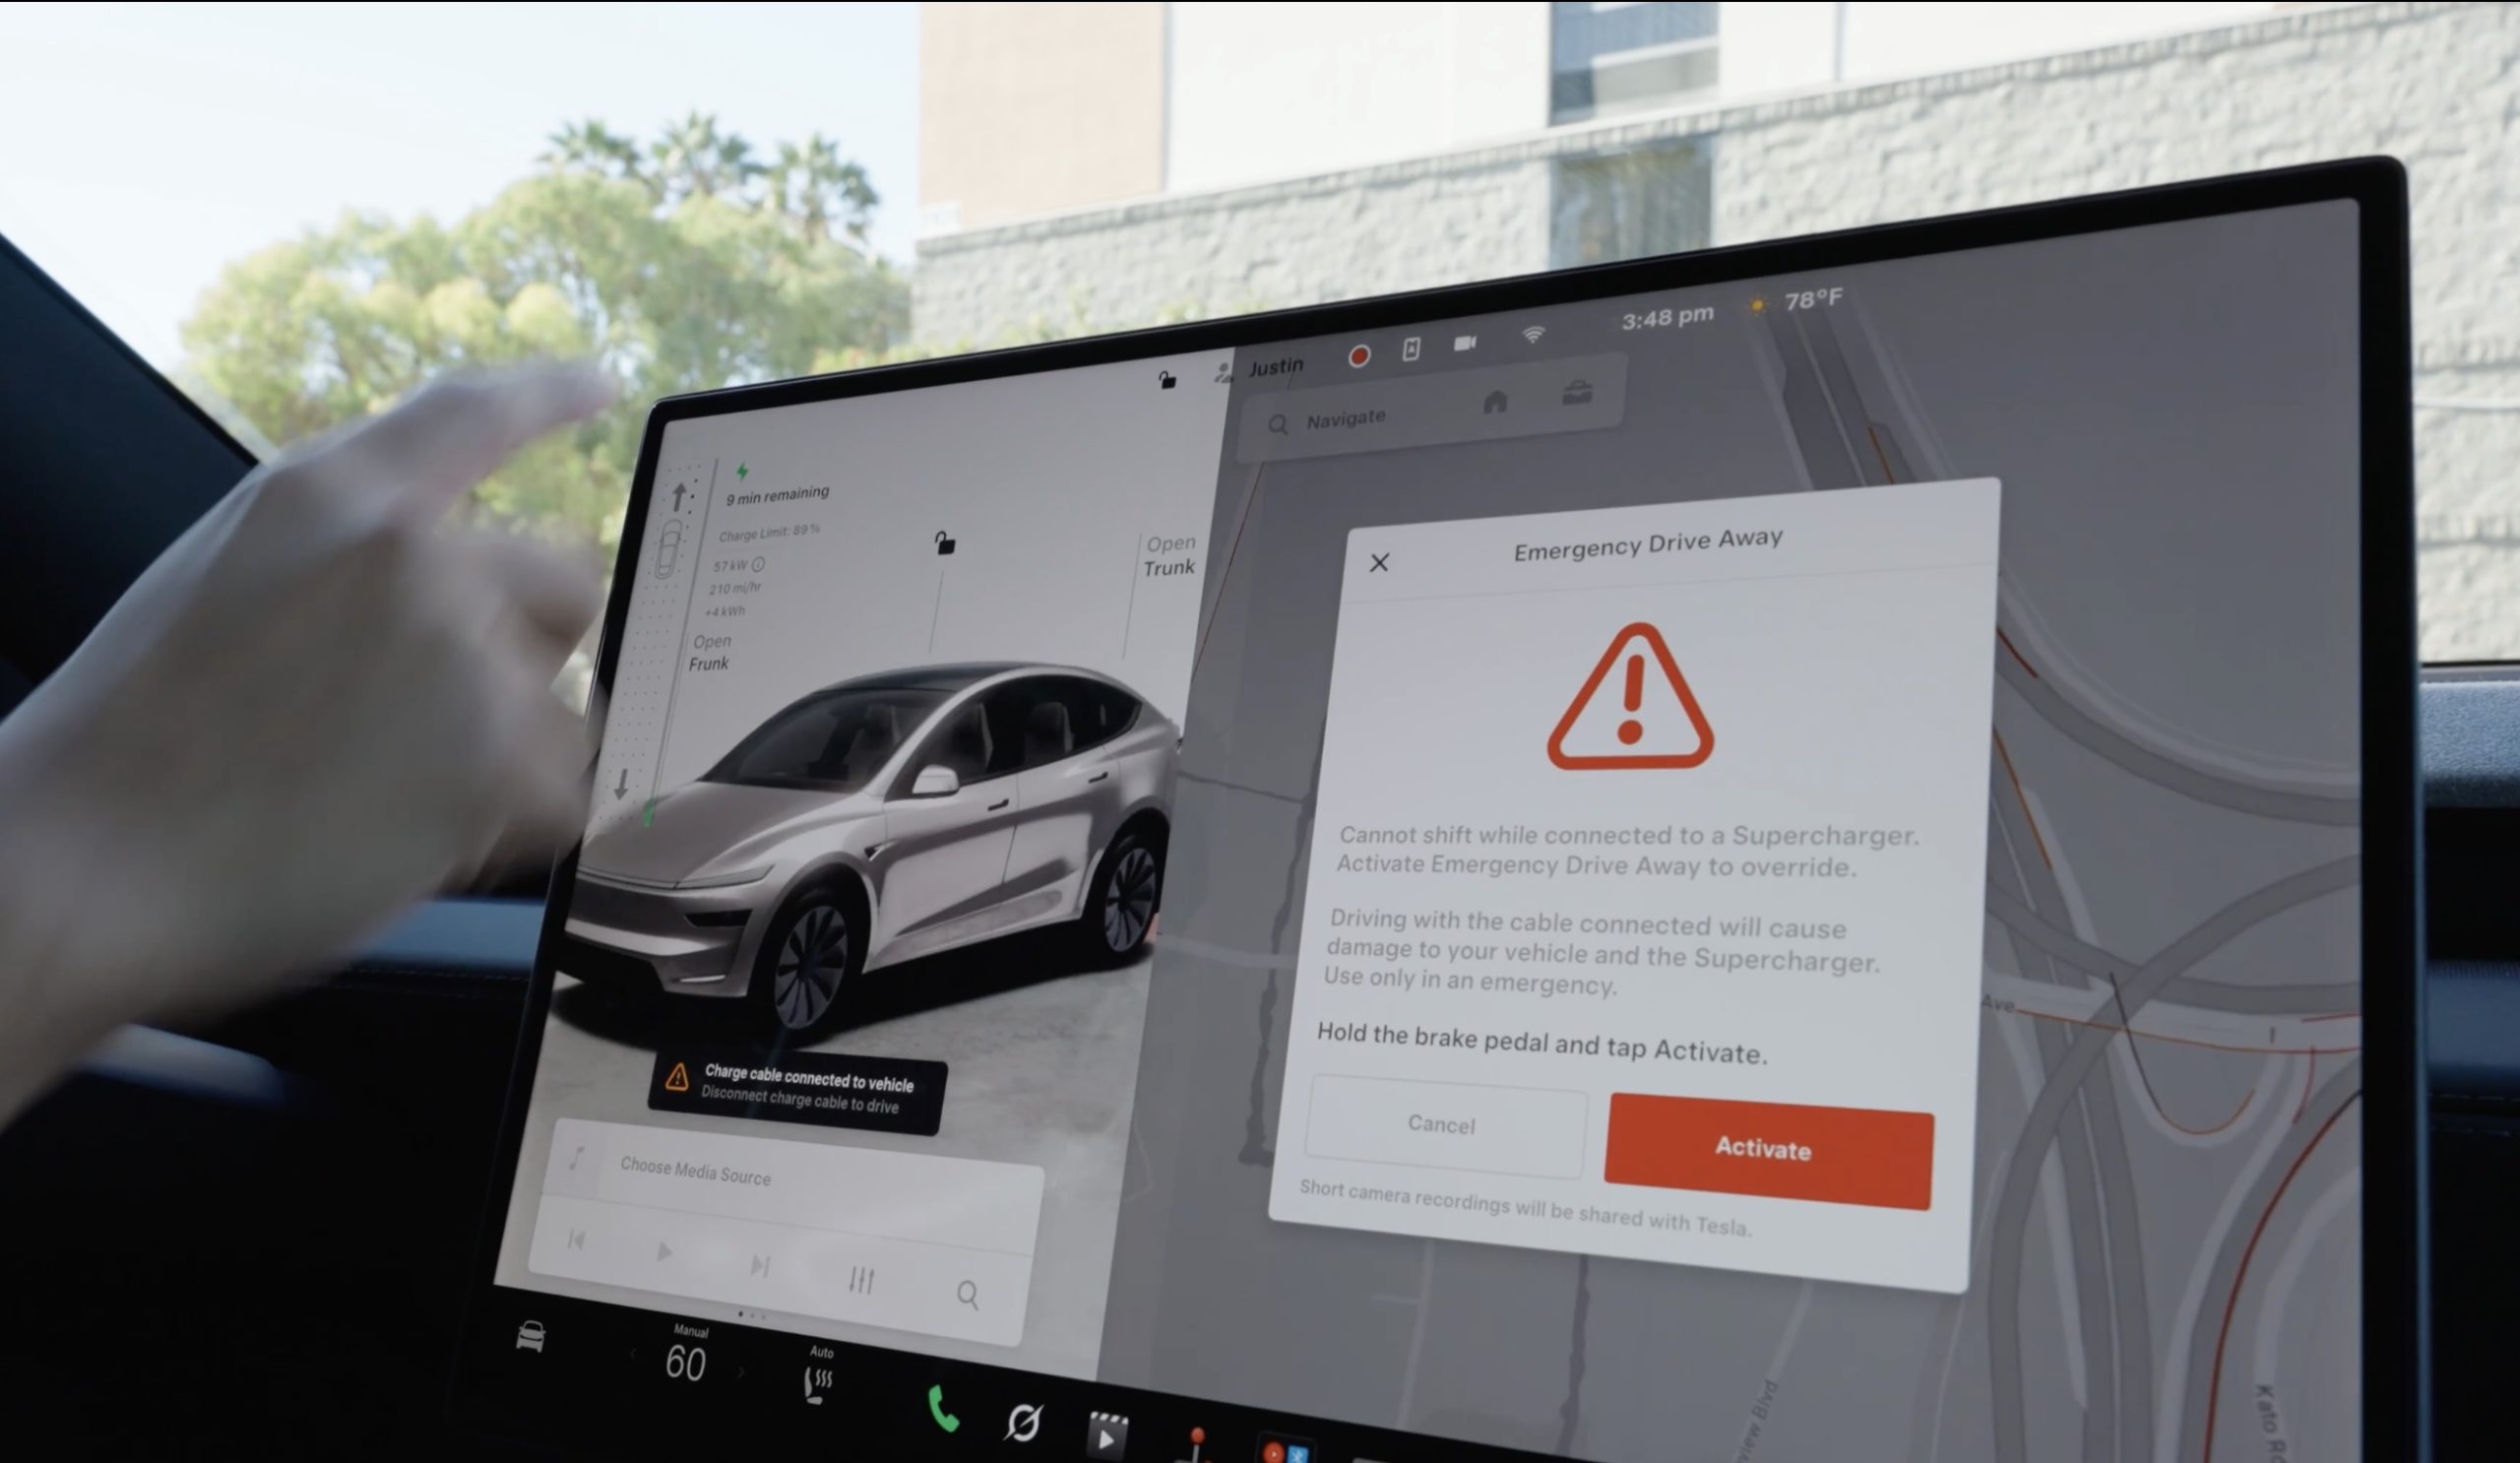
Tesla owners who press Activate on Emergency Drive Away may be on the hook for a service bill even if their car never leaves the Supercharger stall.
Yaro, who posts about Tesla service cases on X as @Tutrifour, said a customer called after tapping Activate while still plugged into a Supercharger. The owner was about to pull away, remembered the cable was still connected and stopped. The car never moved, but the touchscreen showed a red alert reading “Emergency Drive Away has been activated” with “Service is required” underneath. A Service Mode screenshot showed the active alert BMS_a228_EmergencyDriveAwayServiceRequired, which Yaro said only Tesla Service can clear.
Here is a lesson to Tesla owners. Don’t press Activate on the new Emergency Drive Away feature on your Tesla because service charges $539 to inspect the charge port and to clear the alert. Yes, even if you didn’t move the car an inch. https://t.co/NZJENw4SQv
— Yaro (@Tutrifour) October 30, 2026
The cost of clearing it was the bigger surprise. “Don’t press Activate on the new Emergency Drive Away feature on your Tesla because service charges $539 to inspect the charge port and to clear the alert. Yes, even if you didn’t move the car an inch,” Yaro wrote. The $539 figure comes from that single case, and Tesla has not published a set price for the inspection or commented on the post. Yaro also noted that the car would still charge with the alert on screen.
Tesla launched Emergency Drive Away on October 1 with software update 2026.38.3, letting drivers pull away from a U.S. Supercharger with the cable still attached, as Teslarati reported. To use it, a driver shifts into Drive while connected, holds the brake and taps Activate. The prompt warns that driving with the cable connected will damage the vehicle and the Supercharger, and that short camera recordings will be shared with Tesla.
Tesla Charging has been clear about what follows a real activation. Repairs to a Supercharger stall can run up to $25,000 depending on the site, a service visit for the car’s charge port is mandatory, and deliberate misuse “will invoke additional penalties.” What the company had not spelled out is that the service requirement is triggered the moment Activate is pressed, not the moment the cable breaks away.
From an engineering standpoint, that is the cautious choice. Once Activate is pressed, the car cannot be sure the charge port latch was not stressed, so flagging it for inspection removes the guesswork. It also means the button carries a price on its own, which is a stronger deterrent against casual use than any warning screen.
Customer called because they have an active alert after tapping ACTIVATE on the new Emergency Drive Away feature. They didn’t actually drive away but were about to until they “remembered” they had the charge cable connected.
This alert can only be cleared by Tesla Service. https://t.co/SkHyJJPFwU
— Yaro (@Tutrifour) October 28, 2026
The report follows the feature’s first known real world use, when a driver in Austin during F1 weekend appeared to trigger it by accident and dragged the Supercharger cable along with the car. The Reddit user who filmed it said the driver seemed to have only half read the prompts.
For owners, the takeaway is to treat the red prompt as a stop sign. If it appears after shifting out of Park by mistake, shift back and unplug the normal way from the touchscreen, the Tesla app or the button on the charge handle. Activate is meant for moments when staying at the stall is the bigger risk, and Tesla is now pricing it that way.
Elon Musk
Elon Musk calls Earth’s data centers “peanuts” next to what SpaceX is planning in orbit
Elon Musk says SpaceX capex efficiency is underestimated as orbital data centers loom by 2028.
Elon Musk is pushing back on one of the biggest worries hanging over SpaceX stock. In a reply on X on Sunday, Musk said the company’s capital expenditure efficiency is severely underestimated. He was responding to a Milk Road Stocks post citing analyst Kyle Reidhead, who estimates SpaceX will need to spend roughly $470 billion over the next five quarters.
Reidhead built that figure around the target SpaceX set on its third quarter earnings call: 13 gigawatts or more of compute by the end of 2027. In his breakdown, Nvidia captures 83 to 89 percent of the spending. SpaceX ended the quarter with 1.7 GW of nameplate compute and guided to $35 billion to $40 billion in fourth quarter capex, as Teslarati reported.
Musk did not attach a number to his claim, but the earnings call shows the argument. CFO Bret Johnsen said new compute currently pays for itself in under a year at today’s pricing, and Musk said that window could shrink to six months next year. Using that pace, Reidhead argues about $230 billion of the $470 billion could come from operating cash flow and about $60 billion from SpaceX’s roughly $90 billion cash pile, leaving around $180 billion to borrow. Musk confirmed last week that SpaceX had already closed a new $40 billion debt raise to buy GPUs.
The ground buildout is not the end goal. It is what is meant to pay for the move to orbit. Replying on Friday to charts built from Sequoia partner Shaun Maguire’s SpaceX model, Musk wrote that “Terrestrial compute will be peanuts compared to orbital compute,” adding that orbital compute deployed per month “probably exceeds terrestrial around the end of 2028 and then far exceeds it in 2029.”
Maguire’s model shows how steep that path is. It has capex climbing from $88 billion this year to $290 billion in 2027 and $369 billion in 2028, with SpaceX burning $77.8 billion in cash this year and $122.6 billion next year before turning $114.9 billion cash positive in 2028. Musk’s response to the model was, “I think we can do better.”
The orbital half runs through Starmind. SpaceX plans to operate up to 1 million AI satellites flying in clusters of about 10, linked by roughly 10 terabits of bandwidth, with deployment of thousands of units starting as soon as late 2027 out of its Gigasat factory in Bastrop, Texas, according to SpaceX’s space safety page. Musk has said each Starmind spacecraft will carry more than 250 kW of solar power.
Getting there depends on launch volume. Maguire’s model assumes 250 Starship flights in 2028, up from two this year and 38 next year. The nearer test is financial: SpaceX guided to $33 billion to $37 billion in first quarter 2027 revenue, more than double the $14.58 billion it booked in Q3, and Musk reposted that guidance again on Sunday morning.

Grok Bot users hit with weekly limits early, Elon Musk explains what happened

Tesla owners who tap Emergency Drive Away for fun are in for a surprise


