Investor's Corner
Tesla Semi-truck: What will be the ROI and is it worth it?

Elon Musk’s announcement that a Tesla Semi will be arriving as early as September is the first step to what will eventually be a reinvention of an entire industry. We’ve discussed before what, exactly, that means, but given that the man in charge of the Tesla truck program is Jerome Guillen who has a history with Daimler (specifically Freightliner) and large Class 8 semi-trucks, it’s not hard to see where Tesla plans to go with this. That leaves only the question of how far, literally, they plan to take it. In tractor-trailer operations, there are two basic types of freight moving: short-haul and long-haul.
We’re going to look at each of these types of freight hauling and how the return on investment (ROI) for a battery-electric rig (such as that we expect Tesla to unveil) would be. If there is any. We’ll also consider what type of equipment this might entail, in a broad sense, and how that compares to current paradigms in tractor-trailer freight hauling.
Before we dive into that, a few words on what the trucking industry is like are needed. About 69.5 percent of the freight moved in the United States is moved on a commercial truck. The U.S. Department of Transportation (USDOT) also says that a staggering 92 percent of prepared foods are moved by trucks and 82.7 percent of agricultural products are moved by truck, as are 65 percent of pharmaceuticals. However you measure it, that’s a lot of goods being moved on highways and surface roads nationally.
Currently, the trucking industry is seeing a lot of change, internally, as technology improves the way that freight hauling operates. The Internet and faster communications, for example, has begun to erode the traditional consignee-broker-hauler paradigm in which someone with goods to haul contacted a freight broker who then contracted a freight hauler to move the goods, skimming a percentage off the top for the connection. The middleman is often cut out in today’s trucking, with many trucking companies having load brokers on staff.
Electronics and global positioning have also changed how trucks operate, with computers more efficiently organizing load and truck movements to minimize empty movement. The USDOT says that about 29 percent of all truck movement is pulling an empty trailer to or from a freight drop-off point, costing about $30 billion annually. That number, while high, has been dropping for some time and drops exponentially as networks of computers get more efficient at organizing trucking and trucking companies consolidate into larger and larger fleets.
Finally, we should note that the longer the average trip (load to delivery) is for a tractor-trailer, the faster the truck’s ROI for the owner. Shorter hauls have higher per-mile maintenance costs than do longer hauls. Even discounting the cost of fuel, that becomes true as equipment maintenance costs beyond engine and fuel are still higher with shorter distances. There are several reasons for this, including how often brakes are used, how much time is spent not working (idling or sitting), and higher incidences of accidents. To name a few. Many short-haul operations are undertaken on less than ideal roads and in areas where any kind of breakdown, including a flat tire, can mean hours wasted waiting for repair.
Knowing those things, we can look at potential ROI for both short-haul and long-haul Tesla electric semi-trucks.
Short Haul
Conventionally, short-haul operations are defined as being tractor-trailer shipments moving 250 miles or less and long-haul is defined as being those same types of shipments moving more than 250 miles. Each of these has sub-categories, of course, but in the main, those are the two major markets for large Class 8 semi-trucks pulling freight. It should be noted that the overlap between short-haul and long-haul is large, as many short-haul shipments are being carried to a distribution location where it’s reassembled for longer distance hauling.
Of the two operations, short-haul has the most diversity in terms of machines used and types of freight carried. It’s in this category that we find items as aggregate as grain freshly harvested from fields to stones to specialized equipment being carried. Sometimes by the same truck and driver over the course of a year’s work. It’s also in this category that we find specialized rigs meant for entering pit mines, climbing steep grades on primitive dirt roads, moving overweight and outsized items, and so forth. For the most part, trucks in this category are “day cabs” meaning they have no sleeper unit attached for the driver to use as a rest quarters when not at the wheel.
So far, the electrified Class 8 vehicles we’ve seen actually enter the market have nearly all fallen into the short-haul category. These have included battery-electric, hydrogen fuel cell, and hybrid units working as “yard dogs” moving trailers around a dock area, as portage trucks moving containers and freight out of port to staging areas or local distribution centers, and local area urban and suburban delivery vehicles. Currently, there is a large push in California to make all port vehicles (including container-moving trucks) as zero-emissions as possible.
The good news for battery-electric truck makers and those who aspire to become them is that, according to the USDOT, about half of all of the shipments (by value) is moved less than 250 miles. That accounts for about 80 percent of the weight being moved around the country. The bad news is that in this segment, less is paid per ton for that freight to be moved and, according to the American Transportation Research Institute, this segment only accounts for about 25 percent of the trucks on the road. Equipment age also tends to be higher in this category, with trucks being used for more years (and generally fewer miles) than compared to long-haul trucks.
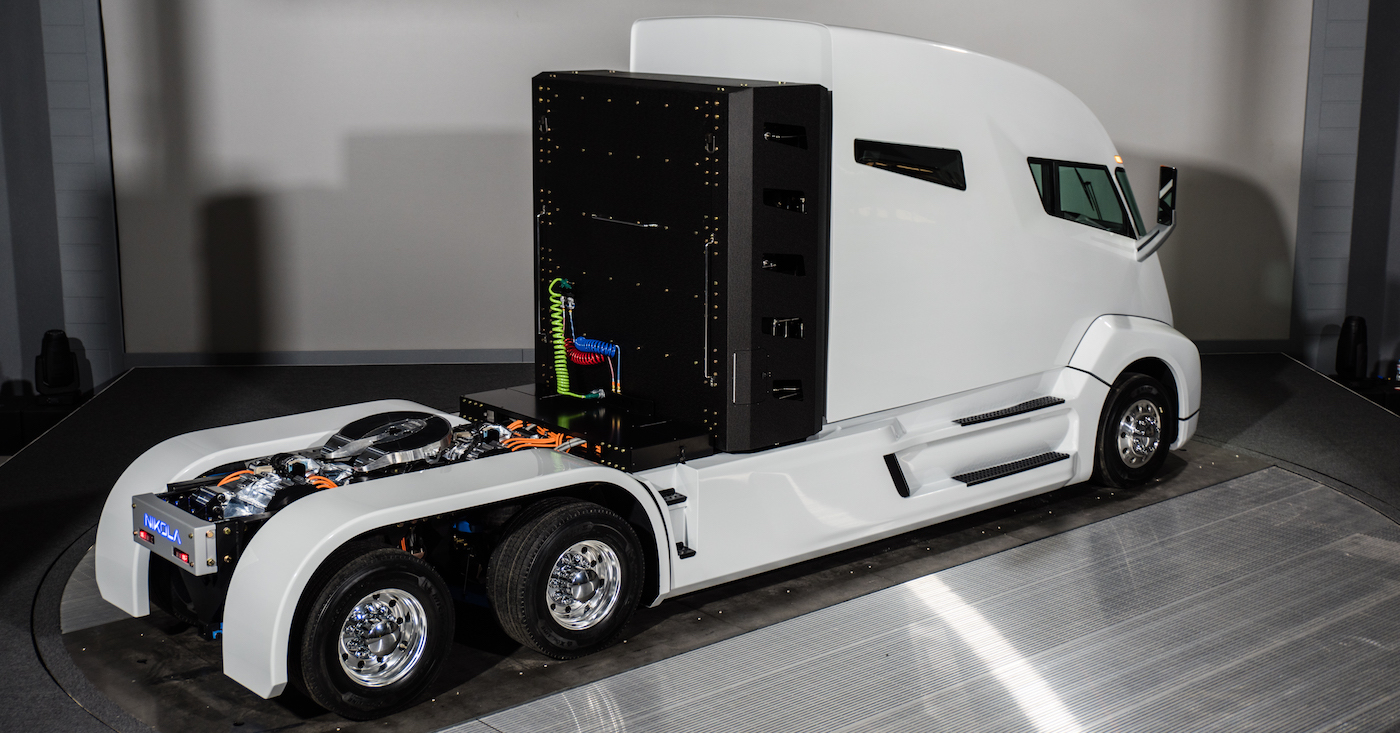
Nikola One all-electric Semi truck
In terms of cost, outside of maintenance, the most expensive items for a tractor-trailer, whether short- or long-haul, are fuel (38 percent), driver wages and benefits (34 percent), and truck-trailer lease payments and insurance (14 percent). These costs are about the same no matter what the truck is used for in most conventional operations, short-haul or long. Maintenance is about six percent higher in short-haul operations when compared to long-haul and insurance is usually a bit higher(1.5 percent), but not by so much that it can’t be averaged between them without skewing the numbers.
We can safely assume that a battery-electric semi-truck will have a higher price tag than its diesel-powered counterpart, which itself averages about $150,000 new. How much larger the electric truck would be is mostly conjecture, but we can probably be considered conservative to say it’s up-front costs will be at least 50 percent higher ($225,000) due to the expense of the batteries. Morgan Stanley’s report on electric and autonomous trucking assumed $75,000 for 500 kWh of battery storage, translating to roughly 150 or so miles of range in a fully loaded (80,000 pound) semi-truck. Given the current lithium crunch and the likelihood that economies of scale will take a lot of time to come to fruition, it’s easy to predict that more than half the Tesla Semi’s cost would be in batteries should it aim for a 250-mile range.
Over time, of course, that larger up-front price tag would be returned with fuel savings. In short-haul operations, about four years (250,000 miles) would be required to pay off $100,000 in battery premium with fuel savings. There are, however, other costs that would rise with the higher price of the rig. A higher-priced rig will have higher lease payments and higher insurance costs for replacement. This would stretch the ROI of the short-haul truck, by roughly another year, making it a five year investment return. If the truck stays in operation for the typical usage cycle in this segment, however, that would mean the truck pays for itself in about two thirds (70 percent) of its intended lifespan. Some percentage of the maintenance would also be lower in cost due to the nature of the electric truck, but much of it (tires, drivetrain, brakes, etc.) remains stagnant, further whittling at that ROI timeframe.
By and large, most forward-thinking fleet managers would jump at that. With one point of caution: by nature of their business and the long timeframes involved, most fleet managers are averse to change on a large scale. A few EV trucks here and there to prove out the technology and make the suits and ties happy are one thing. Jumping whole hog into the change is quite another. It would take some time (likely years) for fleet managers of short-haul fleets to decide that battery-electric trucks (or any type of unconventional powertrain) is a healthy decision. That, more than anything, will be the major delay towards adoption of something like a Tesla Semi.
Long-Haul Operations
Assuming that a Tesla Semi could be capable of hauling freight for 500-1,000 miles on a charge (the average long-haul trip is 600 miles per day), it would jump into a segment of trucking that accounts for more ton-miles than any other type of freight movement and that is growing faster than any other segment of commercial transportation in terms of both value and weight being moved. Further, the average turnover for a tractor in the long-haul business is 6.6 years (ATRI numbers) and the average mileage is over 110,000 miles per year per truck. ROI is typically faster as well, given the lower costs versus the miles driven.
Coming up with an ROI for a long-haul electric semi-truck is much trickier here and may be nearly impossible without knowing more about the EV truck to be used. At this stage, a battery-electric Tesla Semi would be nearly impossible for long-haul given the size and thus weight of the batteries required. So something involving very fast charging, battery swapping, or similar would be required. That adds costs to the equation that we cannot easily quantify without knowing what those logistics are.
What we can easily project is that the cost-benefit for a Tesla Semi in a long-haul scenario would not likely be nearly as compelling as it is for a short-haul fleet manager. A typical over-the-road truck sees about a million miles during its lifespan with a cost of about $400,000 in fuel and $100,000 in maintenance (ATRI) during that time. Most fleets own the truck for about seventy percent that time (700,000 miles), on average. So the cost of a truck, in terms of purchase price, fuel, and maintenance over its expected fleet lifespan is about half a million dollars ($280,000 fuel + $70,000 maintenance + $150,000 purchase = $500,000). This might begin to look very close to break even on a higher-priced EV truck by comparison, which would very likely save on fuel but would have higher up-front costs in balance. Further, those fuel savings might not be as good given the likelihood that logistics like battery swapping or more frequent stops for plugging in would be required.
Conclusion
A Tesla Semi would likely have a good return on investment for any fleet manager who is willing to look over the long-term and consider the cost-benefit. For the short-haul manager, however, the potential ROI is far more provocative than it would be for the long-haul manager. We can see a clear business case for a Tesla Semi for a large proportion of the short-haul industry, though we do caution that it will likely take some time for those in the industry to cast anything but a dubious eye towards an unconventional powertrain.

Give the gift of Tesla upgrades.
Shop for someone else or treat yourself. Get more shopping power with a Teslarati gift card.
Elon Musk
Elon Musk reveals Tesla’s next vehicle without a steering wheel
Elon Musk says Tesla plans a driverless Model Y for families too big for Cybercab.

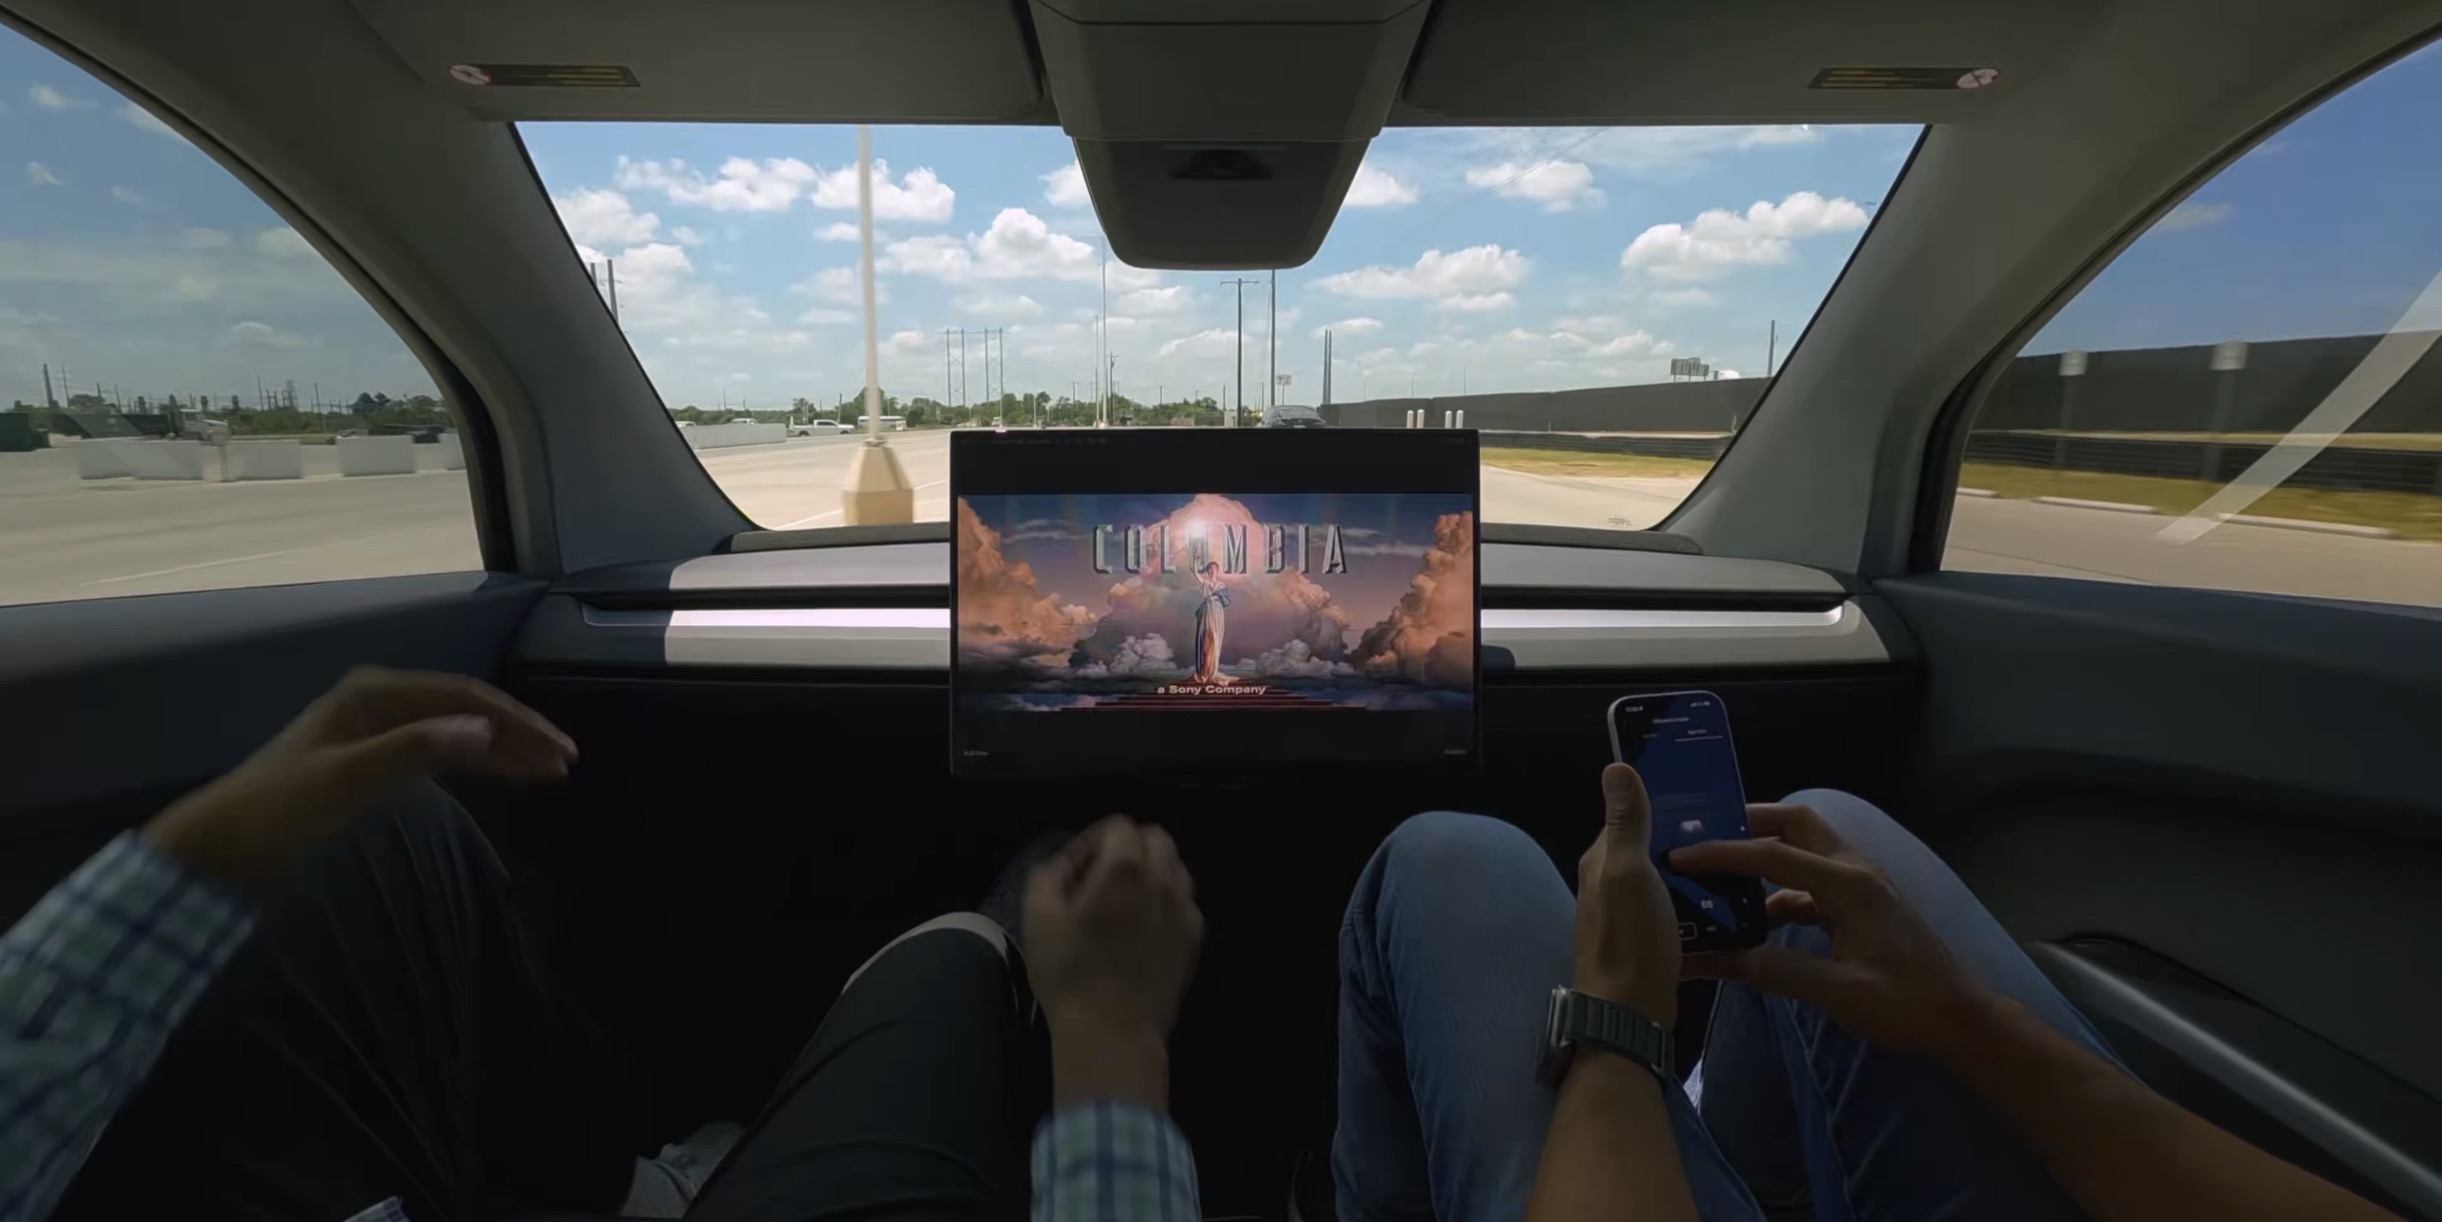
Tesla is planning a driverless version of the Model Y with room for six or seven people, Elon Musk said this week, giving families and groups an alternative to the two-seat Cybercab. Speaking remotely from China at the New York Times DealBook Summit on Wednesday, Musk said the vehicle would have no steering wheel or pedals. He did not give a launch date, price or production location.
The idea came up when Andrew Ross Sorkin asked whether Tesla would eventually stop selling conventional cars as it shifts Cybertruck capacity toward the Cybercab. Musk defended the two-seat design, saying average occupancy is about 1.2 people per car and that a two-seater covers roughly 90 percent of passenger miles. Bigger groups, he said, would be served by the larger autonomous Model Y.
Sorkin also mentioned he had ordered a Model Y L for his family and was still waiting on it. Musk called the six-seat, long-wheelbase SUV Tesla’s most popular car and suggested all Model Y production might need to move to the longer version. “It’s what most people seem to want,” Musk said, though he did not announce any change to Tesla’s production lines.
A driverless Model Y would add a third vehicle to Tesla’s autonomous lineup. Model Y Robotaxis already run 24 hours a day in eight cities, and Cybercab rides expanded to Dallas on Thursday after launching in Austin in September, as Teslarati reported. Tesla also began inviting select customers to buy a Cybercab for personal use last week at $29,990, with deliveries targeted for December.
Musk also addressed whether a Tesla and SpaceX merger should pay out under his compensation plan. Under the change in control terms of his 2025 CEO award, a deal could accelerate vesting, Electrek has noted. Musk said it should not. “I don’t think I should be compensated with any kind of award just for doing a merger. That would be unreasonable and not right,” he said. “You should keep your deals and stay true to your word.”
On the merger itself, Musk said the companies would “probably” be better together because of growing overlap in AI, chips and robotics, but stressed the decision rests with independent committees and shareholders, and that a Tesla vote “may or may not succeed.” Tesla holds its annual shareholder meeting on December 3, with merger talks reportedly progressing toward a possible announcement as soon as December.
Elon Musk
Tesla and SpaceX merger talks hit a new stage, and one hurdle remains
Tesla and SpaceX merger talks are reportedly advancing, and a deal could arrive by December.
Tesla and SpaceX are moving closer to a combination, with a deal announcement possible as soon as December, Bloomberg reported on Thursday, citing people familiar with the matter. The companies have also discussed a scenario in which the announcement slips into early 2027.
Boards and advisers on both sides are now working through the terms of the deal and the governance structure of the combined company, according to the report. One open item is how many SpaceX shares Tesla investors would receive. Bloomberg had previously reported that the two companies were aiming to announce a deal in the first half of next year and close it before the end of President Donald Trump’s term, so a December announcement would pull that schedule forward by months.
Tesla shares rose as much as 1.9% to $398.35 after the report, while SpaceX gained 0.6% to $140.63. SpaceX carries a market value of about $1.9 trillion following its June IPO, and Tesla is valued at about $1.55 trillion, which would make a combination the largest corporate deal on record. Neither company responded to requests for comment.
The talks became official on October 20, when Elon Musk said on SpaceX’s third quarter earnings call that both companies had formed special committees of independent directors to study a merger, as Teslarati reported. Musk said he could not take part because he is “a conflicted party” and called the process “an odd kabuki dance.” He also noted that Tesla would need approval from 50 percent of all outstanding shares, a bar the company missed in 2025 when a board declassification proposal won support from only 39.4 percent.
China remains the biggest structural problem. Bloomberg’s sources said the companies still need to work out how to isolate Tesla’s large and profitable manufacturing business in China from SpaceX’s U.S. government and defense contracts. JPMorgan analyst Rajat Gupta described those two factors last month as “key dynamics that are at odds with each other” for regulatory and shareholder approval. Musk has repeatedly said Tesla has no plans to separate its China business, a position he restated in August after ARK Invest predicted a merger announcement before the end of the year.
Washington adds another layer. Democrats took control of Congress in this month’s midterms and have pledged to investigate Musk’s business and political activities, which could bring added scrutiny to a deal involving one of the Pentagon’s most important launch and satellite contractors.
The report also lands three weeks before Tesla’s December 3 annual meeting at Giga Texas. That ballot has only three items, led by the re-election of Musk, board chair Robyn Denholm and JB Straubel, and includes no merger proposal. Any deal announced in December would likely require a separate special meeting for Tesla shareholders to vote on it.
The two companies already share a growing list of projects, including the Terafab semiconductor plant in Texas. Tesla’s next generation Roadster, which uses cold gas thrusters built on SpaceX hardware, turned up on display at SpaceX headquarters last month and has become one of the clearest public examples of that overlap.
Elon Musk
Nvidia’s board meets on Jensen Huang, and Elon Musk already has an answer
Elon Musk says it would be an honor to hire Jensen Huang amid Nvidia turmoil.
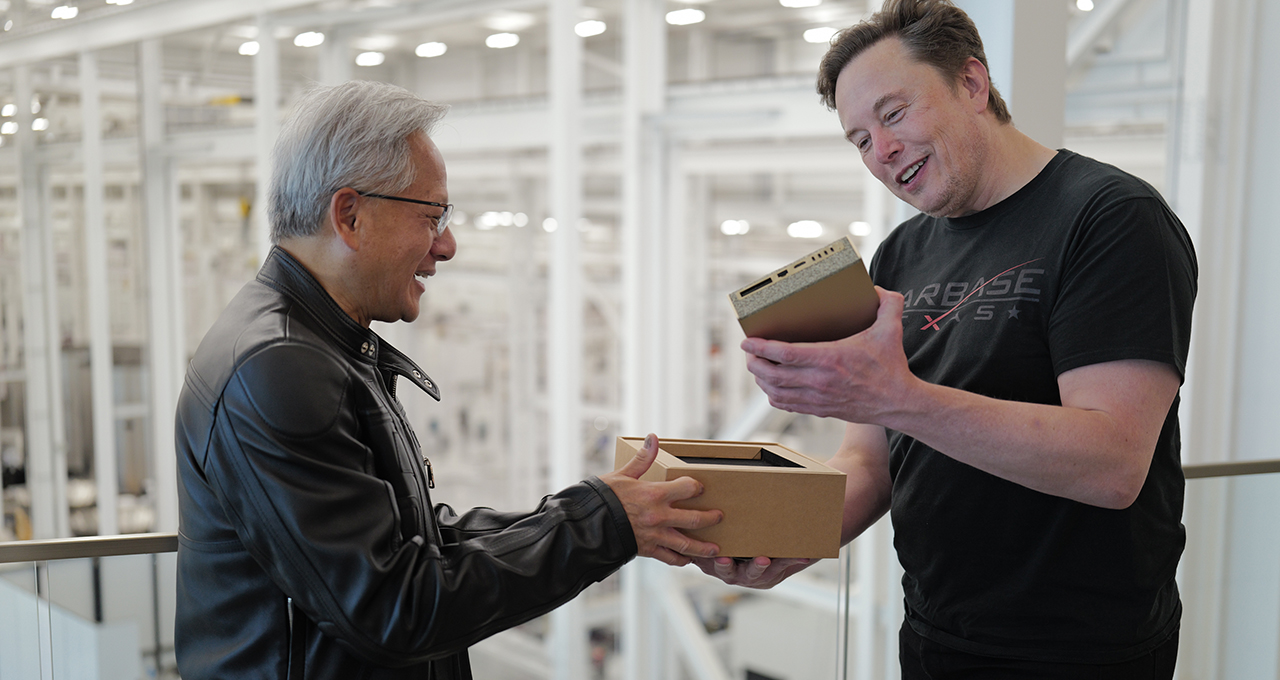
Elon Musk says he would welcome Jensen Huang at one of his companies if Nvidia’s board decides to push out its longtime chief executive.
On Wednesday evening, the financial account ZeroHedge posted “Elon please hire Jensen” on X. Musk replied roughly two hours later: “That would be an honor.” Neither Huang nor Nvidia had responded publicly as of Wednesday night.
Musk’s reply came as Nvidia’s board met to decide Huang’s future. The Wall Street Journal reported that directors were preparing to oust him following reports of two extramarital relationships. One involves Alice Huang, a Singapore-based businesswoman whom U.S. intelligence officials reportedly believe was working for China’s Ministry of State Security. The New York Times separately reported a relationship with Kimberly Powell, Nvidia’s vice president of health care. Huang acknowledged being unfaithful in a memo to employees on Sunday but gave no details.
@zerohedge That would be an honor
— Elon Musk (@elonmusk) November 12, 2026
Under Nvidia’s bylaws, a majority of its 11 directors can remove the CEO with or without cause. Bloomberg reported that the board has been working with an outside firm on possible replacements and may name an interim chief, with CFO Colette Kress seen as the likely pick. Nvidia shares fell more than 8 percent in extended trading, according to CNBC, and the company is scheduled to report quarterly earnings on November 17.
Musk has more riding on Nvidia’s leadership than most tech executives. In August, he told investors on SpaceX’s first earnings call as a public company that it would build its AI infrastructure exclusively on Nvidia hardware, calling Vera Rubin “the best architecture.” SpaceX is also working with Nvidia on the compute payload for Starmind, its planned orbital AI constellation. In October, SpaceX said it had a binding commitment for a roughly $40 billion lease of Vera Rubin GPUs and related equipment, with the leases expected to begin in the first half of 2027.
The scale of that dependence is already enormous. On its Q3 call, SpaceX said it was bringing roughly 200,000 to 220,000 Nvidia GB300 GPUs online each month and expects 2.5 to 3 GW of nameplate compute by the end of the year. That buildout is now reaching new sites like the proposed $24 billion power plant and supercomputer campus at Starbase.
The relationship between the two executives also goes back nearly a decade. Huang has often told the story of personally delivering Nvidia’s first DGX-1 AI supercomputer to Musk in 2016, when no other customer wanted one. “Nobody wanted to be part of it, except for Elon,” Huang said on the Joe Rogan Experience last December.
Musk did not say what role Huang might fill, and his reply stops short of a formal offer. Huang co-founded Nvidia in 1993 and still owns about 3.6 percent of its stock, so any move to a Musk company would depend on whether, and how, he leaves the chipmaker he has run for more than three decades.

Tesla Full Self-Driving v15 rollout begins: full release notes and improvements

Tesla Full Self-Driving v15 gets release date from Elon Musk


