News
SpaceX worth $33B after raising more than $1B for Starlink and Starship

Since April 2018, SpaceX has successfully raised more than $1.24 billion through the sale of equity, likely sold to investors by extrapolating the company’s current record of success to include the potential of its next two products, Starlink and Starship.
Thanks to SpaceX’s successful streak of fundraising, the company is now valued at $33.3 billion according to sources that spoke with CNBC reporter Michael Sheetz. The same source indicated that demand for SpaceX equity remains strong as the company seeks to continue extremely expensive development and production programs. Most notably, SpaceX is simultaneously building two full-scale orbital Starship prototypes at separate facilities in Texas and Florida, readying an earlier Starhopper testbed for serious test flights, and is in the midst of ramping up its Starlink satellite production to levels unprecedented in the history of spaceflight.
Put simply, with SpaceX’s Starship and Starlink programs simultaneously entering into capital-intensive phases of development and production, the company has a huge amount of work on its plate. Most of that work involves testing prototypes with technologies that are frequently unprecedented, as well as refining those designs into something final and worthy of serious production. In the case of Starship, a great deal of integrated testing and design finalization lies ahead before SpaceX can even think about starting serial production of its ~50m (160 ft) tall steel Starships or ~60m (200 ft) Super Heavy boosters.
Although large-scale aerospace development programs already tend to be very expensive, SpaceX (led by CEO Elon Musk) has structured its Starship/Super Heavy development program to be extremely hardware-rich. This is another way to say that prototypes are constantly being built, designs are ever-changing, and hardware is constantly being severely damaged (or even destroyed) during fast-paced testing. SpaceX (and Musk) have often been famous for preferring development programs that move fast and break things, delivering knowledge and optimizing designs through lessons learned (often the hard way). SpaceX also values “scrappiness” in its programs, although that sadly ends up coming at the cost of employee pay (below industry standards) and benefits (scarce bonuses, no 401K-matching, extreme hours, minimal work-life balance).
Put it all together and the results of SpaceX-style development programs have frequently defied cemented industry expectations and beliefs. SpaceX has built – from scratch – entire launch vehicles (Falcon 9 V1.0) and spacecraft (Cargo Dragon) 5-10 times cheaper than NASA believed possible. SpaceX has successfully developed a commercially viable style of reusable rockets and took just ~30 months to go from its first attempted landing to a successful booster recovery and less than 15 months after that to reuse its first booster on a commercial, orbital-class launch. Competitors that vehemently denied that SpaceX would succeed are now 5-10 years behind with disinterested responses to the reusable titan that is Falcon 9/Falcon Heavy.
Still, while SpaceX’s record of commercial and technical spaceflight success is second-to-none since the Apollo Program and the early days of the Space Shuttle, even its extraordinarily cost-effective development style requires major funding in the face of ambitions as grand as Starship and Starlink.
Starlink races ahead
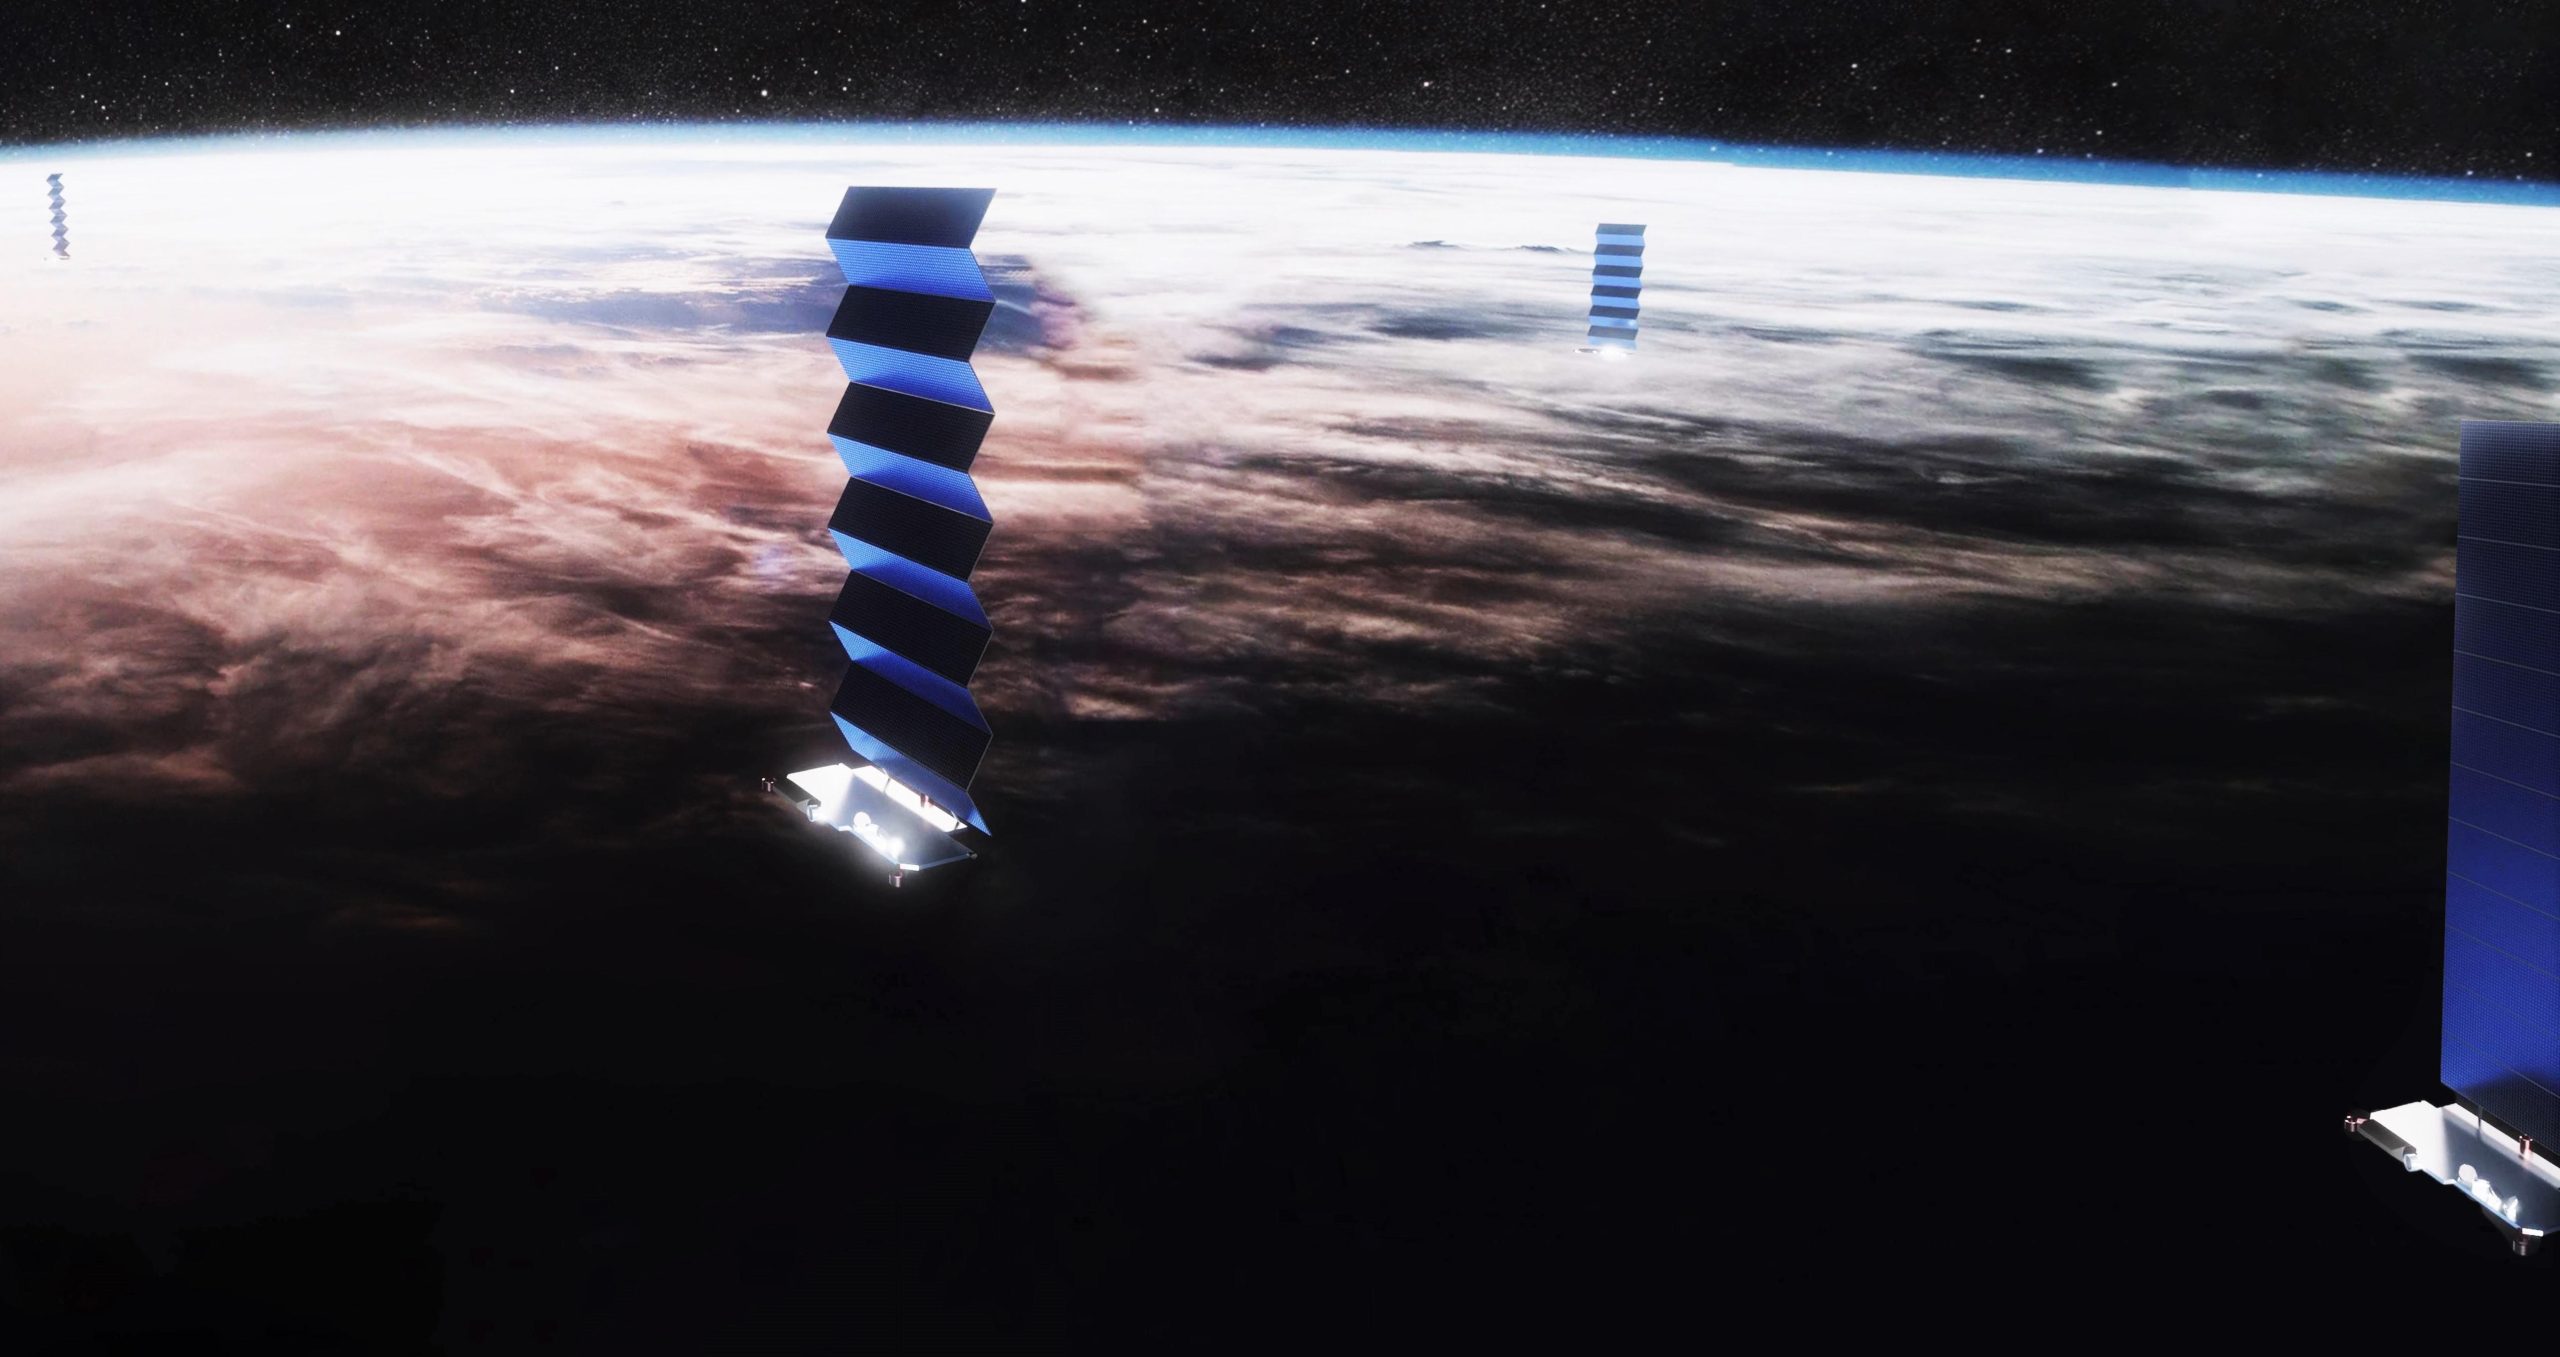
On May 23rd, SpaceX completed an extraordinarily ambitious Starlink launch debut, placing sixty “v0.9” spacecraft into low Earth orbit (LEO). Weighing no less than 16.5 tons (~36,000 lb), SpaceX’s first dedicated Starlink mission also became the heaviest payload the company has ever launched by at least ~30%. Aside from the spectacular statistics associated with the mission, SpaceX also debuted an exotic and largely unprecedented satellite form factor, stacking each flat, rectangular ~230 kg (510 lb) spacecraft like a deck of cards. With Starlink, SpaceX has also flown the first krypton-powered ion thrusters, replacing the traditional xenon to cut as much as $100,000 (or even more) from the cost of each satellite.
“We continue to track the progress of the Starlink satellites during early orbit operations. At this point, all 60 satellites have deployed their solar arrays successfully, generated positive power and communicated with our ground stations. Most are already using their onboard propulsion system to reach their operational altitude and have made initial contact using broadband phased array antennas. SpaceX continues to monitor the constellation for any satellites that may need to be safely deorbited. All the satellites have maneuvering capability and are programmed to avoid each other and other objects in orbit by a wide margin.” — SpaceX, May 31st

~20 days after launch, all 60 satellites are in contact with SpaceX ground controllers and all but 3-4 have managed to successfully begin raising their orbits from ~450 km to 550 km (280-340 mi). Roughly two dozen have already passed 500 km and most should reach their final orbits within 1-2 weeks.
By far the most significant news, however, was CEO Elon Musk’s confidence that SpaceX already has “sufficient capital to build an operational constellation”, likely referring to a constellation of 750-1500 spacecraft capable of either covering the entire US or offering “decent global coverage”. Of note, Musk made this comment days before SpaceX – via SEC filings – effectively announced that it has already raised more than $1B in 2019. A large portion – if not all – of that funding is thus likely bound for Starlink as the program’s shockingly small team of ~400 prepares to aggressively ramp up production.

According to both COO Gwynne Shotwell, Musk, and SpaceX, the company hopes to conduct an additional 1-5 launches of 60 Starlink satellites this year, potentially leaving SpaceX with a constellation of more than 400 satellites – with a total bandwidth of 7 terabits per second (tbps) – after just eight months of launches. Equally significant, SpaceX’s official Starlink.com website states that SpaceX wants to offer real internet service to an unspecified number of US and Canada consumers after just six launches. In other words, SpaceX could deliver the first (possibly alpha or beta) taste of consumer Starlink internet service by the end of 2019.
If SpaceX can deploy the constellation soon and Starlink reaches its cost, performance, and longevity targets, it’s safe to say that SpaceX’s private investors are going to be extraordinarily happy with their financial decision.
Check out Teslarati’s Marketplace! We offer Tesla accessories, including for the Tesla Cybertruck and Tesla Model 3.



Tesla (NASDAQ: TSLA) reports its earnings for Q3 today. Here’s what to expect, as the company will reveal its balance sheet after the market closes on Wednesday.
Tesla already reported deliveries just after Q3 ended, and it demolished Wall Street consensus estimates of roughly 462,000 vehicles. Tesla delivered 486,532 cars in the third quarter, which was a big beat, but was down 2.1 percent from the same quarter last year. Energy storage deployments were 13.7 GWh, up year-over-year.
Tesla showrooms picked clean ahead of Q3 end as demand looks strong
For the quarter, analysts have already compiled their predictions for what Tesla will report this afternoon:
- Total Revenues: $28.34B
- Non-GAAP EPS: $0.43
- Operating Margin: 2.5%
- Operating Income: $721M
- Free Cash Flow: ~-$4.51B
Here are a few things we are looking forward to hearing about on the call:
Automotive Gross Margin and Overall Profitability
This was 16.3 percent in Q2, down from 19.2 percent in Q1, and was impacted by warranty charges and some fading regulatory credits. Consensus implies overall gross margin near 18 percent, but a miss here would potentially reinforce concerns about pricing pressure on its vehicles.
Pay attention to energy storage margins as well, especially since Tesla missed GWh expectations, although it was still a strong quarter.
Robotaxi/Cybercab, Unsupervised FSD, and Optimus Progress
The Say questions from retail investors usually focus on these types of projects, and this quarter is no different. Scaling the Cybercab fleet beyond Austin amid the open NHTSA safety review, timeline for Unsupervised FSD in customer cars, Robotaxi unit economics, and Optimus cost per unit plus when it could start generating revenue, are all things to be looking for.
Any concrete timelines or regulatory path details will likely move the stock more than the near-term numbers. SpaceX merger speculation, which was detailed during SpaceX’s earnings call last night, may also surface, although the key details were shared last night.
Elon Musk just confirmed the Tesla and SpaceX merger step everyone was waiting for
Say Investor Questions
- How does the Cybercab fleet scale past Austin, and what’s the regulatory path outside Texas given NHTSA’s open safety review?
- When can we anticipate FSD unsupervised in customer cars?
- When will the CyberCab be available for customer purchase/ownership?
- What’s the unit economics per paid robotaxi mile, and how does it compare to the thirty-cent target?
- Tesla has acknowledged that HW3 vehicles cannot support unsupervised FSD. When will owners know whether they can upgrade their hardware for free, and when will Tesla provide a clear plan?
The full Earnings Call will be streamed this evening after market close around 5 p.m. this evening.
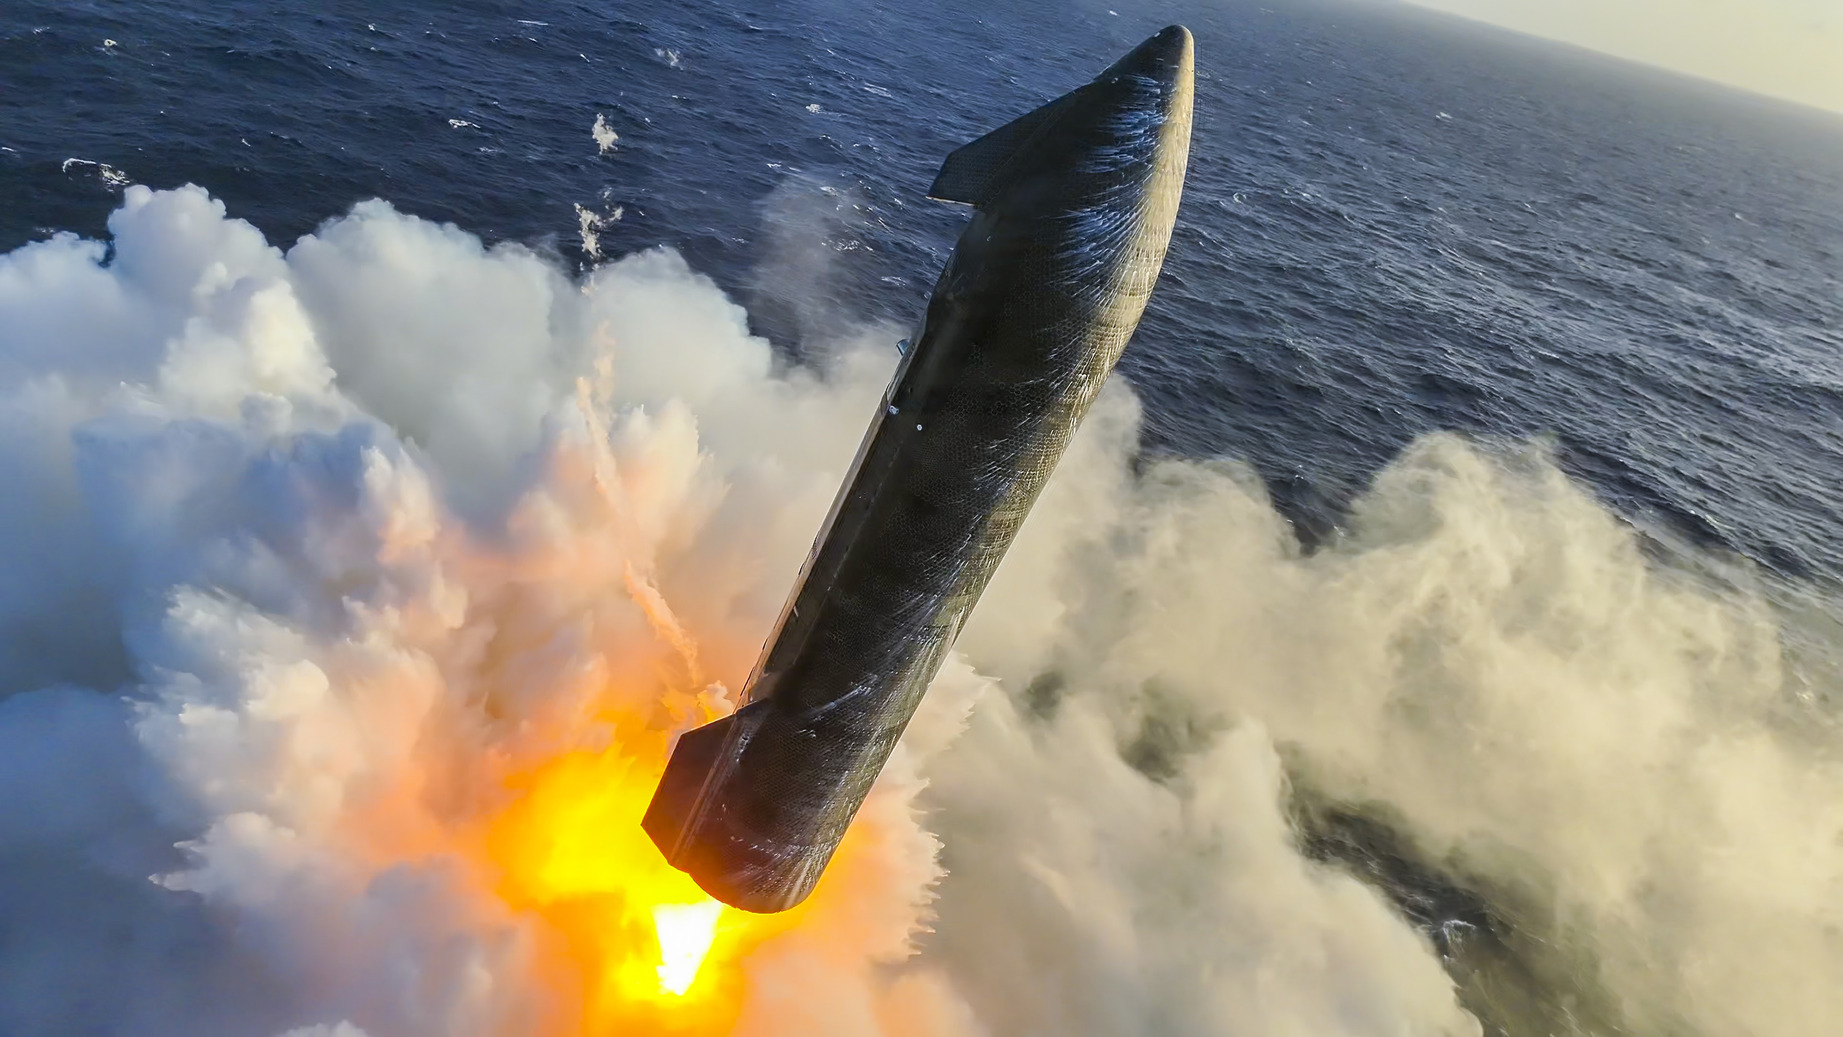
SpaceX confirmed the date of Starship’s 15th launch window with some massive ambitions for the mission, as it will attempt to catch Ship for the first time.
CEO Elon Musk confirmed during SpaceX’s Earnings Call last night on October 20 that it would launch Starship for its 15th test flight in November, and there are some incredible things the company wants to try, making it perhaps the most groundbreaking launch in the program’s history.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
The most major development of the call was SpaceX’s intention to catch Ship alongside catching the Super Heavy Booster, something that has happened in the past. SpaceX showed an animation of the Ship catch, which will be done on the launch tower’s chopsticks:
SpaceX has released a new Starship tower catch animation for the upcoming Flight 15! https://t.co/kStn01Da8u
— Truthful🛰️ (@Truthful_ast) October 20, 2026
This monumental goal is to catch both the Ship and Booster in a dual-catch scenario, an incredible feat since SpaceX has never been able to reuse a Ship after launch. Musk said it would be “the first time that an orbital launch vehicle has been fully recovered,” and said it would be a “profound technology milestone.”
Musk said the odds of success on this first Ship catch attempt are “more likely than not,” but SpaceX is ultimately prepared for more tries moving forward. The SpaceX frontman said that, starting next year, Starship would have a “steady stream” of flights through the end of the year.
The cadence will accelerate in 2027, with Musk stating the company plans to target weekly flights in the first half of 2027 and twice-weekly by year-end.
The Flight 15 attempt follows that of Flight 14, which took off in late September and was Starship’s first orbital mission. It deployed 26 Starlink V3 satellites, accomplished a controlled ocean splashdown of both stages, and shed more light on potential challenges for the program moving forward.
As of now, the Starship program is firing on all cylinders.
Interested in ordering a Tesla? Use my referral code for three free months of Full Self-Driving (Supervised) here.
Wall Street analysts rapidly raised price targets on SpaceX (NASDAQ: SPCX) after the company reported a bullish third quarter for 2026 following the market close on October 20. Shares were sent sharply higher in after-hours and premarket trading.
SpaceX posted revenue of $14.6 billion, a 161 percent year-over-year increase that comfortably topped consensus estimates, which fell near $12.7 billion. The company also posted a net profit of $4.4 billion from a prior-year loss, with adjusted EBITDA reaching $8.8 billion.
More price target movement:
🚀 Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
🚀 Barclays raised its target to $300 from $254 (Overweight).
🚀 Citi increased its target to $240 from $200 (Buy),
🚀 UBS moved to $230 from $210 (Buy)
🚀TD Cowen raised its target to $224 from $200 (Buy).
🚀Morgan Stanley held an Overweight rating with a $300 target.
🚀Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.— TESLARATI (@Teslarati) October 21, 2026
Its Super Intelligence (AI) division generated roughly $7.6 billion and became the largest revenue contributor, growing nearly 830 percent year-over-year, while the Connectivity segment delivered $5.2 billion on strong subscriber additions that lifted the consumer base to 13.6 million for Starlink.
The Earnings Call proved especially catalytic, as CEO Elon Musk and CFO Bret Johnsen outlined Q1 2027 revenue guidance of $33 billion to $37 billion, which was far above the roughly $22 billion analysts had modeled, alongside fourth-quarter capital-expenditure plans of $35 billion to $40 billion focused on AI compute infrastructure at sites including Memphis and Southaven.
SpaceX delivers blockbuster Q3 results as Super Intelligence segment booms
Management targets 2.5 to 3 gigawatts of nameplate compute capacity by year-end and discussed pathways to 13 gigawatts or more by the end of 2027. Musk described relentless demand from hyperscalers and other customers, with compute pricing supporting payback periods of less than a year and potentially as short as six months.
Additional highlights included Starship’s recent orbital success and V3 satellite deployment, Starlink pricing and enterprise momentum, rapid Grok Bot adoption, spectrum expansion plans, and the formation of special committees to explore a possible combination with Tesla.
These elements prompted a wave of price-target increases:
- JPMorgan more than doubled its target to $500 from $240 while maintaining an Overweight rating.
- Cantor Fitzgerald lifted its target to $345 from $246 (Overweight).
- Barclays raised its target to $300 from $254 (Overweight).
- Citi increased its target to $240 from $200 (Buy),
- UBS moved to $230 from $210 (Buy), and
- TD Cowen raised its target to $224 from $200 (Buy).
- Morgan Stanley held an Overweight rating with a $300 target.
- Other firms also adjusted higher, including Wells Fargo (to $274 from $214) and Clear Street (to $248 from $217). Analysts broadly cited the strong quarterly print, accelerating AI compute expansion, Starlink progress, and Starship milestones as drivers of higher long-term growth and earnings power.
Shares, which closed at $147.79 on October 20, jumped roughly 8 percent in early premarket trading on October 21 as investors digested the results and the newly elevated Street targets.
The average analyst price target has moved higher, which reflects greater conviction in SpaceX’s trajectory across launch, connectivity, and the Super Intelligence business, even as elevated spending remains a point of focus.

Tesla reports Q3 Earnings today: here’s what to expect

SpaceX confirms Starship 15 launch window with massive ambitions

SpaceX stock gets a slew of price target boosts after bullish earnings call

SpaceX reveals how its 1 Million AI satellite network will work and prevent space collisions

Tesla Roadster: Three configs, one can fly, 0-60 in 0.8 seconds


